Facebook
 X
 Pinterest
 Copy Link
New Home Prices Hit a 5-Year Low
If you’ve assumed a newly built home is out of reach, it may be time to take another look.
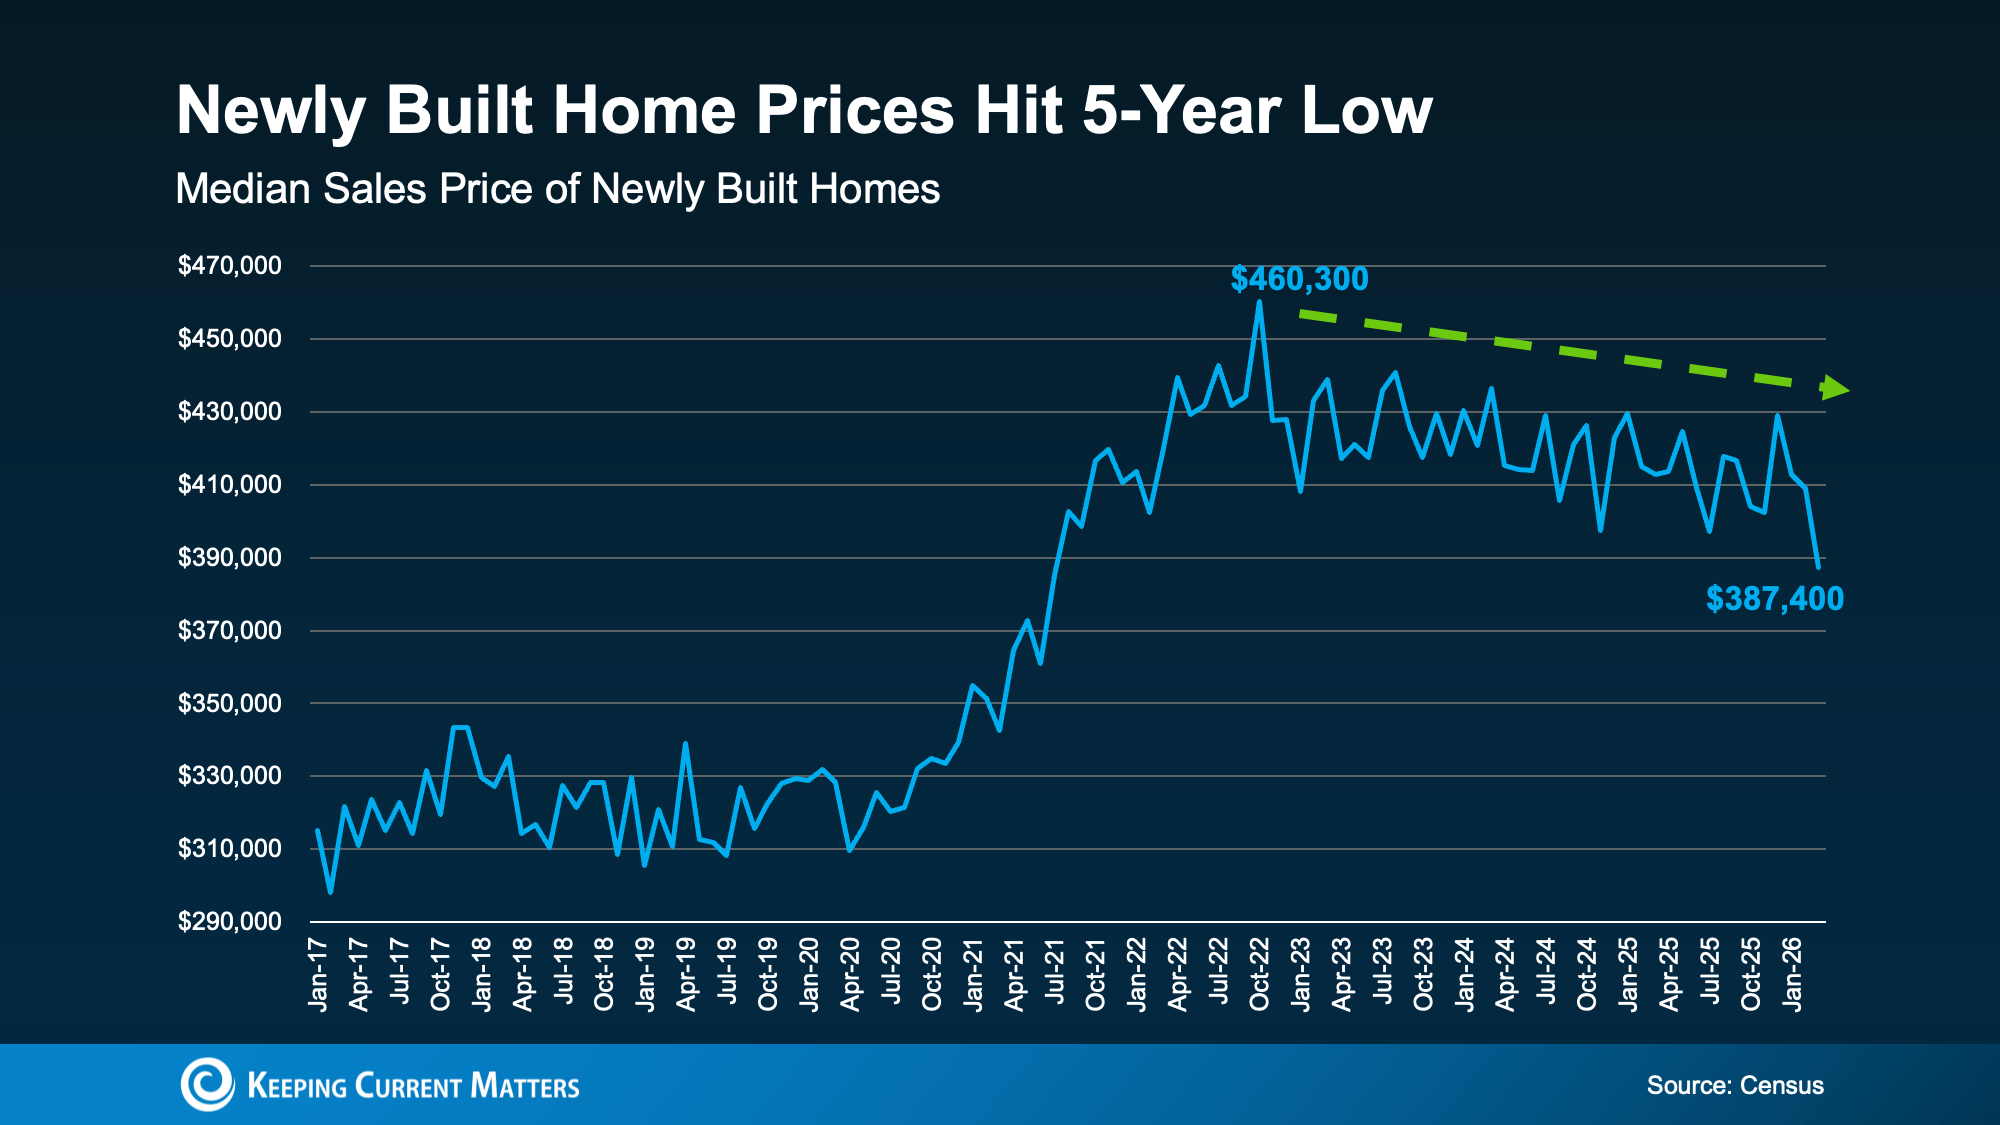
The median sale price of a newly built home has dropped to its lowest level since 2021, according to the latest United States Census Bureau data. At the same time, many builders are still offering incentives to help attract buyers.
New Home Prices Have Come Down
After climbing sharply during the pandemic years, new home prices have eased. The median sale price of a newly built home is now around $390,000, which is the lowest level in nearly five years.
Local markets can vary, but the national trend may work in buyers’ favor, especially in the entry-level price range. According to Zonda, prices in the entry-level new construction segment have dropped about 2.7% over the past 12 months, which is more than any other price tier.
This doesn’t mean every newly built home is suddenly affordable now. But, it does mean that buyers may be seeing some of the best new construction pricing since 2021.
Why Lower New Home Prices Do Not Mean a 2008 Repeat
Lower prices can make some buyers wonder whether the new home market is in trouble. But today’s conditions are very different from 2008.
Builders are being more intentional about how much inventory they bring to market. Instead of letting homes pile up, many are using pricing adjustments and incentives to keep inventory moving.
It’s also important to keep perspective. Even with recent price improvements, new home prices are still higher than pre-pandemic norms. This isn’t a market crash. It’s a builder strategy designed to match today’s buyer demand.
Builders Are Still Offering Buyer Incentives
Lower prices aren’t the only potential advantage for buyers. According to the National Association of Home Builders (NAHB), 60% of builders are currently offering some form of incentive to attract buyers.
Common builder incentives include:
- Closing cost assistance: Some builders may help cover upfront costs, which can reduce the cash buyers need at closing.
- Upgrade packages: Builders might include premium finishes, appliance packages, or design features at no additional cost.
- Mortgage rate buydowns: Some builders might pay to reduce a buyer’s mortgage rate, which can lower the monthly payment.
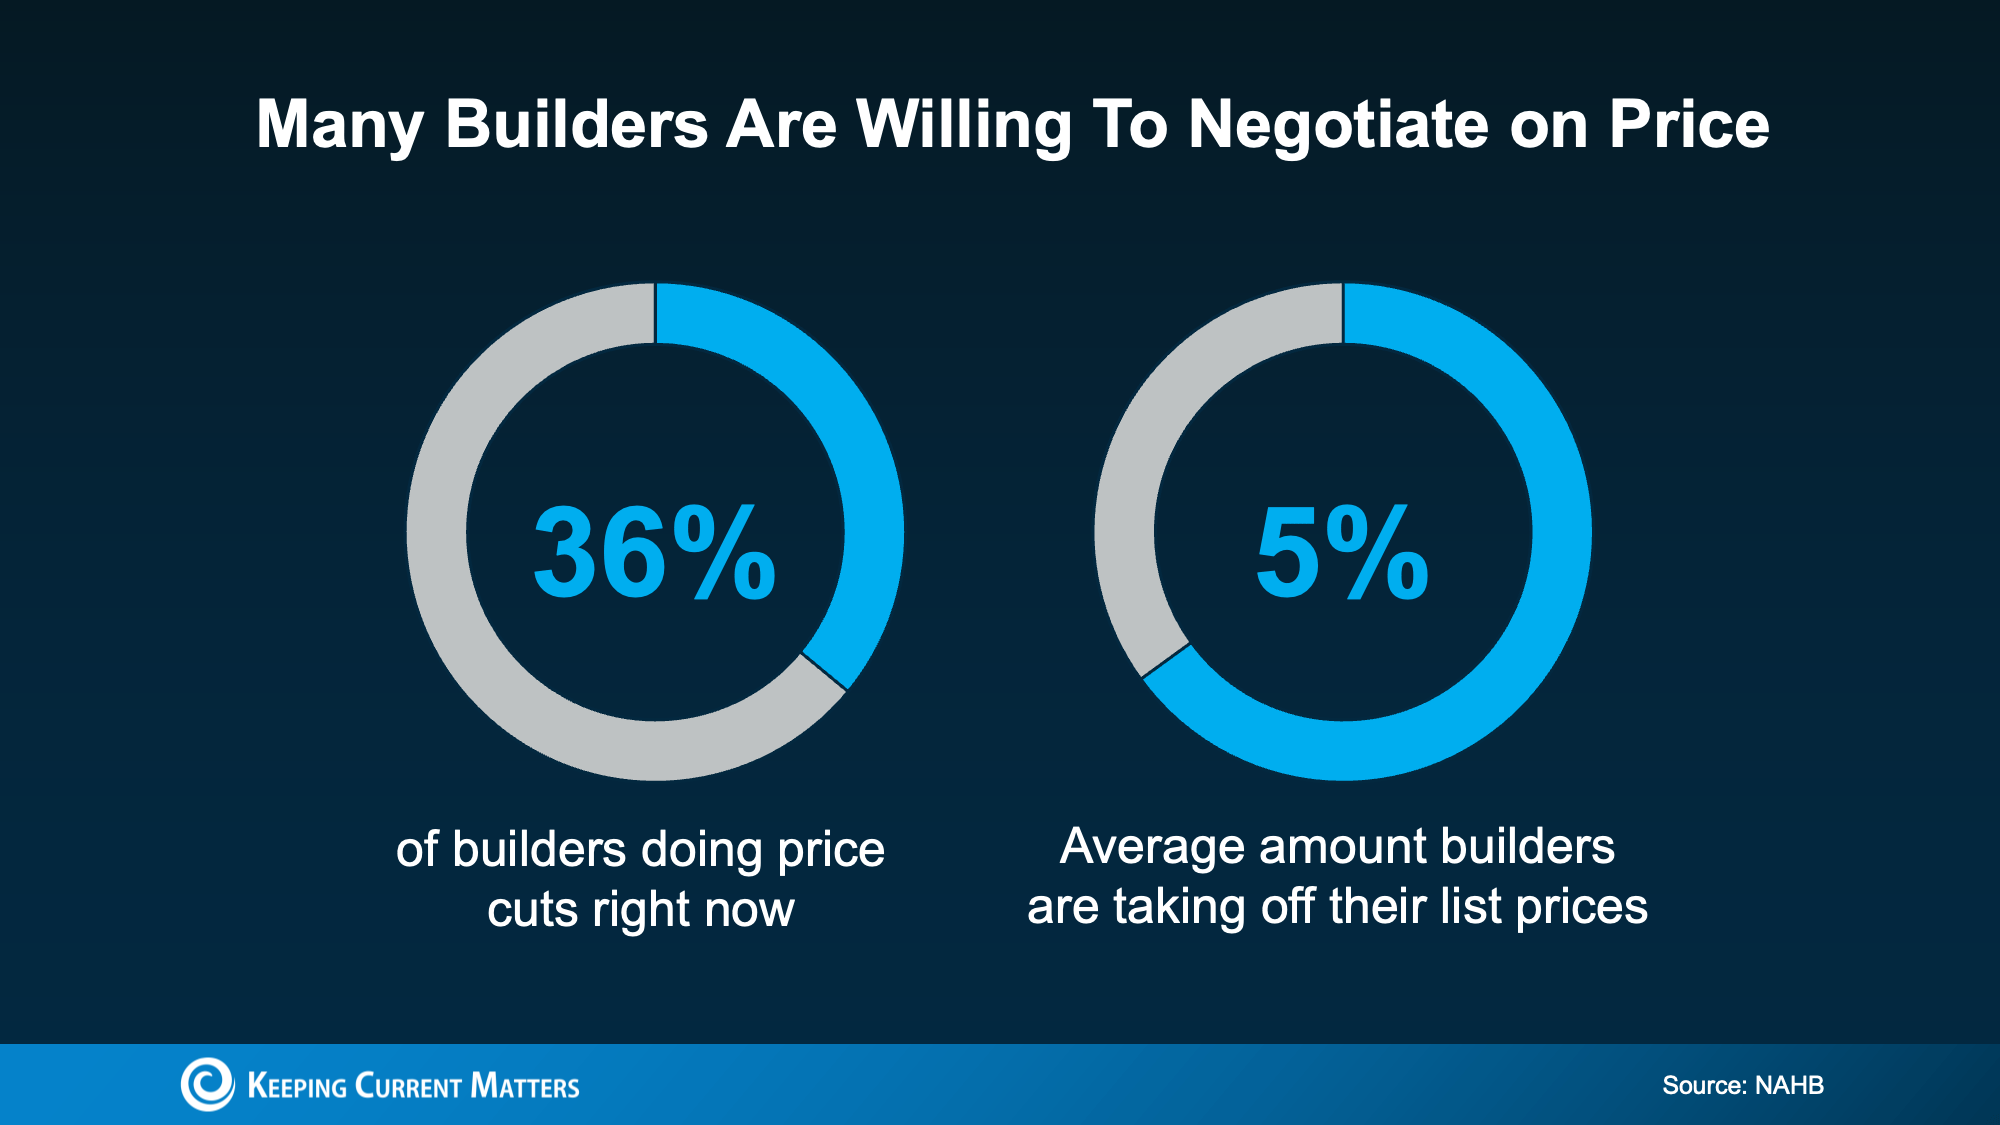
- Price cuts: More than one in three builders, or 36%, are cutting prices right now, with reductions averaging around 5% off list price.
Why Builders May Be More Flexible Than Sellers
Many buyers assume builders won’t negotiate on price. But builders often have different motivations than individual homeowners.
A homeowner may decide to take a listing off the market rather than accept a lower price. Meanwhile, builders usually need to sell the homes they’ve already built so they can keep projects moving.
As Joel Berner, Senior Economist at Realtor.com, explains:
“. . . many existing-home sellers resort to taking down their listing instead of taking less than their desired price, but builders are more motivated to sell their inventory than owner-occupants . . .”
That doesn’t mean every builder will negotiate the same way. But it does mean buyers should ask about current pricing, incentives, rate buydowns, and available inventory before assuming a new build is outside their budget.
What This Means for Home Buyers
If you’re shopping for a home, newly built homes may deserve a closer look. Between lower new home prices and ongoing builder incentives, some buyers may find opportunities they did not expect.
Before you make a decision, look at the whole picture:
- The purchase price
- Builder incentives
- Closing cost assistance
- Mortgage rate buydown options
- Included upgrades
- Monthly payment estimates
- Location, commute, and long-term housing needs
A local real estate agent can help you compare new construction homes with existing homes in your market, review builder incentives, and understand what questions to ask before you make a move.
Bottom Line
New home prices have eased, and many builders are still offering incentives to attract buyers. That could give today’s home shoppers more room to explore newly built homes than they’ve had in recent years.
If you’re curious about new construction homes in your area, connect with a local real estate professional to see what’s available and what builder incentives might be offered in your market.
Record High Mortgage Debt: What Do Buyers Need To Know?
Mortgage debt in the United States has hit a record high, and at first glance, that looks like a warning sign for the housing market.
It’s an attention-grabbing headline for sure. After all, when people hear “record debt,” most think back to the 2008 housing crash and wonder if today’s market is heading in the same direction.
But headlines leave out the real story.
It’s true that mortgage debt is higher than ever. But, so are home values and homeowner equity. When you add in those missing pieces, the real picture becomes much less alarming than you might think.
Mortgage Debt Is High, But So Is Homeowner Wealth
New data from the Federal Reserve says total U.S. mortgage debt is now around $14.4 trillion, and the Federal Reserve Bank of New York found it was $13.19 trillion at the end of March 2026. Both numbers are record highs, but they’re missing some critical perspective.
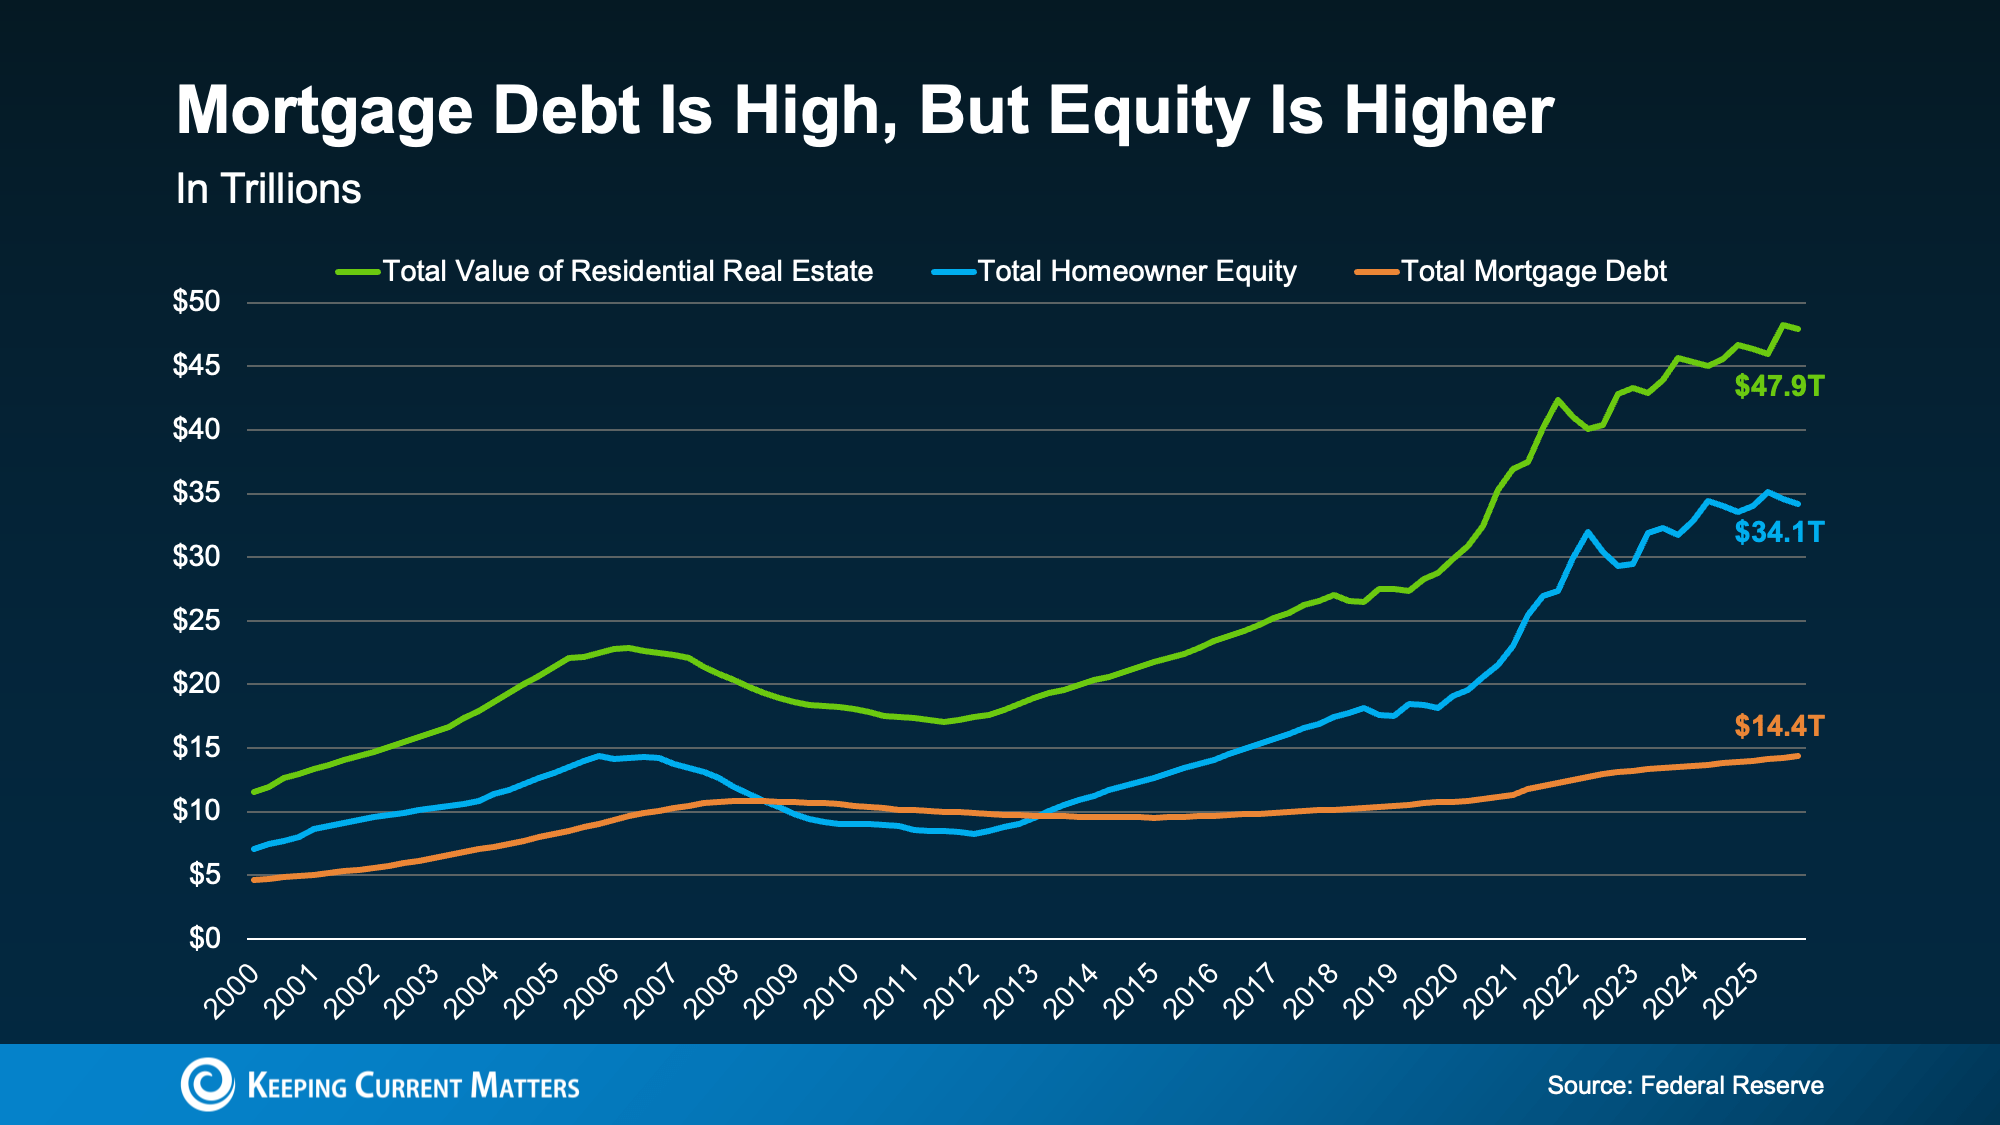
Meanwhile, the total value of U.S. homes is about $47.9 trillion, while homeowners collectively hold roughly $34.1 trillion in equity. In other words, homeowners owe a lot, but they also own a great deal more.
Mortgage debt has peaked, but that alone doesn’t determine the health of the housing market. What matters more is how much equity homeowners have compared to what they owe.
Right now, homeowner equity is more than double the amount of mortgage debt, and near its own historical peak. That’s a very different situation from the years surrounding the 2008 housing crisis.
Why Today’s Housing Market Is Not Like 2008
During the housing crash, many homeowners owed more on their mortgages than their homes were worth. When home prices fell, they had little to no financial cushion. That caused a wave of serious distress, including short sales and foreclosures.
Today’s market looks very different.
Homeowners have significantly more equity than debt, which gives them options. Even if home prices soften in some areas, many owners still have a substantial financial buffer. They can sell, refinance when conditions improve, or use their equity strategically if needed.
That equity cushion is one of the biggest reasons today’s housing market is on much stronger footing than it was during the last crash.
Many Homeowners Have Little or No Mortgage Debt
The strength of today’s market is even clearer when you look at homeowners individually. Recent data from ATTOM and Census illustrate this point.
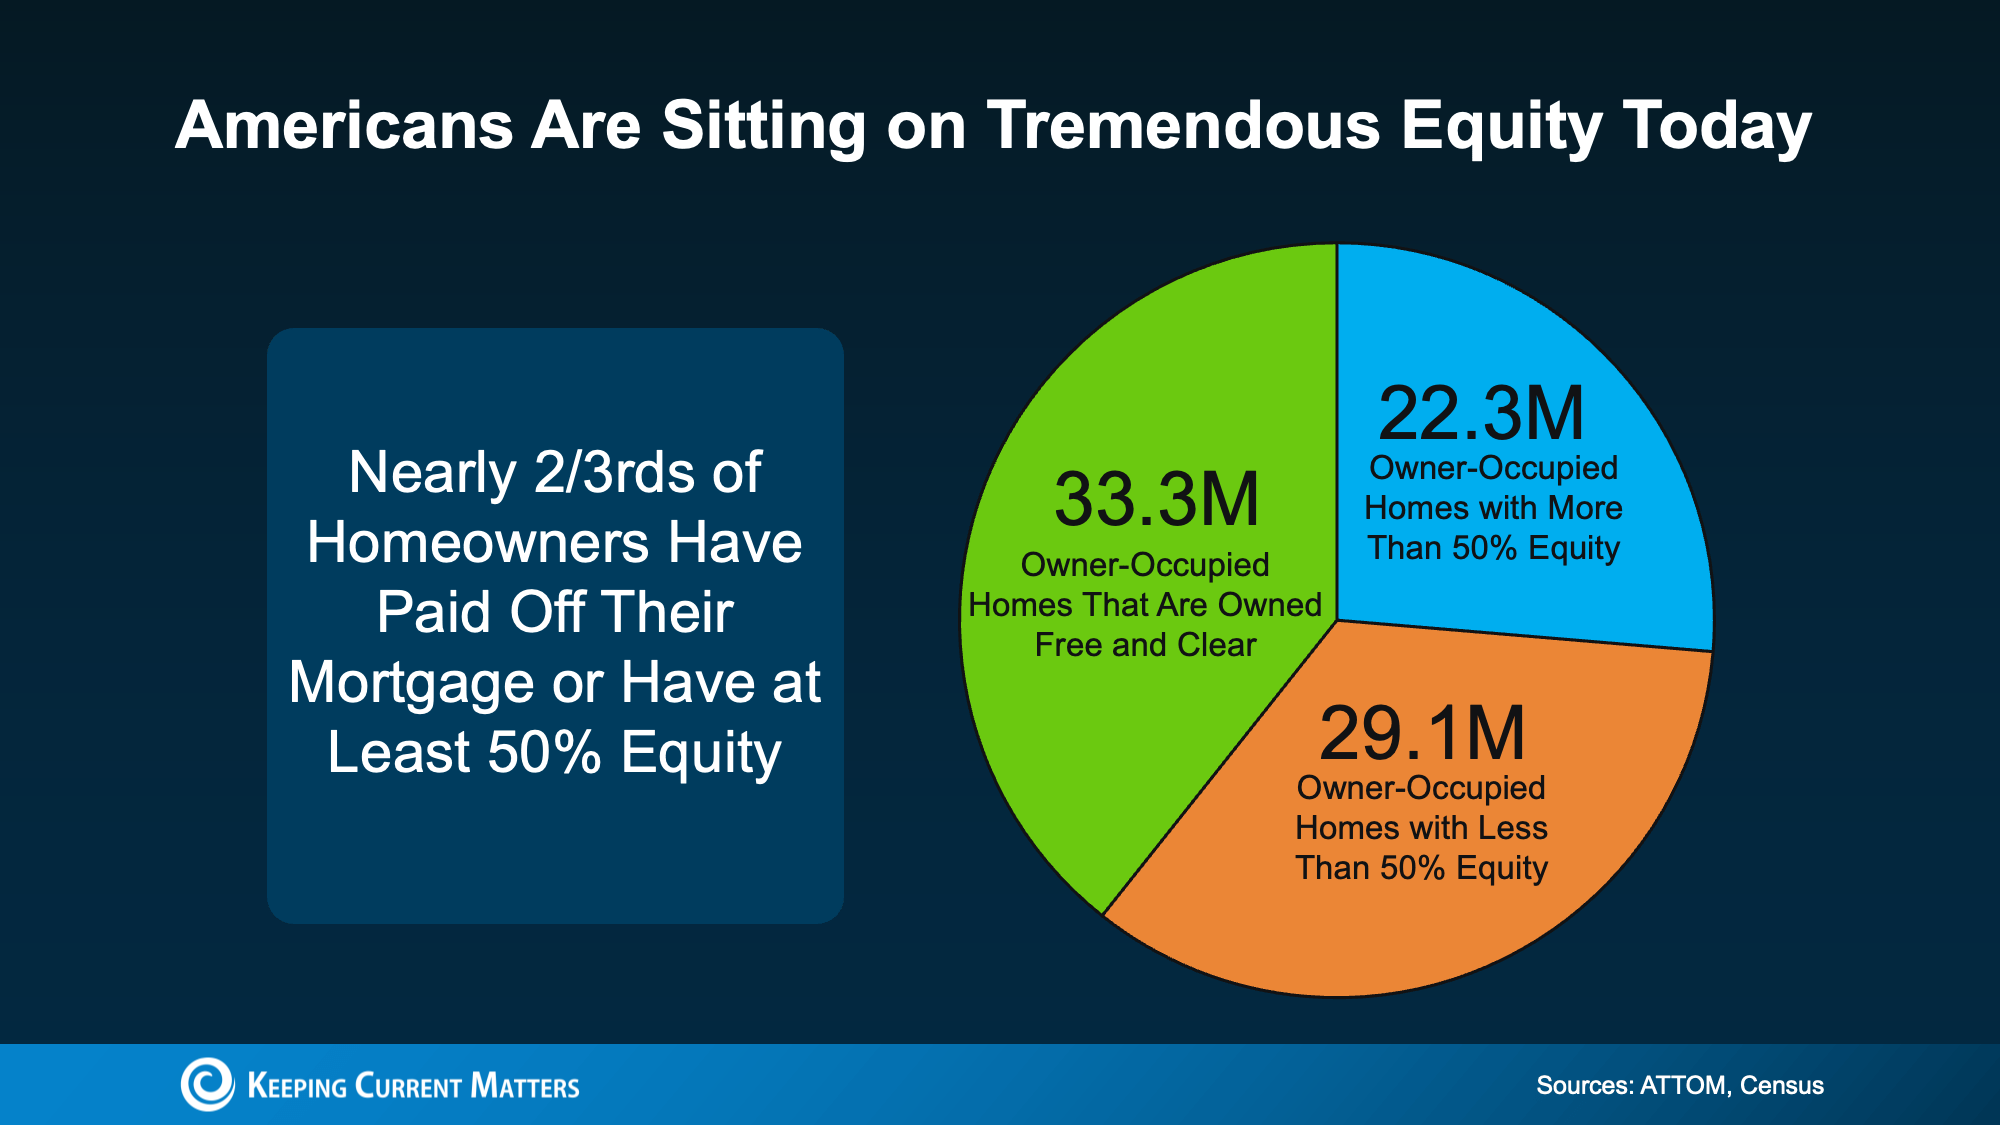
Of all owner-occupied homes in the United States, 33.3 million are owned free and clear, meaning there’s no mortgage on the property at all. On top of that, 22.3 million homeowners have more than 50% equity in their homes.
Put those groups together, and nearly two-thirds of homeowners are in an exceptionally strong financial position. Some owe no mortgage debt, and others owe far less than their homes are worth.
Those are the signs of a strong market, not a fragile one.
What About Homeowners With Less Than 50% Equity?
The remaining group includes homeowners with less than 50% equity. But these homeowners aren’t necessarily in trouble.
Many of these homeowners are simply recent buyers. Since equity builds over time through mortgage payments and home price appreciation, newer buyers naturally tend to have less equity than people who have owned their homes for years.
Low equity doesn’t always signal financial stress or threat of foreclosure. Often, it just means someone is a first-time buyer in early homeownership.
The Real Story Behind Record Mortgage Debt
Mortgage debt is a critical piece of the housing market’s health, but it’s only one piece it.
When you also consider record or near-record home values, strong homeowner equity, and the number of people who own their homes outright, there’s far less cause for alarm.
Homeowners today aren’t severely overleveraged the way they were before the 2008 crash. Many have meaningful equity, and most have no mortgage debt at all.
Bottom Line: Strong Equity Balances High Debt
Dramatic headlines about record mortgage debt can make it seem like the housing market is in trouble, but the actual data tell a more reassuring story.
Home values are high. Homeowner equity is strong. And a large share of homeowners are in a stable financial position.
So while mortgage debt has reached a record level, today’s market has a much stronger foundation than recent headlines would suggest.
No matter if you’re thinking about buying, selling, or simply trying to understand what these numbers mean for your local market, talking with a trusted real estate professional can help you learn the real story.
Are Home Prices Going To Fall? Here’s What Buyers Should Know
One of the biggest questions buyers are asking right now is: Will home prices fall after I buy?
It’s a common concern. Buying a home is a major financial decision, and no one wants to feel like they bought too early, or too late. With headlines pointing to changing prices in some markets, it’s easy to want to play it safe by waiting.
But the short-term noise isn’t the whole story. While some local markets may see temporary dips, the bigger, long-term picture is much different: home prices historically rise over time.
What Housing Market Data Shows
When you look at long-term housing data, one trend becomes clear. Home values have generally moved upward for decades.
Yes, there have been exceptions. The housing crash of 2008 is the most dramatic example. And in some years, certain markets have seen slight declines. But outside of major disruptions, home prices have typically either held steady or increased, and data from Case-Shiller and Biello shows this.
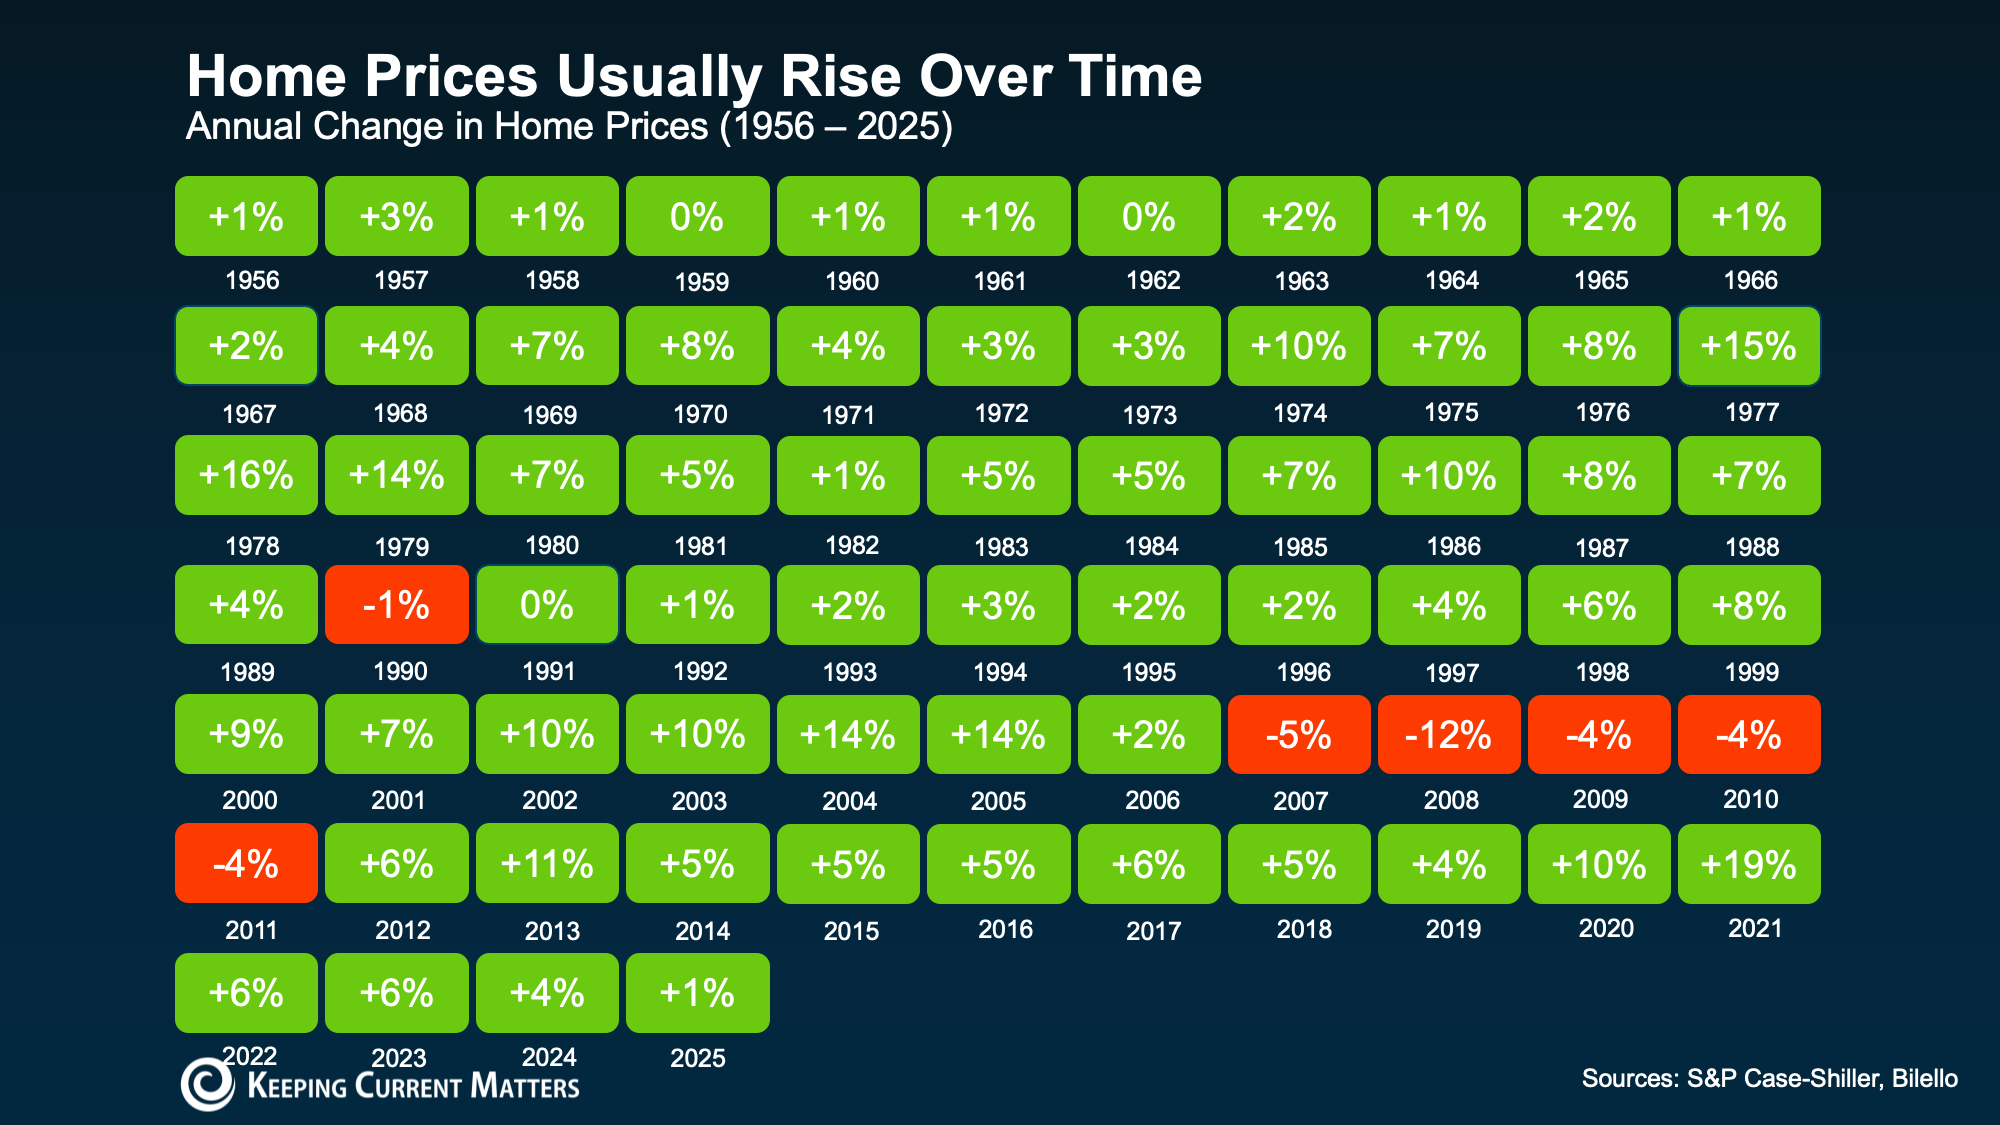
That long-term track record is important for buyers to understand. Real estate is not usually about what happens over the next few weeks or months. It’s about what happens over several years.
Short-term price drops can happen, especially in markets where inventory is rising or buyer demand has cooled. But historically, those dips have proven to be temporary.
Why Home Prices Tend To Rise Over Time
There are several consistent reasons home prices tend to increase in the long run.
People Always Need Homes
Life changes keep the housing market moving. People get married, have children, change jobs, retire, downsize, or relocate to be closer to family. No matter what the market is doing, people always need places to live.
Steady demand like this helps support home values over time.
Housing Supply Is Still Limited
Even though more homes may be available for sale than there were during the tightest years of the market, many areas are still dealing with housing shortages.
When there aren’t enough homes to meet buyer demand, prices tend to stay elevated. Even when demand slows, limited inventory helps prevent dramatic price drops in most markets.
Inflation Plays a Role
Over time, the cost of goods and services tends to rise, and housing is no exception. Land, labor, materials, and construction costs all influence home values.
As the everyday cost of living inflates, home prices naturally move higher too.
What This Means If You’re Thinking About Buying
It’s natural to worry about whether home prices will drop after you buy a home. That concern is especially common among first-time buyers trying to make a smart financial decision.
But what matters most is your own expected timeline.
If you’re planning to buy a home and stay there for several years, short-term market movements matter less. That’s because time gives your home more opportunity to appreciate in value, helping you ride out the kind of ups and downs we’re seeing in some markets.
That’s why many real estate professionals recommend buying only when you expect to stay in the home for at least five years. While there’s no guaranteed timeline, a longer-term approach often gives homeowners a better chance to benefit from rising values.
Real Estate Is Local
Another critical point to remember is that not all housing markets are the same.
Some areas may see home prices soften. Others may continue to rise because demand is strong and inventory remains low. National headlines can give you a general idea of what’s happening, but they don’t always reflect conditions in your specific city, neighborhood, or price range.
That’s why local market insight matters. A trusted real estate agent can help you understand whether prices are rising, flattening, or adjusting in your area.
Don’t Try To Time the Market Perfectly
Trying to buy at the exact bottom of the market is extremely difficult. By the time it’s clear prices have bottomed out, competition may already be increasing again.
Instead of focusing only on timing, focus on whether buying makes sense for your life, your finances, and your long-term goals.
Ask yourself:
- Can I comfortably afford the monthly mortgage payment?
- Do I plan to stay in the home for several years?
- Does buying now support my lifestyle and financial goals?
- Am I prepared for the responsibilities of homeownership?
If the answer is yes, buying may still make sense, even if prices fluctuate in the short term.
Bottom Line: Most Price Drops Are Temporary
So, are home prices going to fall? In some markets, small short-term declines are possible. Historically though, data shows home prices strongly tend to rise over time.
That’s why buying a home is often considered a long-term investment, not a short-term gamble.
You don’t have to buy before you’re ready. But if homeownership fits your goals and you plan to stay put for a while, today’s market headlines shouldn’t scare you away.
For the most reliable picture, talk with a local real estate agent who can explain what home prices are doing in your area and help you decide whether now is the right time to make a move.
What Foreclosure Headlines Are Missing About Today’s Housing Market
You’ve probably seen the headlines: foreclosures are on the rise. And if that immediately makes you think of the 2008 housing crash, you’re not alone.
For many homeowners and buyers, the word “foreclosure” brings back memories of the Great Recession, when distressed properties flooded the market and home values fell sharply. But today’s housing market is very different.
Yes, foreclosure activity has increased, but the bigger picture doesn’t point to a crash. Rather, it shows a market slowly shifting back to normal after several unusual years.
Foreclosures Are Rising, But Still Down Historically
According to data from ATTOM, foreclosure filings are up 26% compared to a year ago and have now increased for five straight quarters. That’s definitely worthy of attention, but it doesn’t mean the housing market is in trouble.
A clear perspective requires a bit of context.
Foreclosure numbers were unusually low in 2020 and 2021 because of pandemic-era protections, including the government’s foreclosure moratorium. Those were exceptional years with totally abnormal market conditions.
A better comparison is 2017, 2018, and 2019, which were the last few years before the pandemic disrupted the housing market. When you compare today’s foreclosure activity to those years, filings are still lower than pre-pandemic levels.
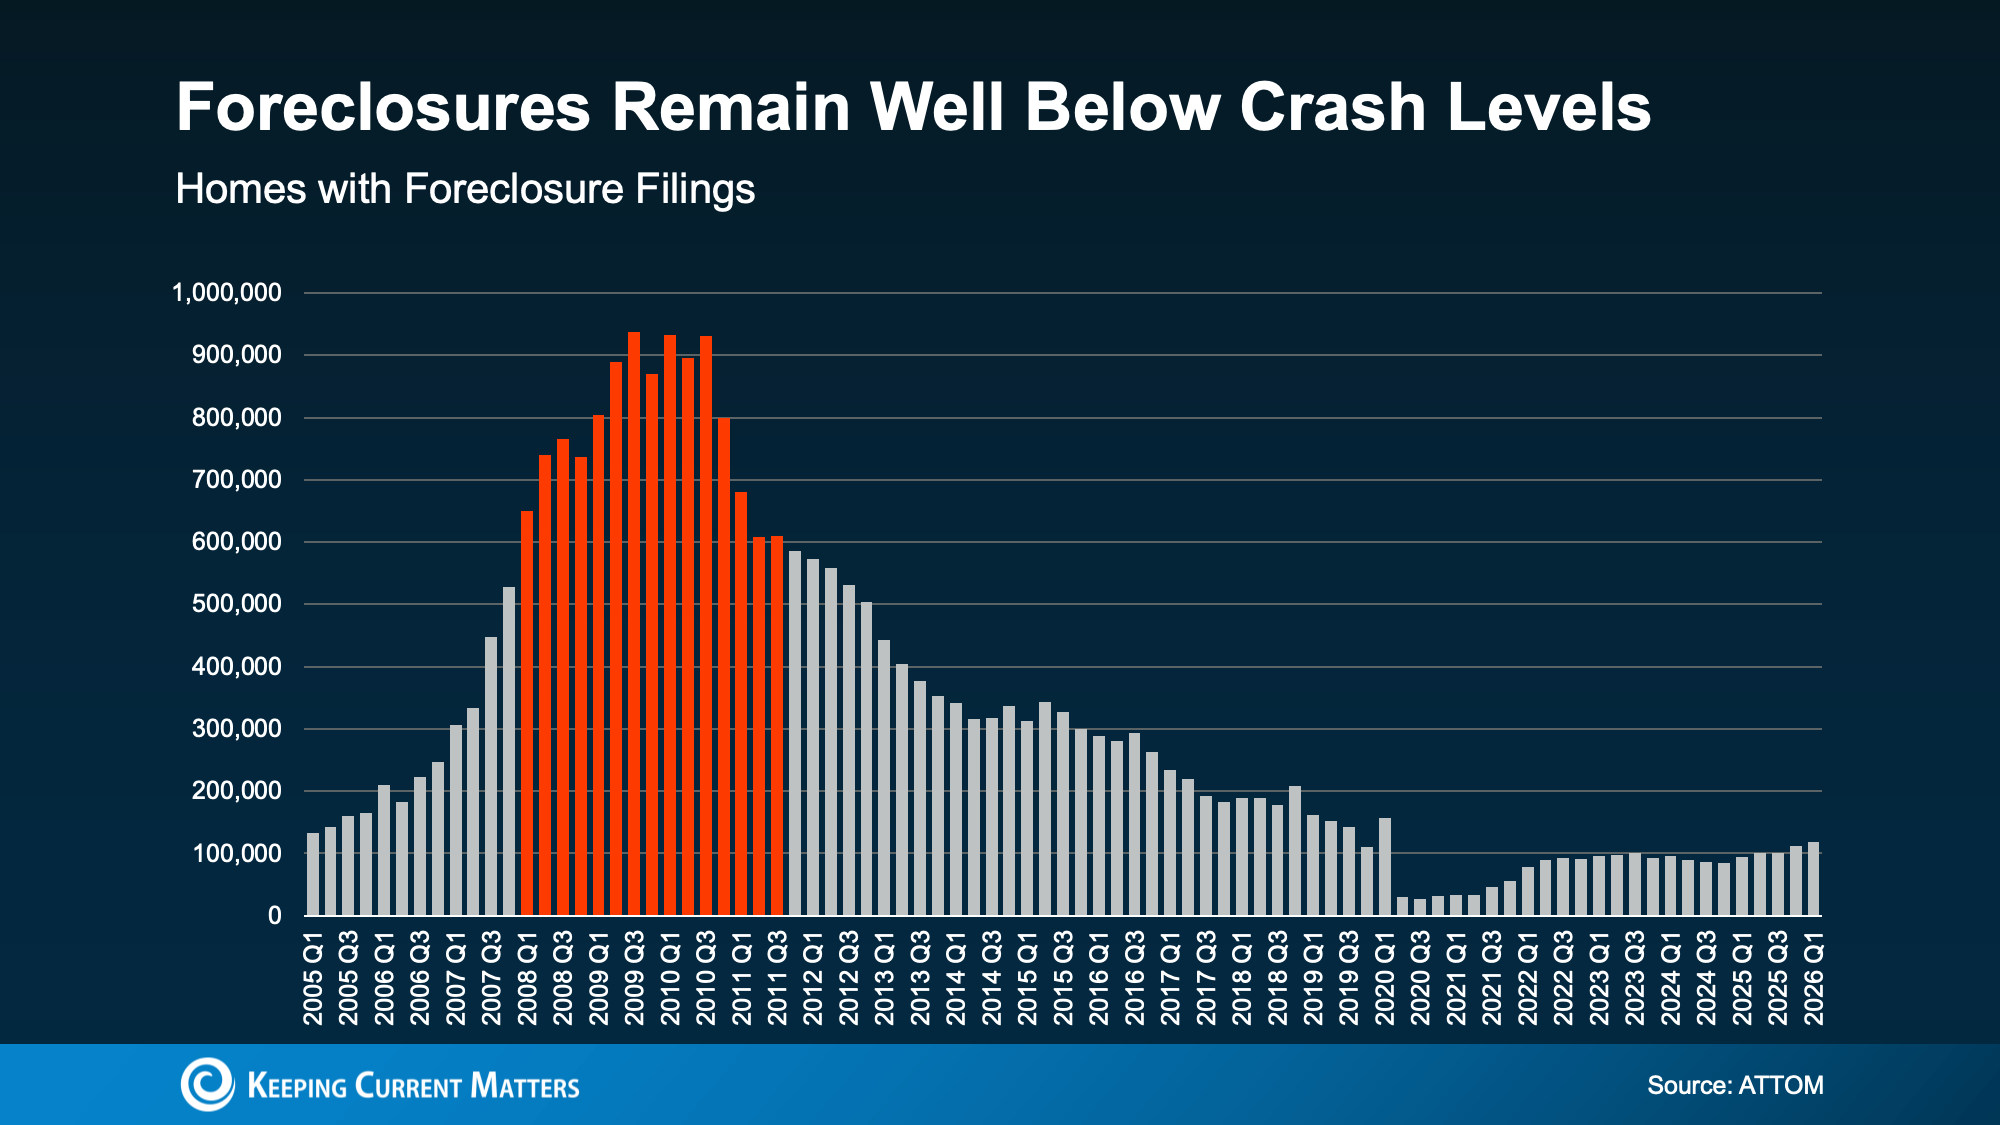
This shows the current increase in foreclosures is more about normalization than distress. The market isn’t returning to 2008 conditions: it’s slowly moving back toward a more typical level of activity.
And compared to the foreclosure wave during 2008 the housing crash, today’s numbers remain far, far lower.
Why Today Is Not Like 2008
One of the biggest differences between now and 2008 is homeowner equity.
During the last housing crash, many homeowners owed more on their mortgages than their homes were worth. That left them with few to no options. Selling often wasn’t possible because selling wouldn’t cover their remaining mortgage balance. For many people, foreclosure became the only path forward.
Today, most homeowners are in a much stronger position.
According to Cotality, the average homeowner has roughly $295,000 in home equity. Home equity like that creates options, even for someone who is struggling financially.
If a homeowner has enough equity to cover their mortgage balance and selling costs, they may be able to sell their home, pay off what they owe, protect their credit, and potentially walk away with money.
That’s a very different picture from 2008, and one that doesn’t point to foreclosures rising out of control.
Foreclosure Filings Don’t Always Lead to Foreclosure
Another important point that often gets lost in the headlines is this: a foreclosure filing does not always mean someone loses their home.
Foreclosure filings only show that the process has started, but many homeowners find a solution before the process is completed. Some work out an agreement with their lender. Others sell their home before foreclosure is finalized. Some may qualify for loan modifications or other assistance.
That’s why completed foreclosures are typically much lower than total foreclosure filings.
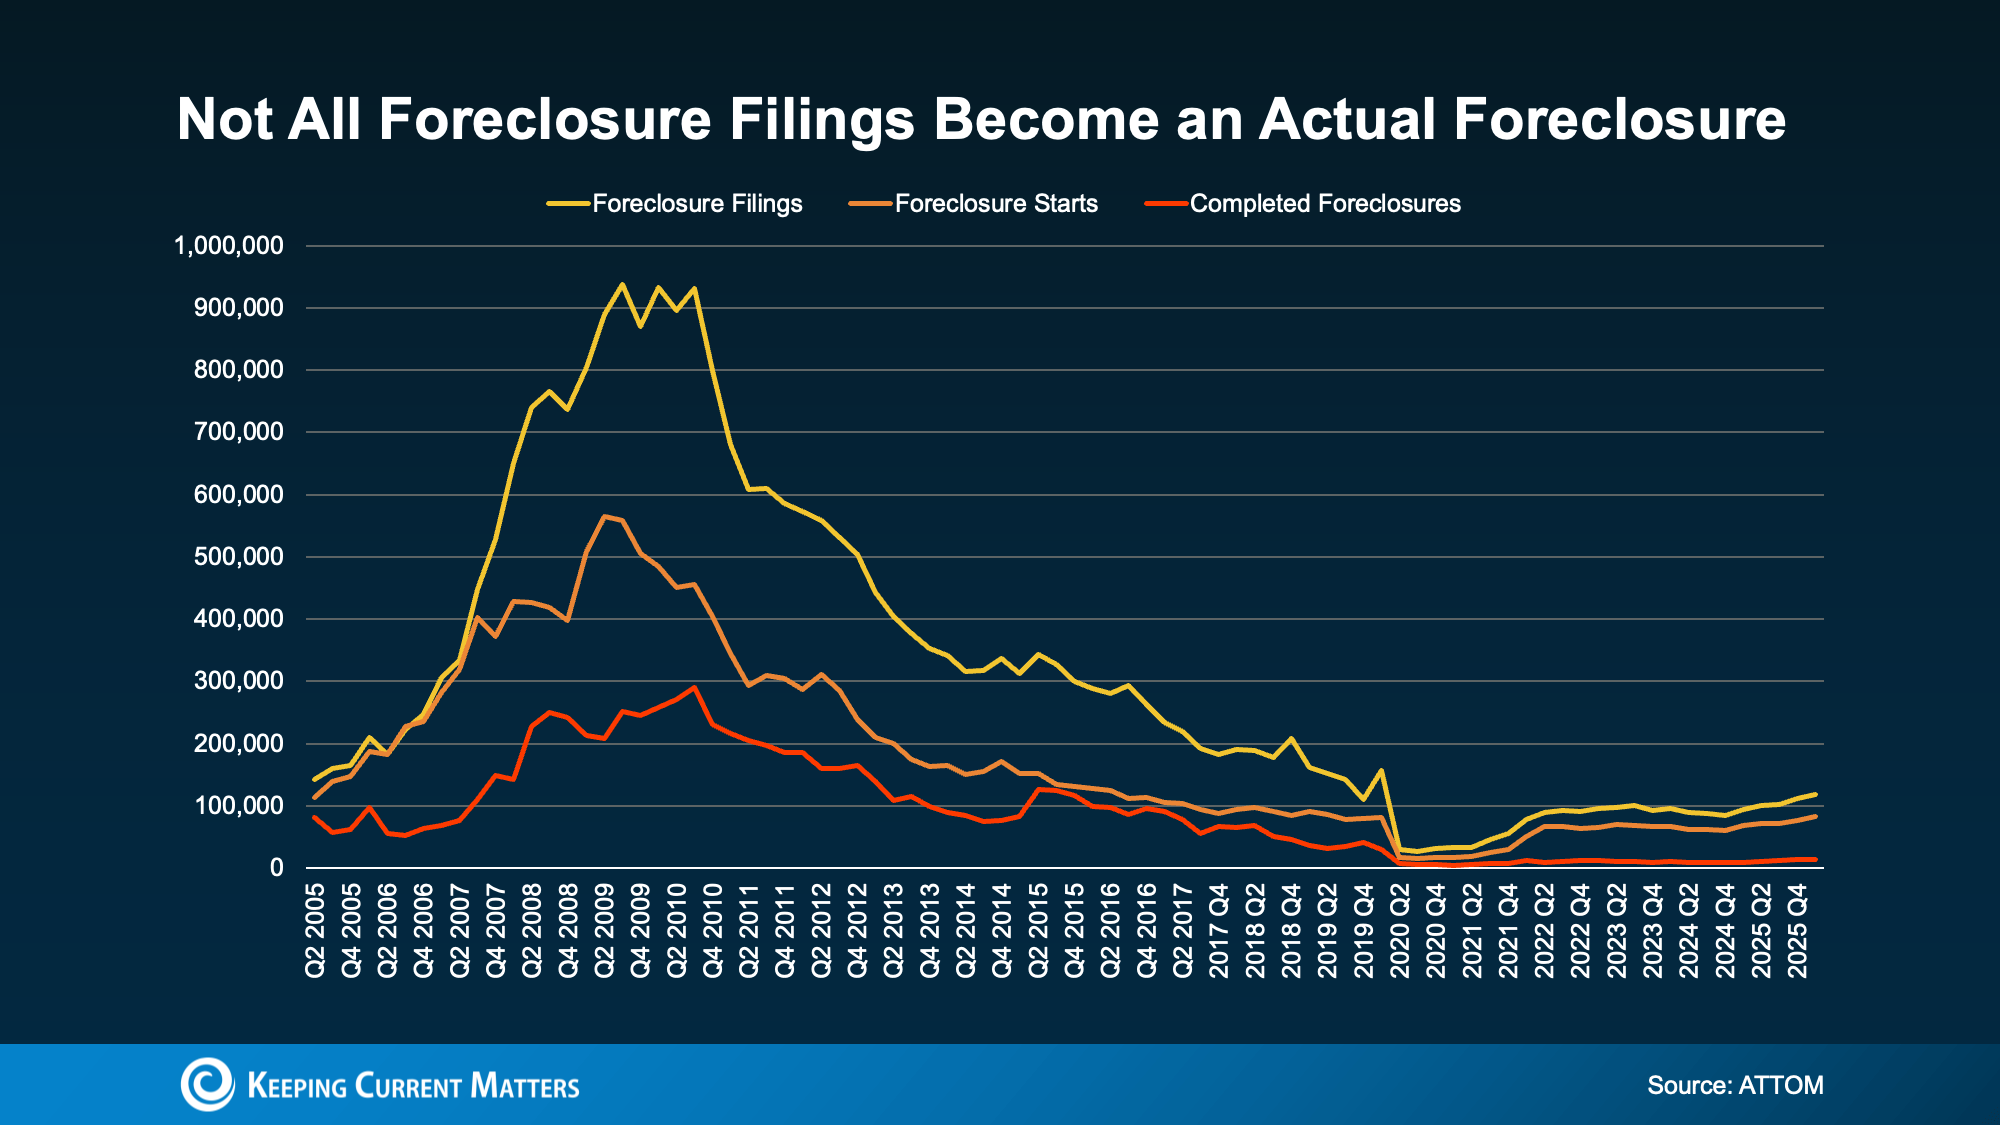
According to ATTOM’s data, completed foreclosures have barely risen despite the jump in filings. The home equity that many homeowner’s have now is a huge reason for this. Strong homeowner equity gives many people a path forward that doesn’t end in losing their home.
Struggling Homeowners Still Have Options
If you’re behind on mortgage payments or worried you may fall behind soon, the most important thing to know is that you may have more options than you think.
Missing a payment does not automatically mean you’ll lose your home.
Most lenders would rather work with you than go through foreclosure; the process is costly and time-consuming for them too. Depending on your situation, they may be able to discuss options such as:
- A repayment plan
- Temporary forbearance
- Loan modification
- Other hardship assistance programs
The sooner you contact your lender, the sooner you’ll be able to explore your options. Waiting too long can make the situation more difficult, especially in states where the foreclosure process moves quickly.
And if selling your home becomes your best option, talking with a real estate professional can help you understand your home’s current value, your equity position, and whether selling could help you avoid foreclosure.
Bottom Line: Don’t Panic
Foreclosure filings are rising, but that doesn’t mean the housing market is headed for another crash. Today’s numbers are still low compared to historical levels, and the equity homeowners have built gives many people options they didn’t have in 2008.
Online headlines and discussion may sound alarming, but the full story is much more reassuring. This is not a repeat of the last housing crisis. It’s a normalizing housing market, and one supported by much stronger homeowner equity.
Do You Need 20% Down? Most First-Time Buyers Pay Less
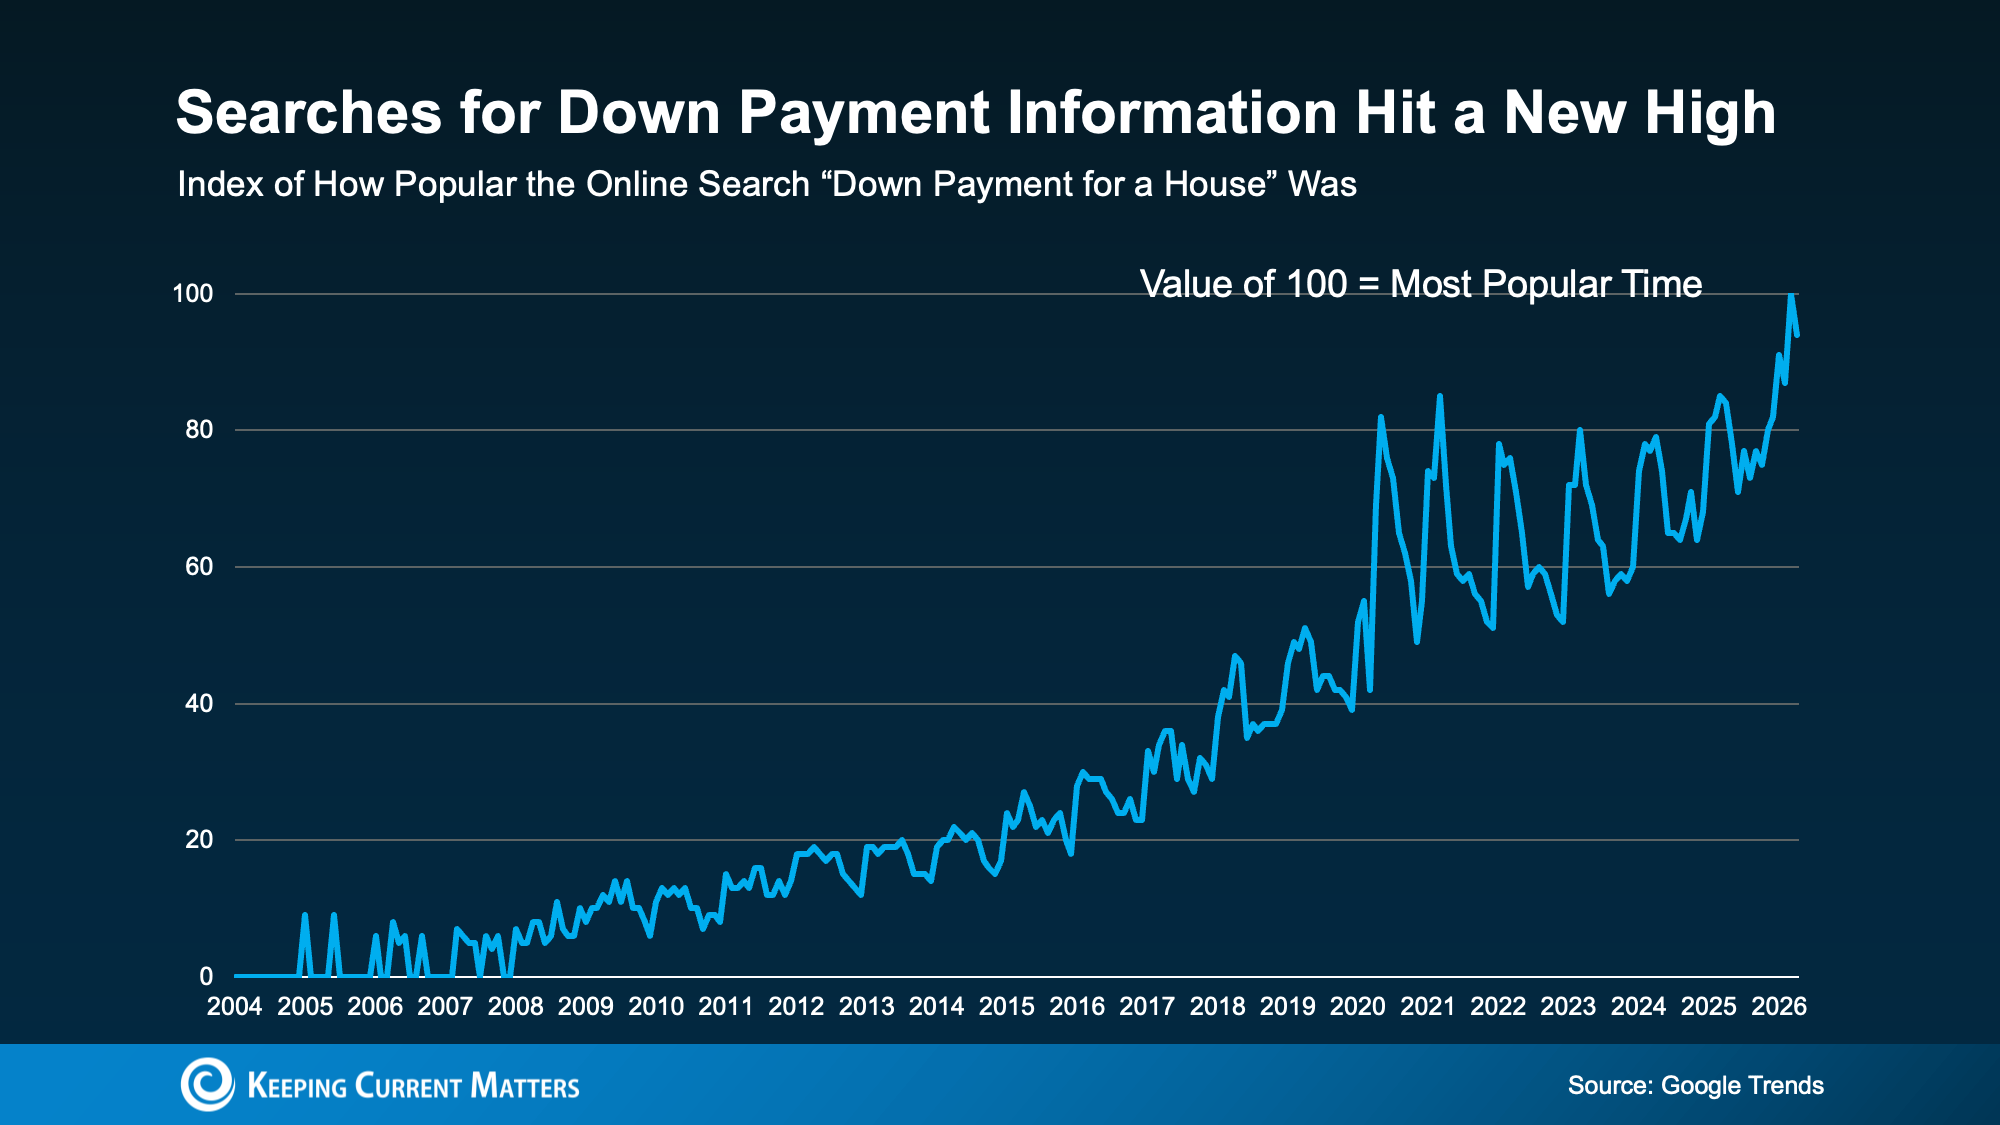
If you’ve been waiting to buy a home because you think you need a 20% down payment, you’re not alone. According to Google Trends, searches for house down payment information recently reached a new high, which shows just how many buyers are trying to understand what it really takes to get started.
The good news is that 20% down can be helpful, but it usually isn’t required. For many first-time homebuyers, the path to homeownership starts with a smaller down payment, the right loan program, and possibly even down payment assistance.
The 20% Down Payment Homebuying Myth
The idea that you must put 20% down to buy a home is one of the most common misconceptions in real estate. It’s easy to see why the myth sticks. A larger down payment can lower your monthly mortgage payment, reduce the amount you finance, and in some cases help you avoid private mortgage insurance.
But that doesn’t mean 20% is the minimum needed to buy a home.
Unless your lender specifically requires it, you may have options that call for far less money upfront. As The Mortgage Reports explains:
“The amount you need to put down will depend on a variety of factors, including the loan type and your financial goals. If you don’t have a large down payment saved up, don’t worry—there are plenty of options available, and you don’t need to put down the traditional 20% . . . many homebuyers are able to secure a home with as little as 3% or even no down payment at all . . .”
For instance, FHA loans allow down payments as low as 3.5%. VA loans and USDA loans may offer zero down payment options for qualified buyers, including eligible Veterans and buyers purchasing in qualifying areas.
Saving for 20% can take longer than many buyers expect. If you’re delaying your plans only because you believe 20% down is a hard requirement, you may be waiting extra long to buy.
What First-Time Homebuyers Are Actually Putting Down
But if most first-time buyers aren’t putting down 20%, what are they putting down?
According to the National Association of Realtors (NAR), the median down payment for first-time homebuyers is 10%. That’s half of the 20% many people assume they need.
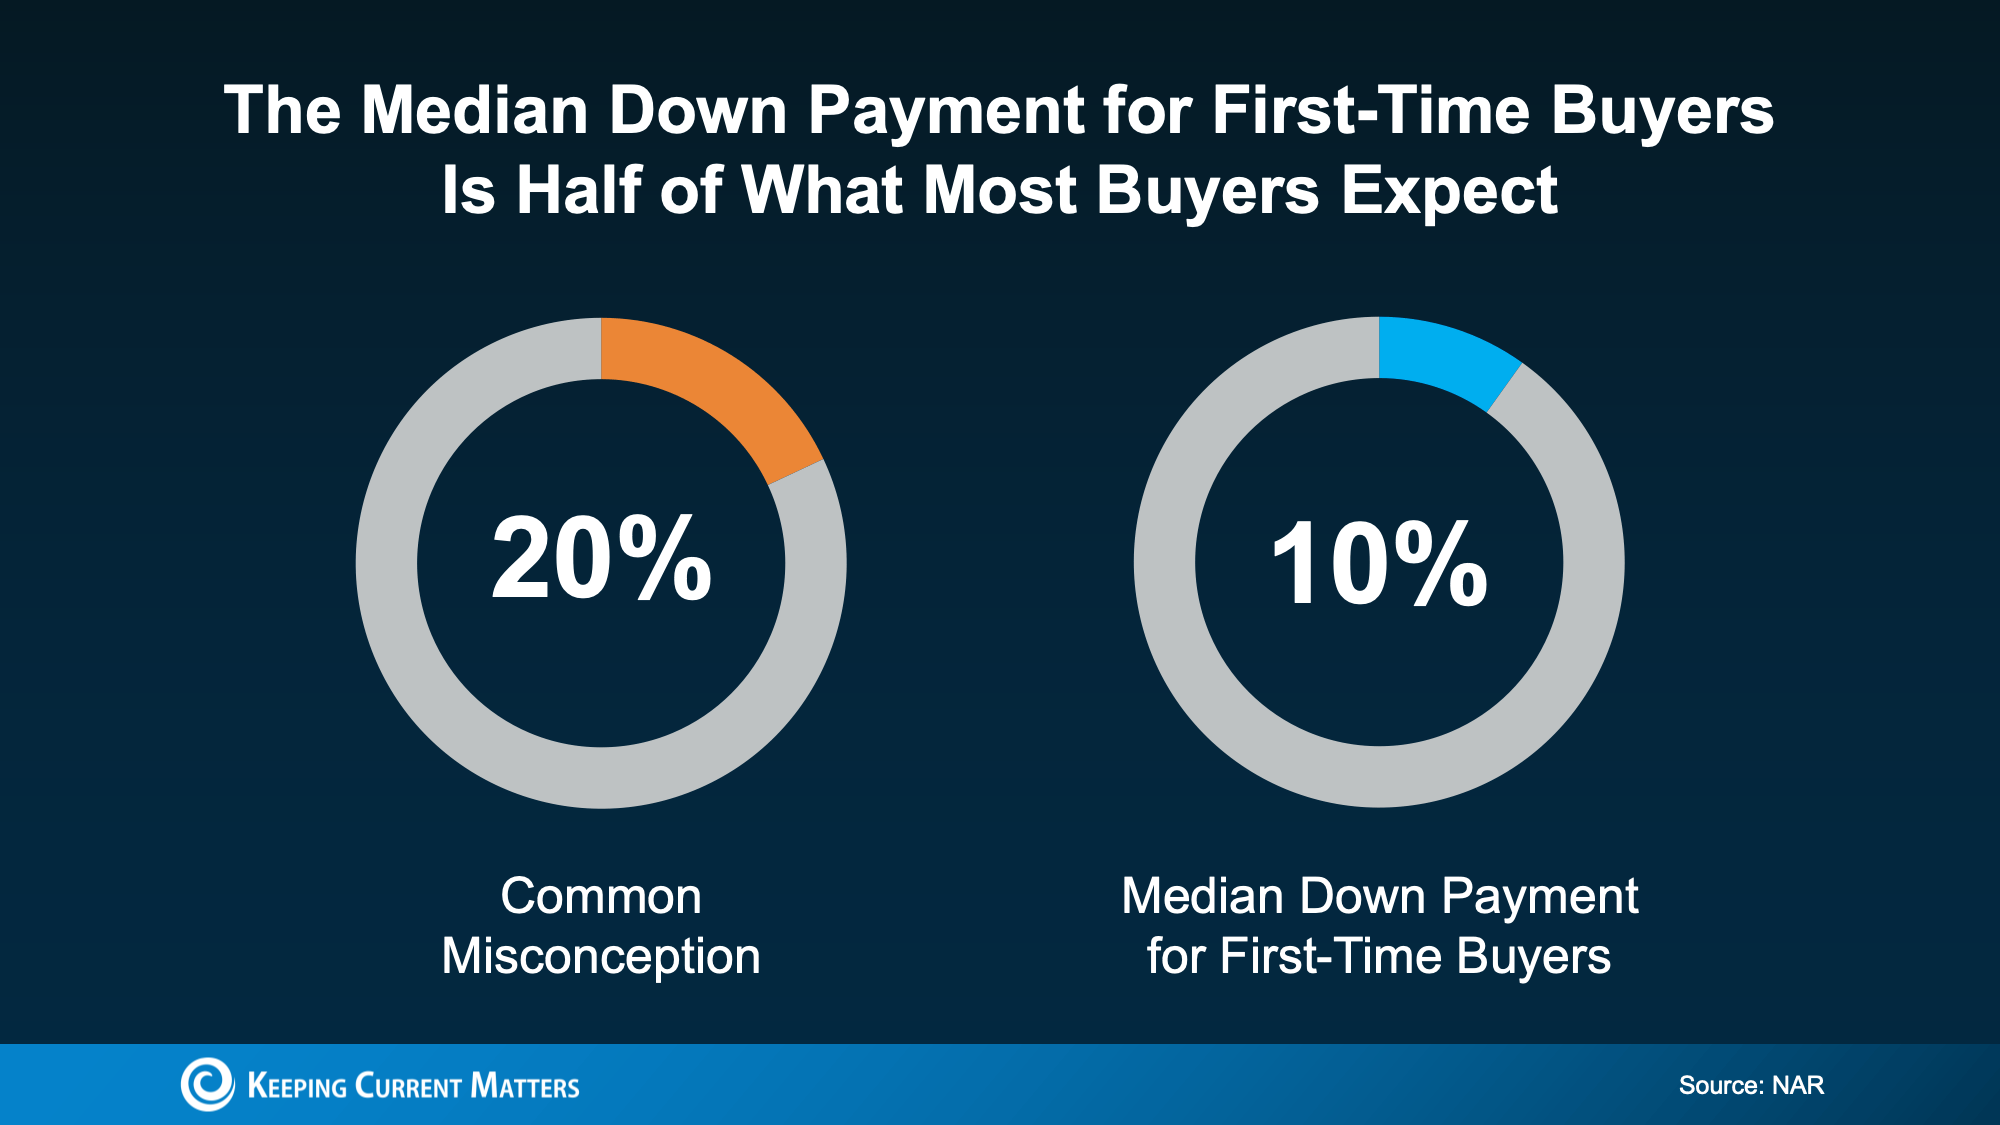
This doesn’t mean 10% is the right amount for every buyer. Your ideal down payment depends on your credit, income, loan type, home price, monthly payment goals, and how much cash you want to keep available after closing.
But it does show that first-time buyers are finding ways to purchase without waiting until they have 20% saved. And for some buyers, the number may be even lower depending on the loan program they use.
Down Payment Assistance Could Help You Buy Sooner
There’s another reason the 20% myth can hold buyers back: many people don’t realize how much help may be available.
Down payment assistance programs are designed to help qualified buyers cover part of their upfront costs. These programs may come in the form of grants, forgivable loans, low- or no-interest second loans, tax credits, or other forms of support. Eligibility can vary based on income, location, property type, profession, or whether you complete a homebuyer education course.
Research from Realtor.com found almost 80% of first-time homebuyers qualify for down payment assistance (DPA), but only 13% take advantage.
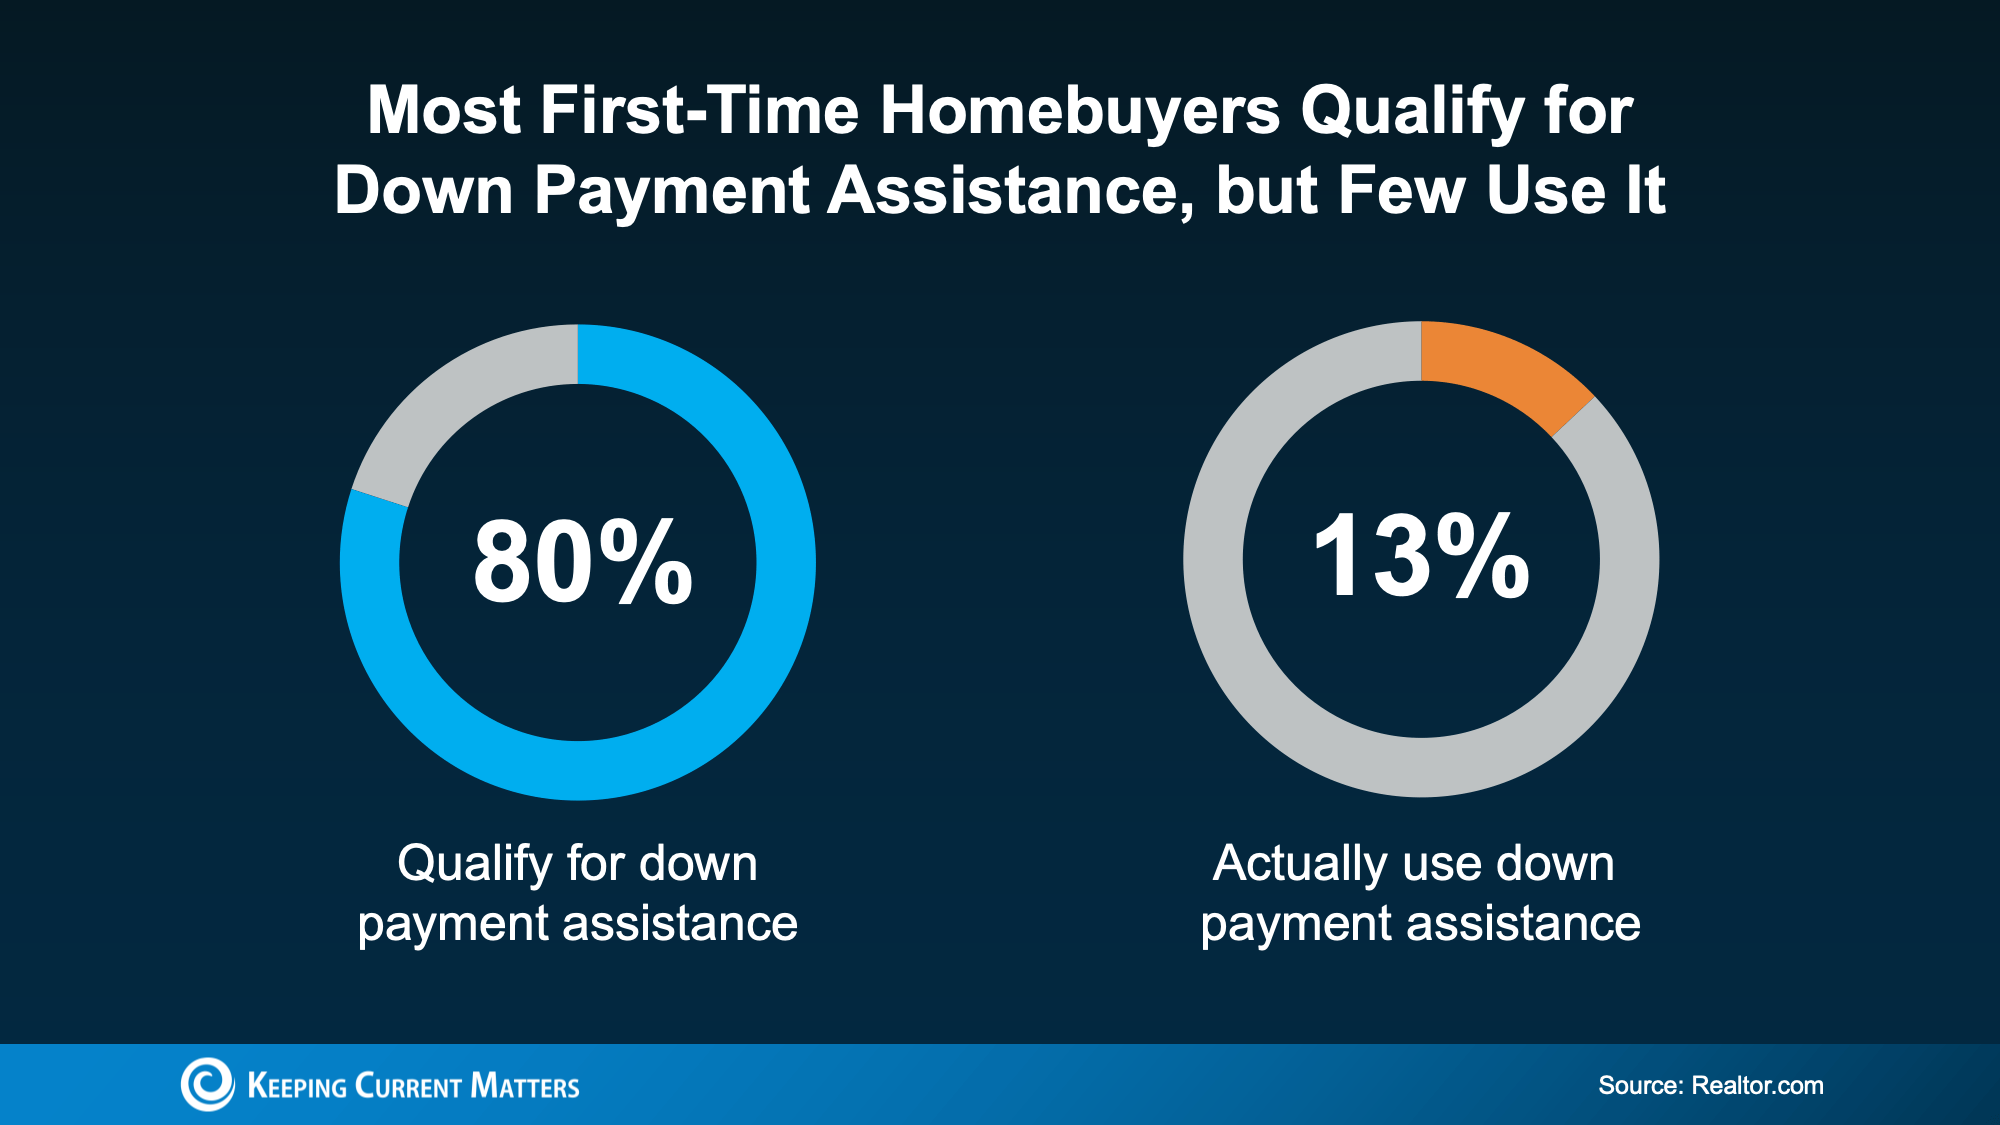
That gap is important. It means many would-be buyers may be leaving valuable assistance on the table simply because they don’t know what programs exist or how to apply.
In the U.S., there are more than 2,600 homeownership programs available, and many provide meaningful financial support. As Down Payment Resource explains:
“With an average benefit of $18,000, down payment assistance (DPA) remains one of the most essential tools for addressing the nation’s affordability challenges. Programs continue to expand in scope, serving a broader range of incomes, property types and borrower needs, including first-generation, military and repeat buyers.”
For some buyers, that kind of assistance could make a major difference. It may help cover part of the down payment, reduce closing costs, or make it easier to keep emergency savings intact after the purchase. In some cases, buyers may even be able to combine multiple programs for additional support.
The Bottom Line: Explore Your Options
Most first-time homebuyers do not put 20% down, and you may not need to either. While saving is important, the real question is whether you know which loan programs and assistance options fit your situation.
Before you rule out buying, connect with a trusted lender and a knowledgeable real estate professional. They can help you understand what you really need to save, what programs you may qualify for, and whether homeownership could be closer than you think.
3 Things That Aren’t Going To Happen in Today’s Housing Market
There’s no shortage of uncertainty in today’s housing market, and that’s naturally fueling a lot of dramatic headlines. And if you’re trying to buy a home, that kind of noise can make your decision feel a lot more complicated.
In fact, a recent CNBC study asked homebuyers what they’re most concerned about, and the same three topics kept rising to the top:
- Mortgage rates
- The number of homes for sale
- Home prices
The challenge is that much of what people are hearing about these topics is driven by misconceptions, not facts. Let’s separate the headlines from what the data is really showing.
Misconception #1: “I Should Wait Because Mortgage Rates Are Going To Fall Dramatically”
One of the most common ideas circulating on social media is that mortgage rates are about to drop sharply, so waiting to buy is the smarter move.
But is that what experts are expecting?
While mortgage rates have eased a little in recent weeks, forecasts still aren’t predicting any major declines. It’s more likely that rates will stay in the low 6% range this year.
And that’s not a remarkable shift from the rates we’re seeing today:
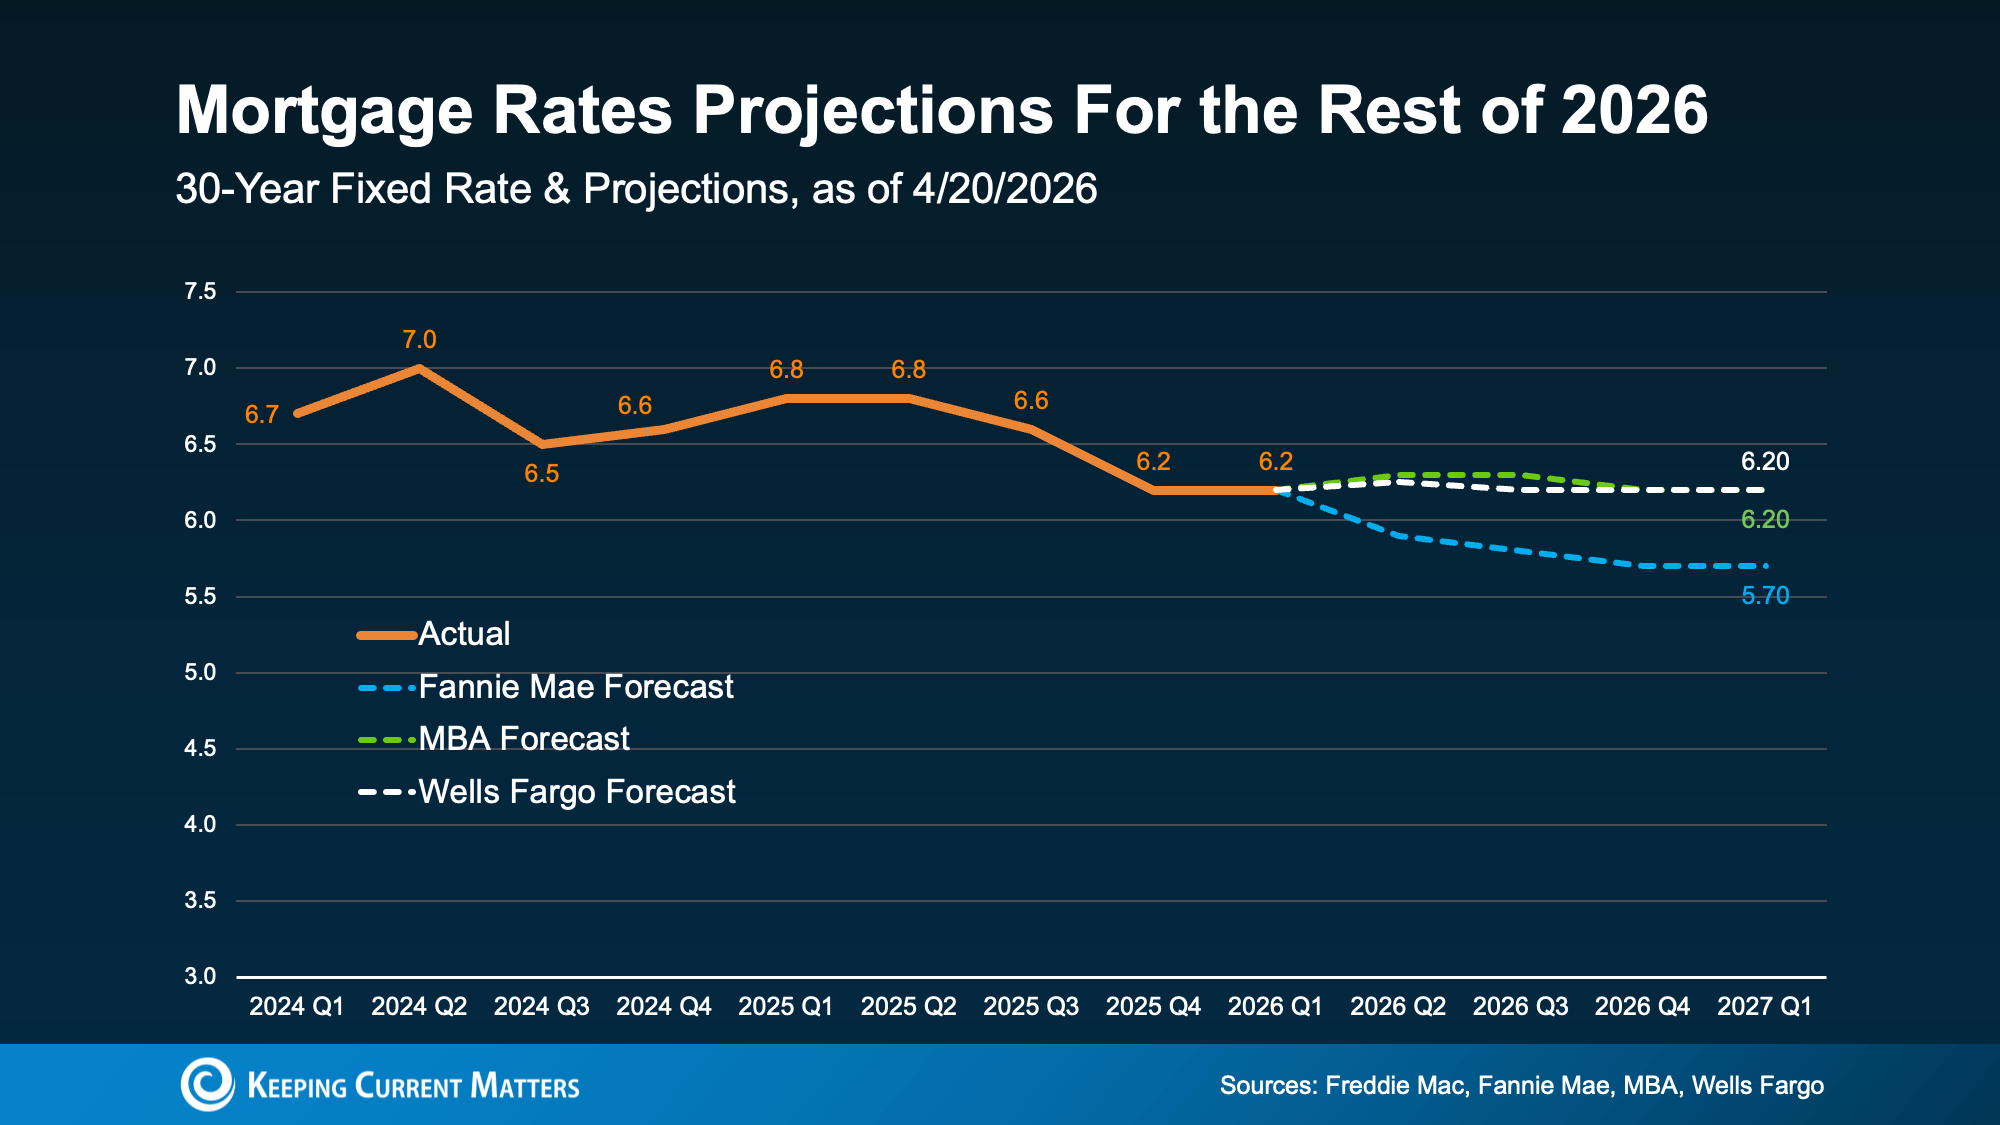
Obviously, a lot depends on inflation and the broader economy. But based on what we know right now, waiting for a big drop in mortgage rates may not play out the way many buyers hope. As U.S. News explains:
“Mortgage rates aren’t expected to change much over the next several quarters . . .”
And even with rates where they are today, buying a home is already more affordable than it was a year ago. Even if rates don’t drop in the near future, home affordability is better now than a year ago.
Misconception #2: “There Are Too Many Homes for Sale”
You may have heard that housing inventory is rising. Nationally, that’s true: the number of homes for sale is 8% higher than it was at this time last year. But that’s not bad news. In lots of markets, it’s easing the pressure on buyers.
The problem is that some headlines make good news sound like bad news. They focus on the fact that inventory is at its highest level since 2019 or highlight how many new homes builders are adding. That can make it sound like supply is growing too much, too fast.
But the bigger picture tells a different story.
According to new Realtor.com data, even though inventory is up over last year, it’s still nearly 14% lower than it was in the last normal housing market from 2017 to 2019:
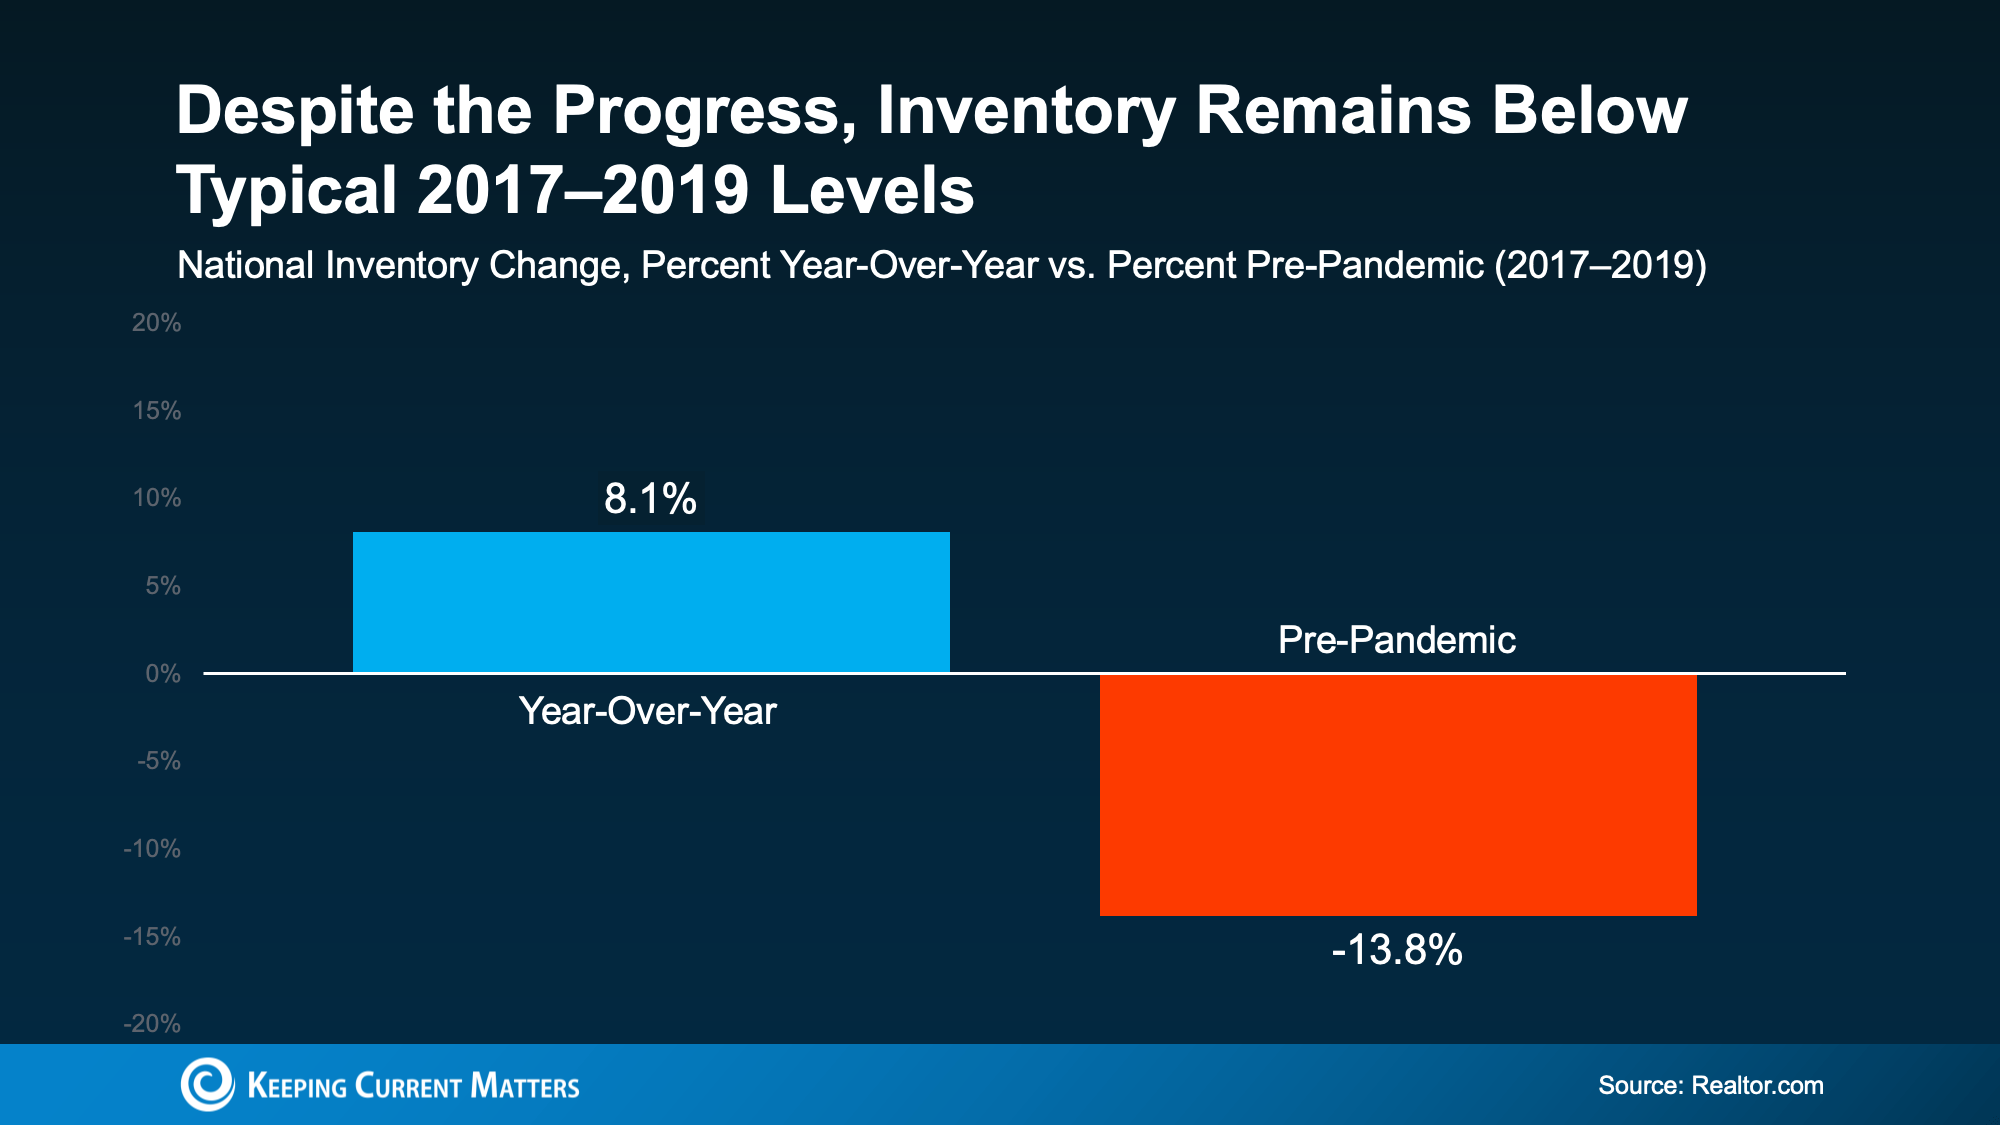
And while local conditions vary, only 9 states have more inventory now than they did before the pandemic. That’s a major reason there aren’t enough homes for sale to trigger anything like the 2008 housing crash.
Misconception #3: “Home Prices Are About To Crash”
This is another common headline you’ve probably seen. This misconception comes from the fact that a few metros are actually seeing small price declines. Influencers are pointing to this to claim home prices are crashing. But this is absolutely not true nationally.
In most markets, home prices are still rising, not falling. Here’s why:
- Many homeowners are choosing not to sell to avoid giving up the low mortgage rate they locked in a few years ago. That continues to limit how much inventory can grow.
- Inventory remains below pre-pandemic norms. There still aren’t enough homes for sale to cause a widespread price crash.
- Even in markets with more listings, some sellers are pulling their homes off the market instead of making major price cuts.
Those are three big reasons home prices are not on track for a crash.
And even in the areas seeing small price declines, those drops are nowhere near enough to erase the huge gains most homeowners have built over the past five years:
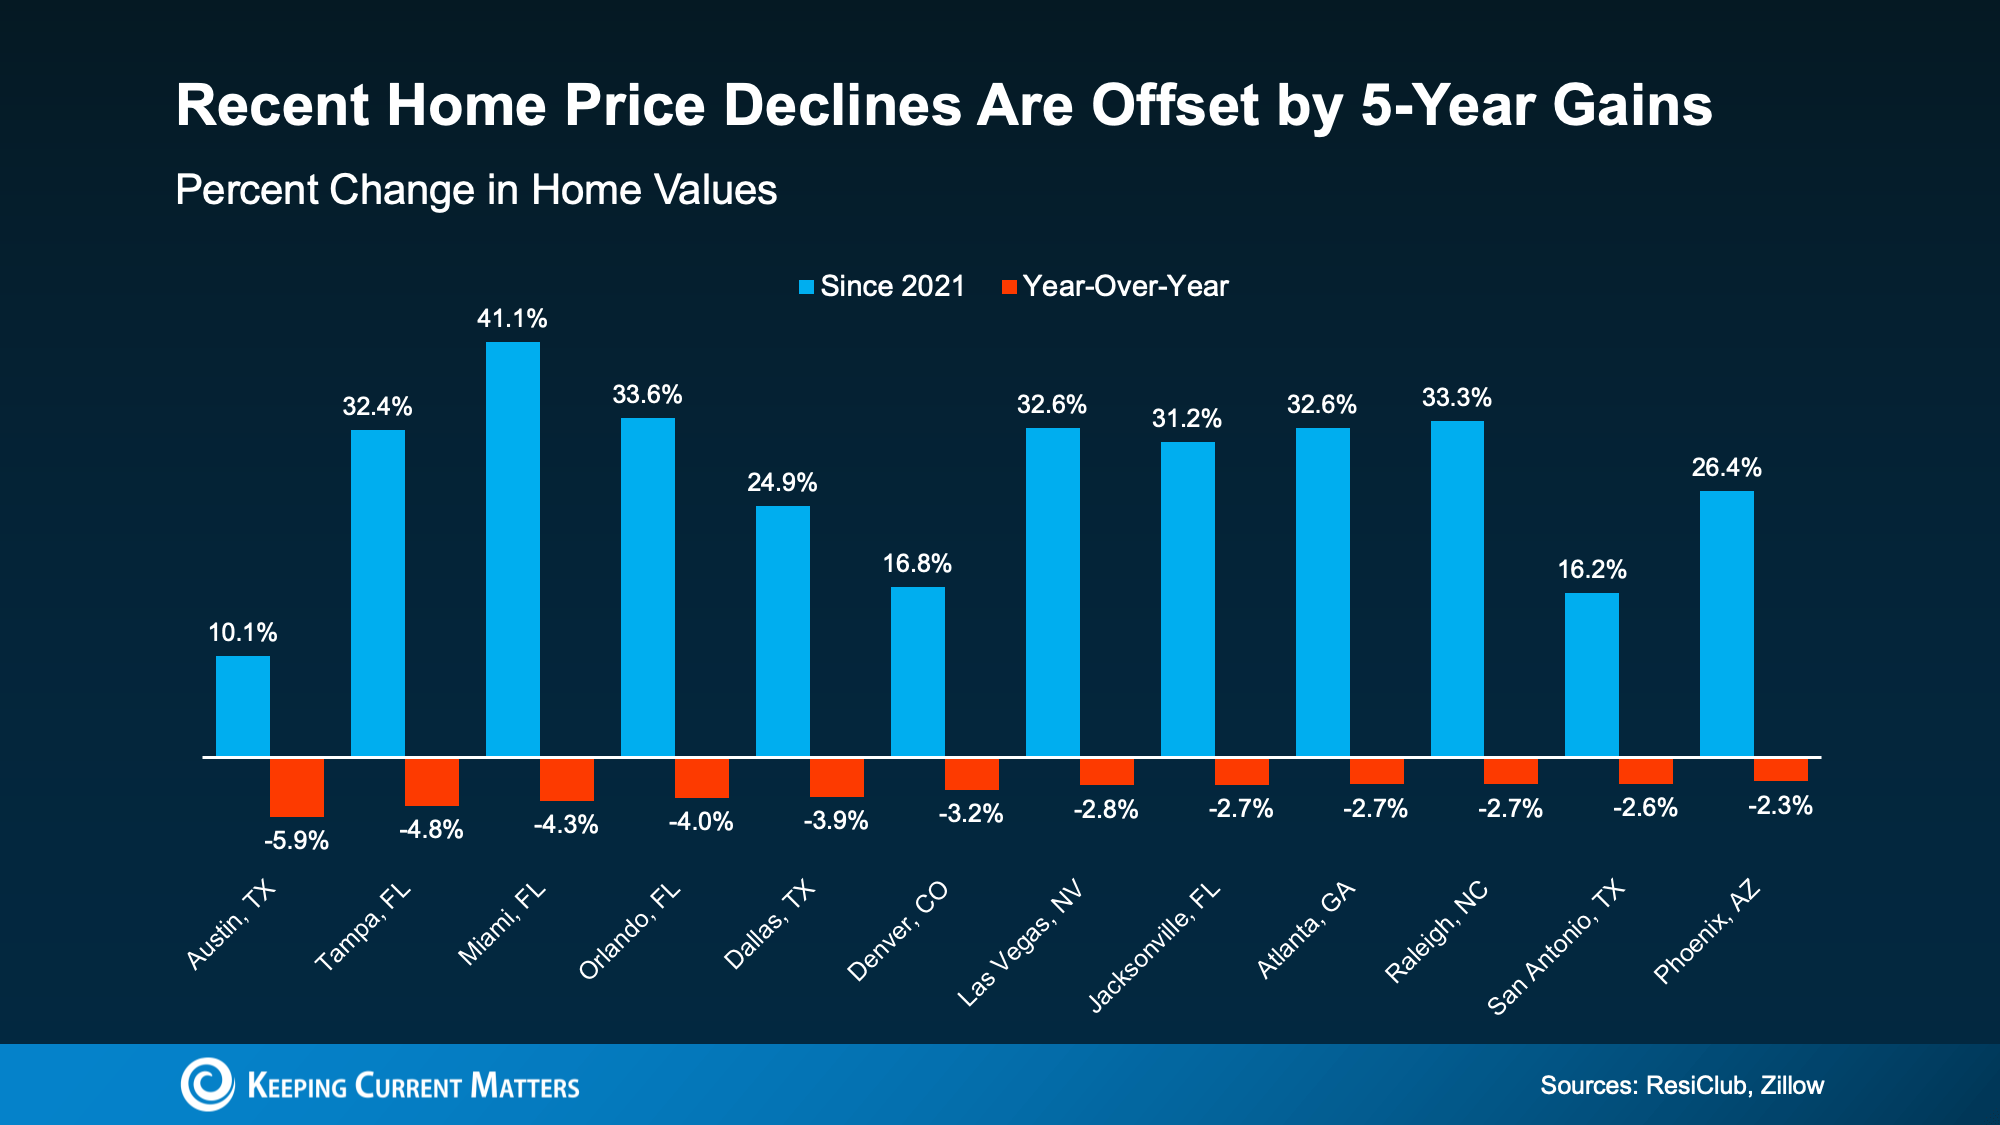
These drops don’t signal a crash. They show the market settling after a few years of record-breaking spikes in prices.
Bottom Line: Get the Facts on Your Market
The discussions we see online can often exaggerate the negative and ignore the positive, especially in housing. If you want a clearer, truer idea of what’s happening with mortgage rates, housing inventory, and home prices in your market, talk to a trusted real estate professional.
Connect with a local real estate agent so you have an expert who can give you the real story on your local housing market.
Should You Still Buy a Home Right Now? What Buyers Need To Know
Between nonstop economic headlines, global uncertainty, and ongoing concerns about affordability, it’s understandable to wonder whether now is still a smart time to buy a home.
The good news is this: current events may be influencing the housing market, but they have not taken homeownership off the table. For many buyers, the opportunity is still there. It just may require a more thoughtful strategy than it did a few months ago.
Mortgage Rates Have Risen Slightly. Here’s What’s Behind It
After trending downward for much of 2025, mortgage rates have climbed again over the past month. Experts point to a mix of global events and broader economic pressures as key reasons why.
As Mark Fleming, Chief Economist at First American explains:
“Mortgage rates have recently moved higher, driven by geopolitical uncertainty and rising energy costs that are contributing to inflation concerns.”
So what does that mean if you’re thinking about buying a home? Should you wait for conditions to settle before making a move?
Not necessarily.
Your Opportunity To Buy Hasn’t Disappeared
There’s no denying that buying felt a bit more affordable when mortgage rates were closer to 6%. Now that rates are hovering in the mid-6% range, monthly payments are naturally a little higher.
But it helps to take a step back and look at the bigger picture.
For example, if you’re financing a $500,000 home, a rate in the mid-6s could still mean a monthly payment that is roughly $300 lower than what buyers were facing early last year.
That means today’s higher rates have not erased all the progress we’ve seen. In fact, buying a home can still be more affordable than it was just a year ago.

Yes, your payment may have been lower a few weeks ago. But trying to perfectly time the market rarely works in your favor. Conditions can shift quickly, and hindsight always makes past decisions look easier.
Instead of waiting for the “perfect” moment, focus on making the best decision based on your goals, finances, and today’s market conditions.
Expect Mortgage Rate Volatility
One thing buyers should be prepared for is continued movement in mortgage rates.
Rates may keep rising or falling in the weeks and months ahead as new economic reports are released and world events continue to unfold. That kind of uncertainty can feel frustrating, but it’s also part of today’s market.
The truth is, you can’t control what happens with inflation, global events, or mortgage rates next week. What you can control is how prepared you are when the right opportunity comes along.
That preparation can make all the difference.
If You Need To Move, You Still Have Options
For many buyers, the decision to move is not just about market timing. Life keeps moving, even when the market feels unpredictable.
Maybe your family is growing. Maybe you’re relocating for work. Maybe your current home no longer fits your lifestyle or needs. Those reasons still matter, and they may be more important than waiting for rates to change.
Buyers who are moving forward right now are often doing so because their personal situation makes it the right time.
And the good news is there are still strategies that can help make a purchase more manageable.
For example, some buyers are exploring adjustable-rate mortgages (ARMs) to secure a lower initial rate. That approach is not right for everyone, but it’s one example of how flexibility and planning can create opportunities in today’s market.
A Smart Plan Starts With the Right Experts
In a market like this, having a plan matters more than ever.
Working with a trusted real estate agent and lender can help you:
- Understand what you can realistically afford at today’s rates
- Review financing options, including ARMs and buyer assistance programs
- Stay informed as market conditions shift
- Make confident decisions based on your goals, not just the headlines
The right professionals can help you look beyond the noise and focus on what makes sense for your specific situation.
Conclusion
Uncertainty in the market does not mean you’re out of options.
If you need or want to move, buying a home may still be the right decision. The key is to go in with a solid plan, the right support, and a clear understanding of your financing options.
Homeownership is still possible. You just need the right strategy for today’s market.
The Best Time To List Your House Is Almost Here
Spring is usually one of the strongest seasons to sell a home, but according to research from Realtor.com, one specific week tends to stand out year after year. And it’s almost here.
Based on historical housing market trends, the best week to list your house this year is April 12–18.
Here’s why that window can be especially favorable for sellers.
Buyers Are More Active
Realtor.com reports that homes listed during this week typically receive 16.7% more views than the average week. In a market where buyers have more choices, extra visibility can make a real difference.
More attention early on can help generate stronger interest, more showings, and a better overall start to your sale.
Homes Sell Faster
More buyer activity can also lead to a quicker sale. Realtor.com found that homes listed during this week spend 17% less time on the market than usual.
That matters, especially in a market where some homes are taking longer to sell than they did a year ago. A faster sale can mean less stress, fewer disruptions, and more momentum from the start.
Sellers May Get a Better Price
As inventory grows, buyers often feel more comfortable asking for repairs, concessions, or price reductions. But during this early spring window, Realtor.com says about 18.9% fewer homes need a price cut.
That gives sellers a stronger chance of listing confidently and holding closer to their asking price.
More Money in Your Pocket
According to the same study, a well-prepared home listed during this week can sell for about $5,300 more than the average week and about $26,000 more than homes listed at the beginning of the year.
For sellers, that’s a meaningful difference.
More views, less time on the market, and a better shot at top dollar all make this one of the most appealing times to list.
What You Should Do Now To Prepare
If you’re thinking about selling and want to take advantage of this timing, the next step is simple: connect with a local real estate agent.
A trusted local agent can help you decide how to prepare based on what is happening in your market. Real estate trends can vary by city, neighborhood, and even price point, so local insight matters.
Your agent can help you figure out:
- What updates are worth making before you list
- Which repairs should come first
- What buyers in your area care about most
- Which small improvements can have the biggest impact
For some sellers, getting ready may only take a couple of weekends. Fresh paint, basic landscaping, or a deep clean can go a long way.
For others, taking a few extra weeks to make light updates may be the smarter move. And that’s completely fine. While mid-April may offer an advantage, it is not the only good time to sell.
Spring Still Offers a Strong Opportunity
Zillow says May is also one of the best times to list a home. That means sellers still have a strong window of opportunity throughout the spring season.
So while April 12–18 may be a standout week, it’s not your only shot at a successful sale.
Conclusion
Listing your house in mid-April could help you attract more buyers, sell faster, and maximize your sale price. But the bigger opportunity is the spring market as a whole.
The real question is: what do you need to do now to get your home ready to list?
For anyone planning a spring move, now is the time to start preparing. The sooner you connect with a local agent, the sooner you can make a plan that fits your goals and your timeline.
Home Affordability Improved in All 50 States: What Buyers Need To Know
For the past few years, affordability has been one of the biggest reasons buyers have put their home search on hold. Maybe you did the same.
At some point, you may have looked at the numbers, saw what a monthly mortgage payment would be, and decided to wait for the market to become more manageable. But there’s encouraging news you may have missed.
Over the past year, housing affordability has improved in all 50 states. Yes, every single one.
That’s according to new research from First American. And while buying a home is still more expensive than what’s historically normal, the affordability pressure many buyers have felt over the last several years is finally starting to ease.
Some Markets Are Seeing Bigger Improvements
One of the most important things to understand is this isn’t limited to one part of the country or just a few select markets. Affordability is improving almost all over the country.
Of course, real estate is always local. Conditions can vary a lot from one state, city, or neighborhood to the next. But overall, the market is becoming more favorable for buyers. In fact, affordability has improved in 48 of the top 50 metros over the past year.
That same research also highlights the top 10 cities seeing the biggest gains in affordability:
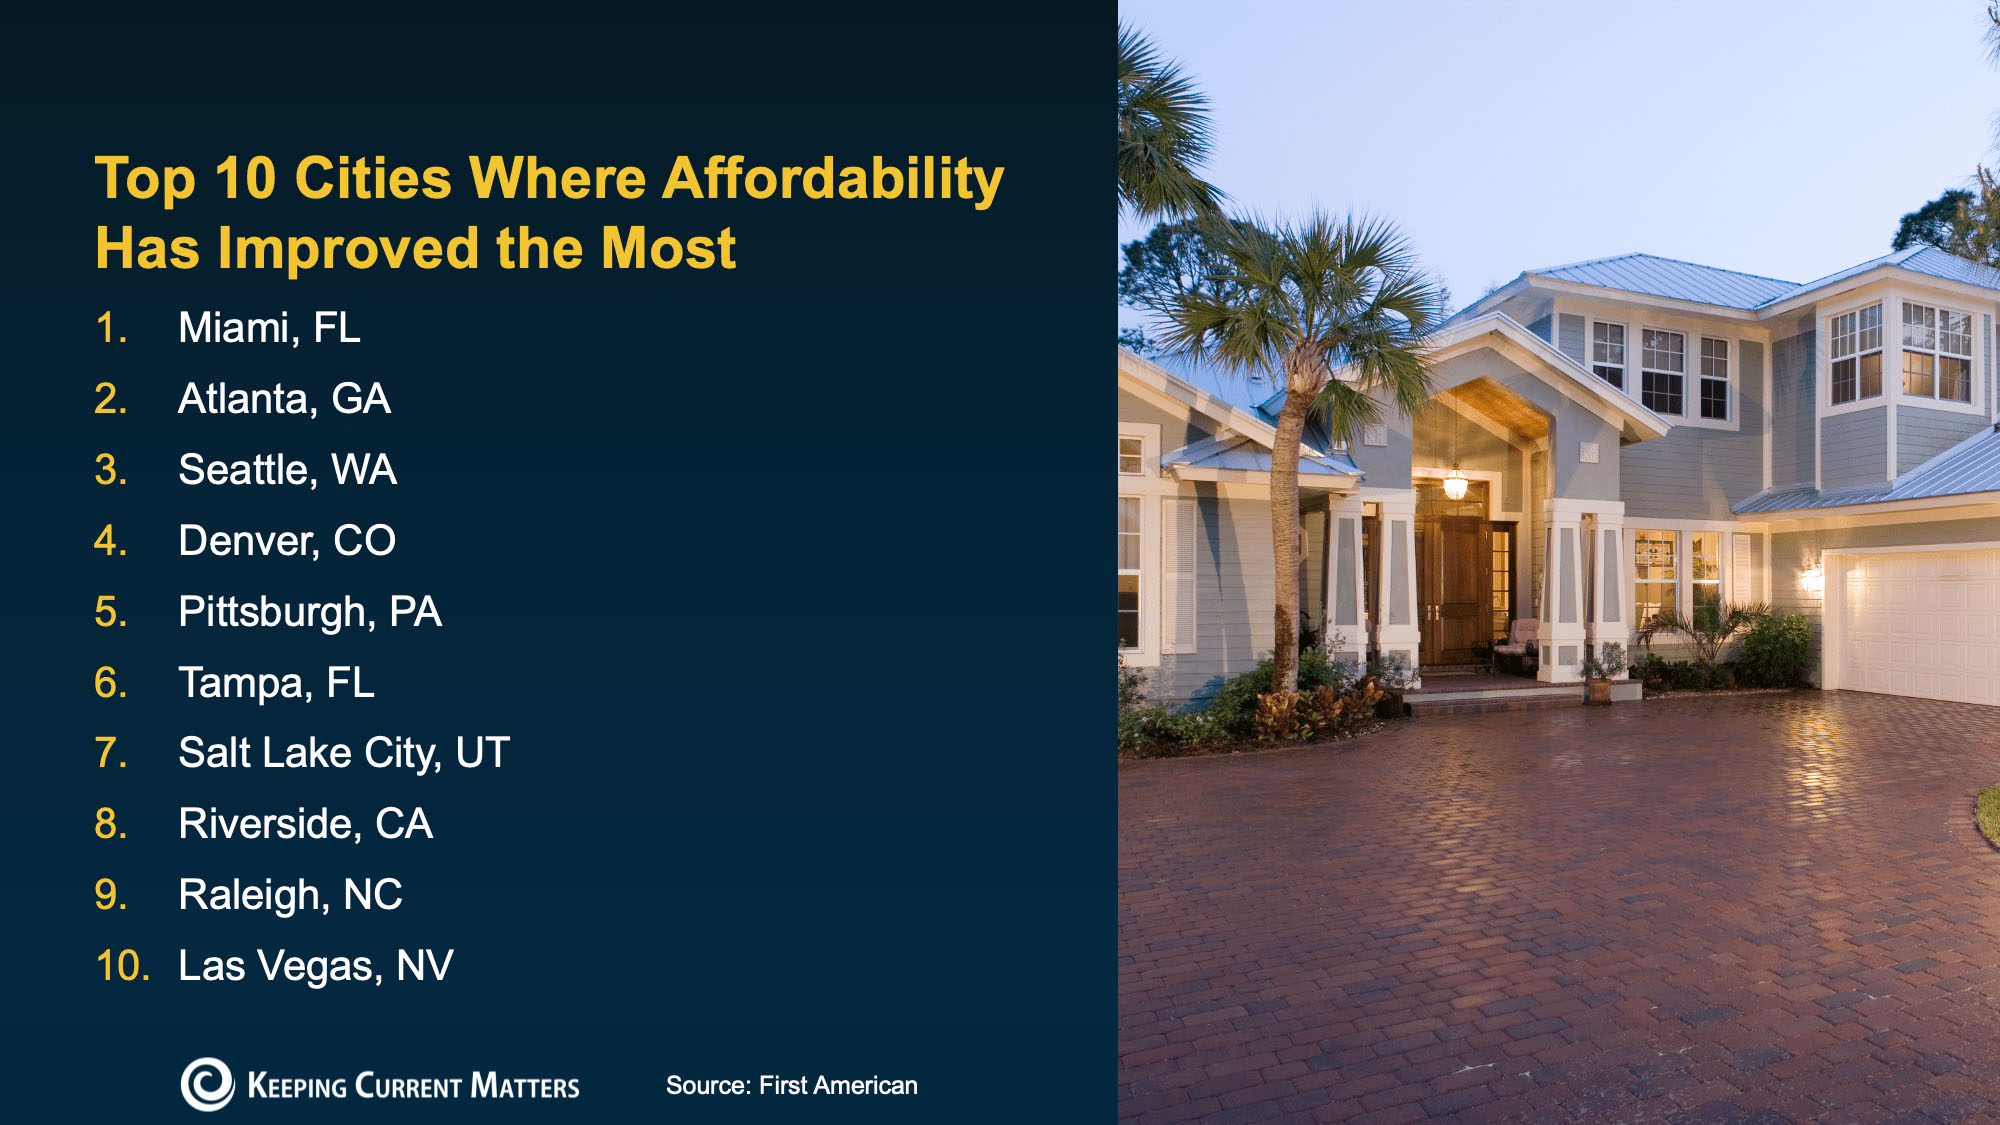
Top 10 Cities Where Home Affordability Has Improved the Most
- Miami, FL
- Atlanta, GA
- Seattle, WA
- Denver, CO
- Pittsburgh, PA
- Tampa, FL
- Salt Lake City, UT
- Riverside, CA
- Raleigh, NC
- Las Vegas, NV
If you’re wondering why some markets are improving faster than others, a lot of it comes down to home inventory.
When there are more homes for sale, the market becomes more balanced. This can help improve affordability by giving buyers more negotiating power. With more options available, buyers may have a better chance of finding a home that fits their budget, and they may also be in a stronger position to ask for seller concessions, price reductions, or closing cost assistance.
That can make a bigger difference than many people expect.
What Does This Mean for Buyers?
Home affordability challenges haven’t disappeared altogether, obviously. Buying a home is still a major financial decision, and housing prices remain high in many markets. But the overall nationwide trend is moving in a direction that gives buyers more opportunity than they’ve had in recent years.
As Chen Zhao, Head of Economic Research at Redfin, explains:
“The housing affordability crisis is showing signs of easing. . . opening the door for more Americans to make the jump to homeownership.”
Conclusion
If you’ve been waiting on the sidelines for affordability to improve, this may be the sign you’ve been hoping for. To find out what’s happening in your local market and how much buying power you may have today, connect with a trusted local real estate agent.
Are Home Prices Dropping? What the Latest Data Show
You’ve probably seen headlines or social posts claiming that home prices are falling. It’s an attention-grabbing message, and it naturally leads to two big questions:
- Is this the start of a crash?
- What does it mean for my home’s value?
Here’s the reality: a few markets are seeing small, normal pullbacks, but this is not a nationwide crash. In most areas, prices are still rising or holding steady, just not at the breakneck pace we saw a few years ago.
Home Prices Are Still Rising Nationally
A lot of online chatter focuses on isolated price drops without mentioning the broader data. Nationally, prices have continued to trend upward, but at a slower rate than usual.
According to a new report from the National Association of Realtors (NAR):
“Home prices continued to rise in the fourth quarter of 2025. National median prices rose 1.2% year over year to $414,900.”
That’s modest growth compared to the peak “boom” years, but it’s still growth. And regionally, the story varies.
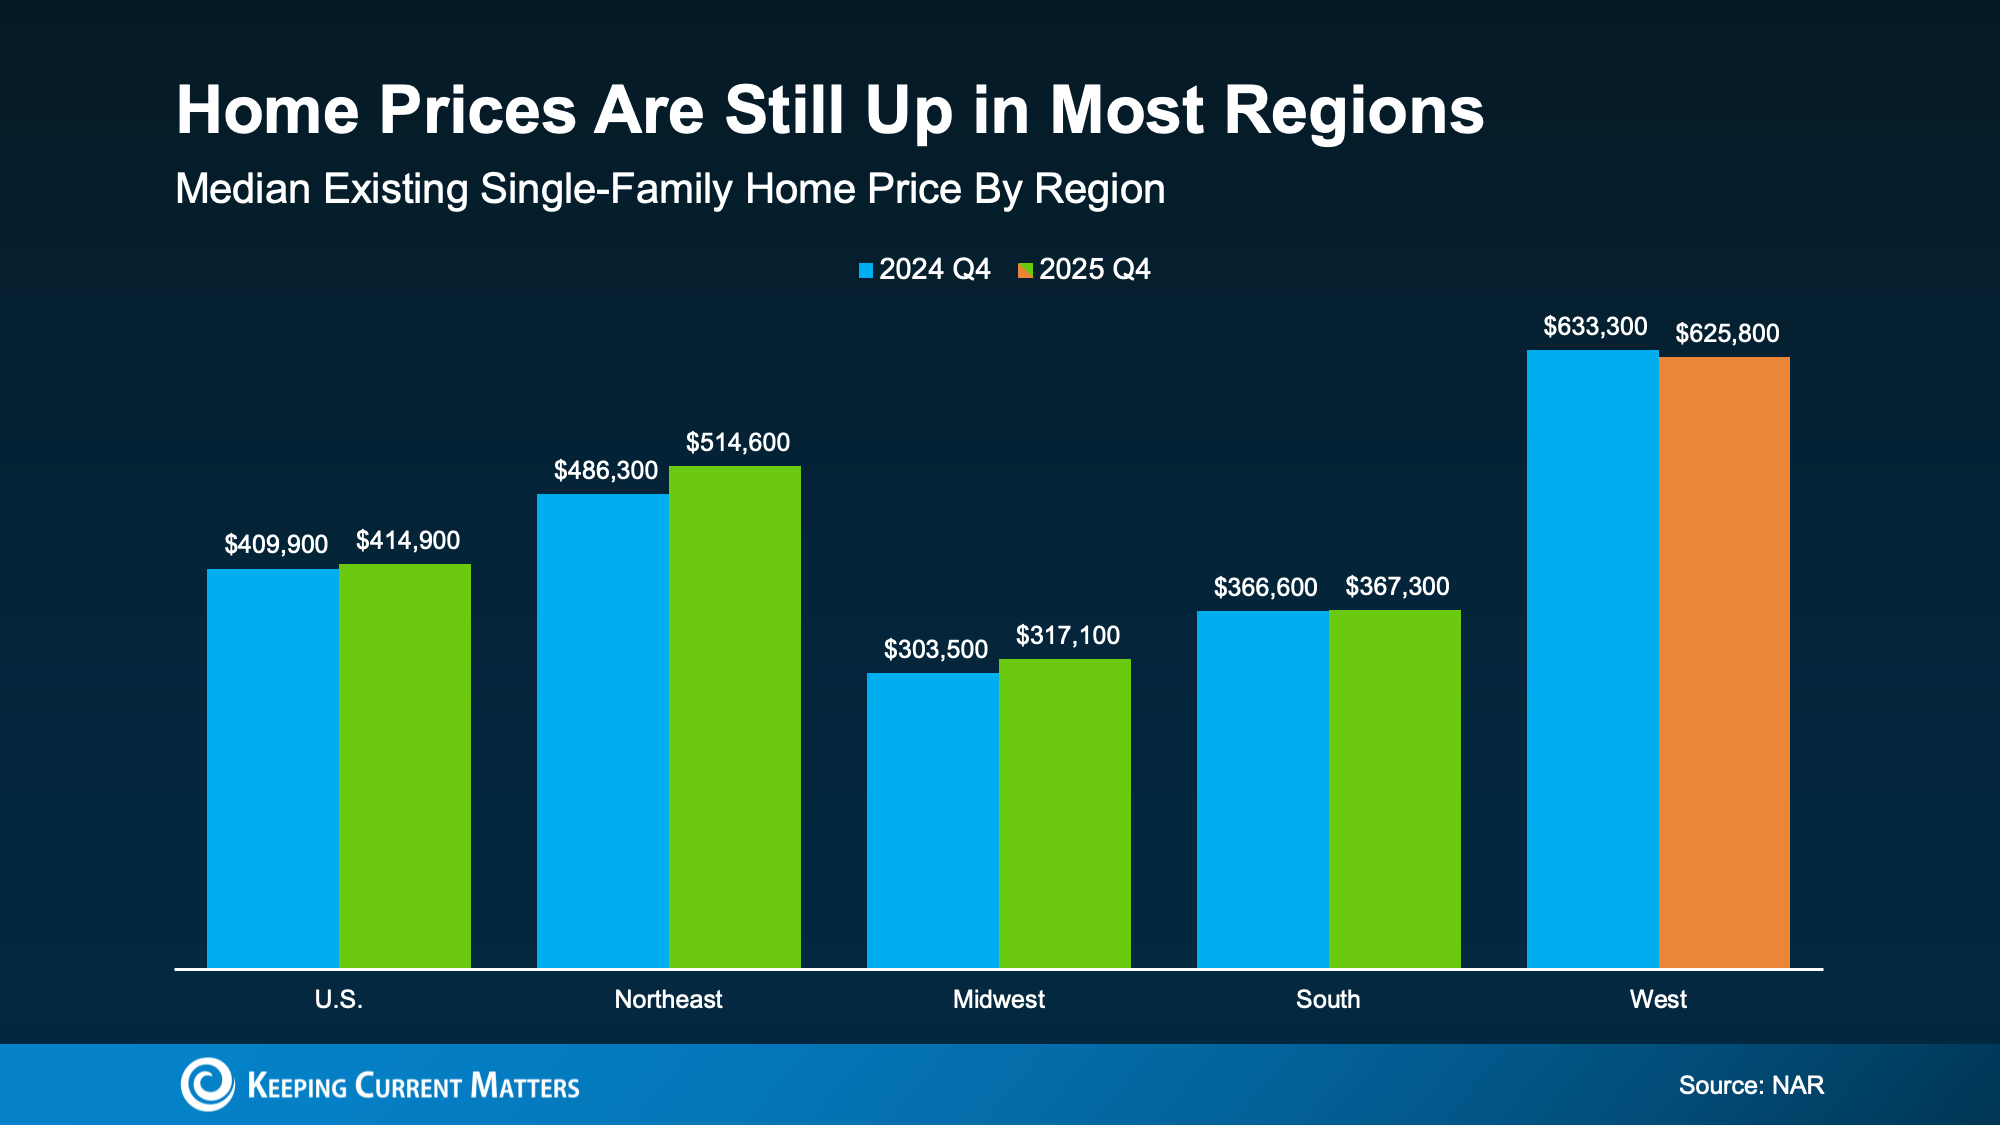
At a glance, the numbers show:
- Northeast, Midwest, and South: prices generally up or steady.
- West: more mixed, with some markets seeing mild price declines.
In other words, the market is cooling and normalizing, not crashing.
Why You’re Hearing So Much About Price Drops
Price declines make for clickable headlines. But a few factors can make a local shift look like a national trend:
- High-profile metros go viral. A dip in one major market can dominate the conversation.
- Seasonality is real. Some months are softer than others, even in healthy markets.
- Affordability has cooled demand. Higher payments can reduce competition and push prices to level off.
Those are signs of a market adjusting, not collapsing.
Some Markets Have Softened, But Context Matters
In the places where prices have dipped, it helps to look at the big picture. Many of those markets saw especially strong appreciation over the last several years. When you compare today’s values to where they were five years ago, homeowners in many “down” markets are still up significantly overall.
According to data from ResiClub and Zillow, price dips in the short-term aren’t always the cause for concern they seem to be. The long-term trends tell a clearer story, and they remain strong for many homeowners.
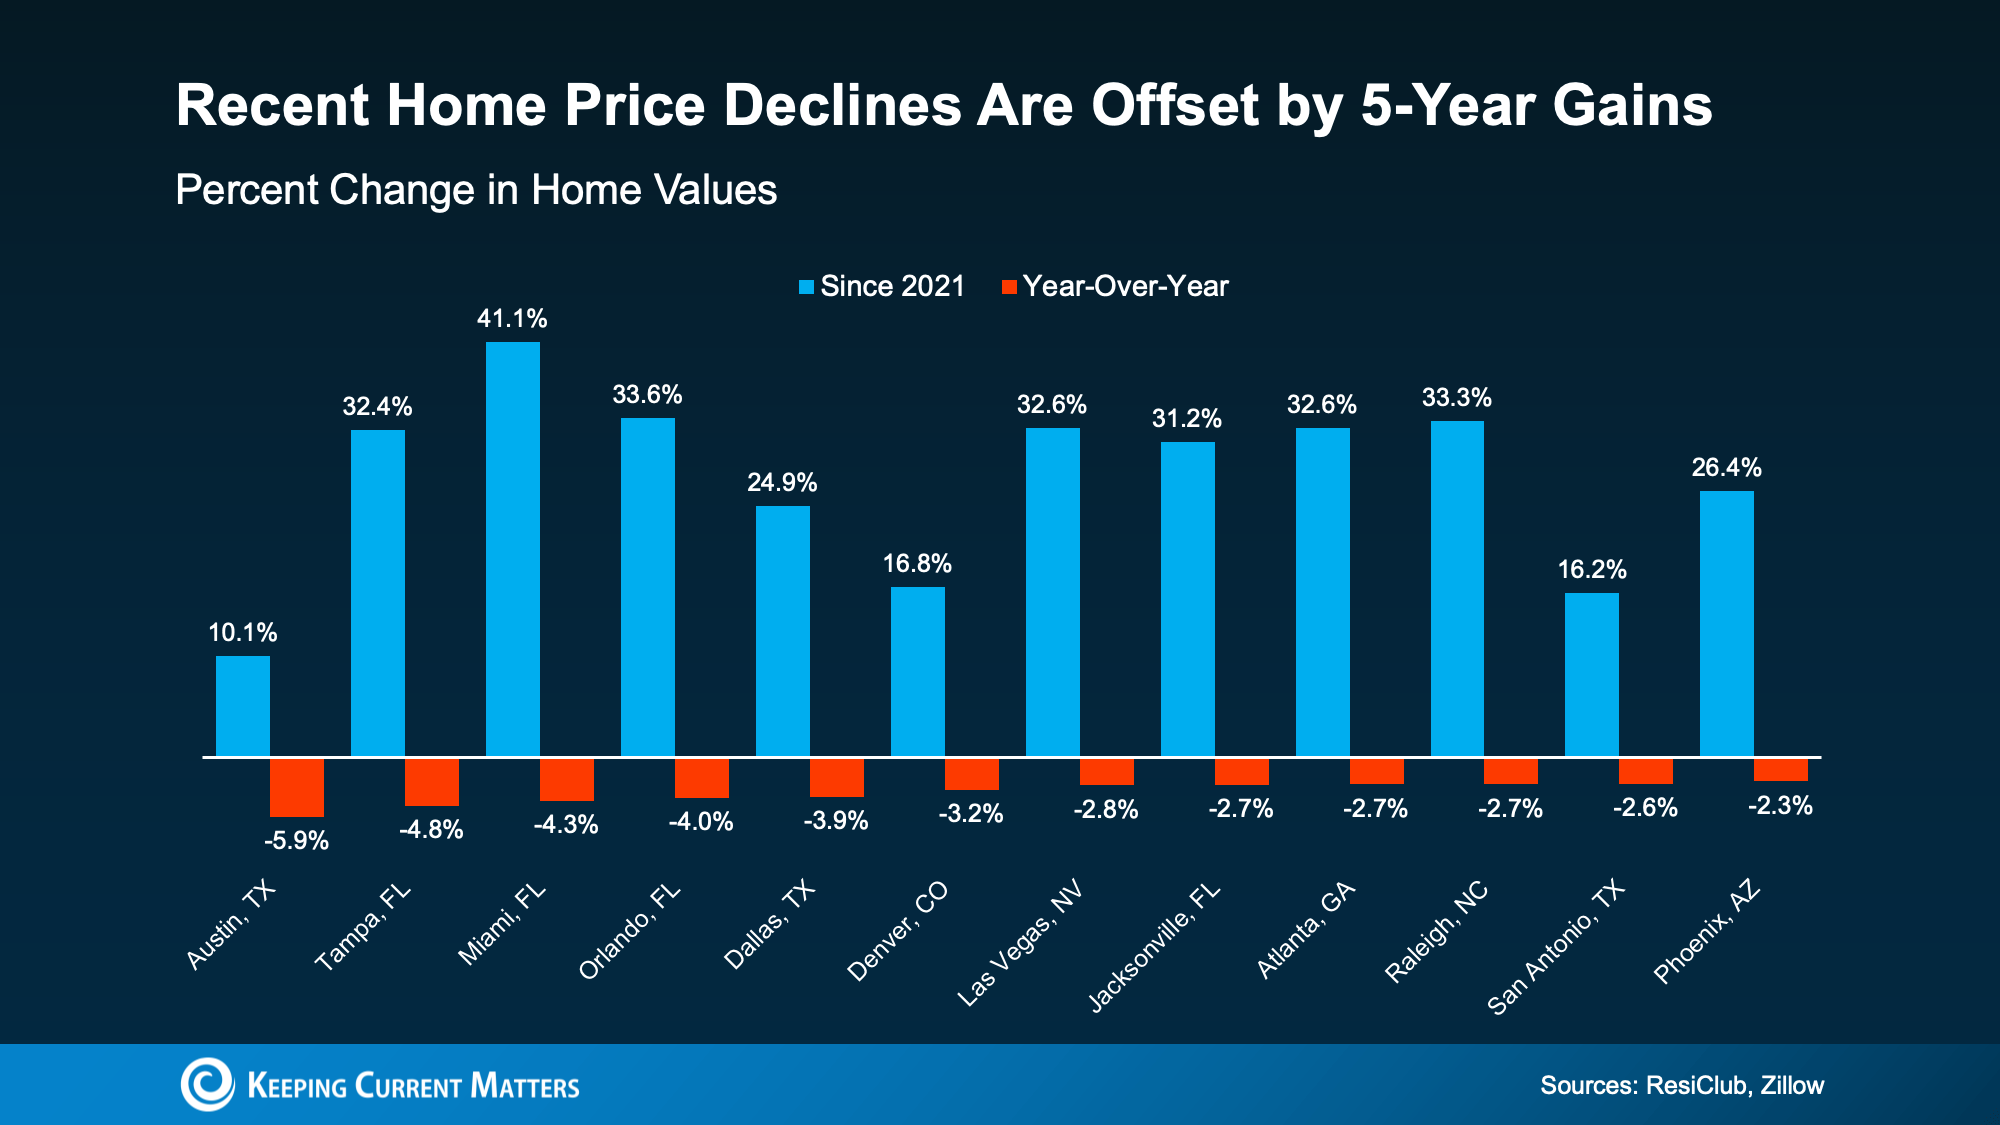
The key point: a pullback after rapid growth is not the same thing as a crash. It’s often a correction toward something more sustainable.
What This Means for Homeowners and Buyers
If you’re a homeowner:
In most markets, you’re not watching value evaporate overnight. Instead:
- You likely still have meaningful equity compared to pre-2020 values.
- Pricing strategy matters more now that buyers aren’t automatically overbidding.
- The best indicator is recent comparable sales in your neighborhood.
If you’re a buyer:
A cooler market can create more breathing room:
- You may see more negotiability in certain areas.
- You may have more time to decide than during the peak frenzy.
- But waiting for a big “crash” could mean missing the right home if your local market is stable.
Real estate is local. The best move depends on your budget, timeline, and the neighborhood you want.
How to Know What’s Happening Where You Live
National headlines can’t tell you what’s happening on your street. To get a clear picture, look at:
- Recent sold prices (comps) for similar homes.
- Days on market and list-to-sale price ratios.
- Inventory levels and new listings.
- Price reductions on comparable listings.
A local real estate agent can help make sense of your market’s unique trends. That way, you know you’re relying on sound information for any decision you make.
Conclusion
Home prices are rising or holding steady in most parts of the country, and a handful of small declines does not equal a nationwide downturn. If you want to know what your home is worth today, review your local numbers with a trusted real estate professional.