Facebook
 X
 Pinterest
 Copy Link
Condos vs. Townhomes: Affordable Buying Options in 2026
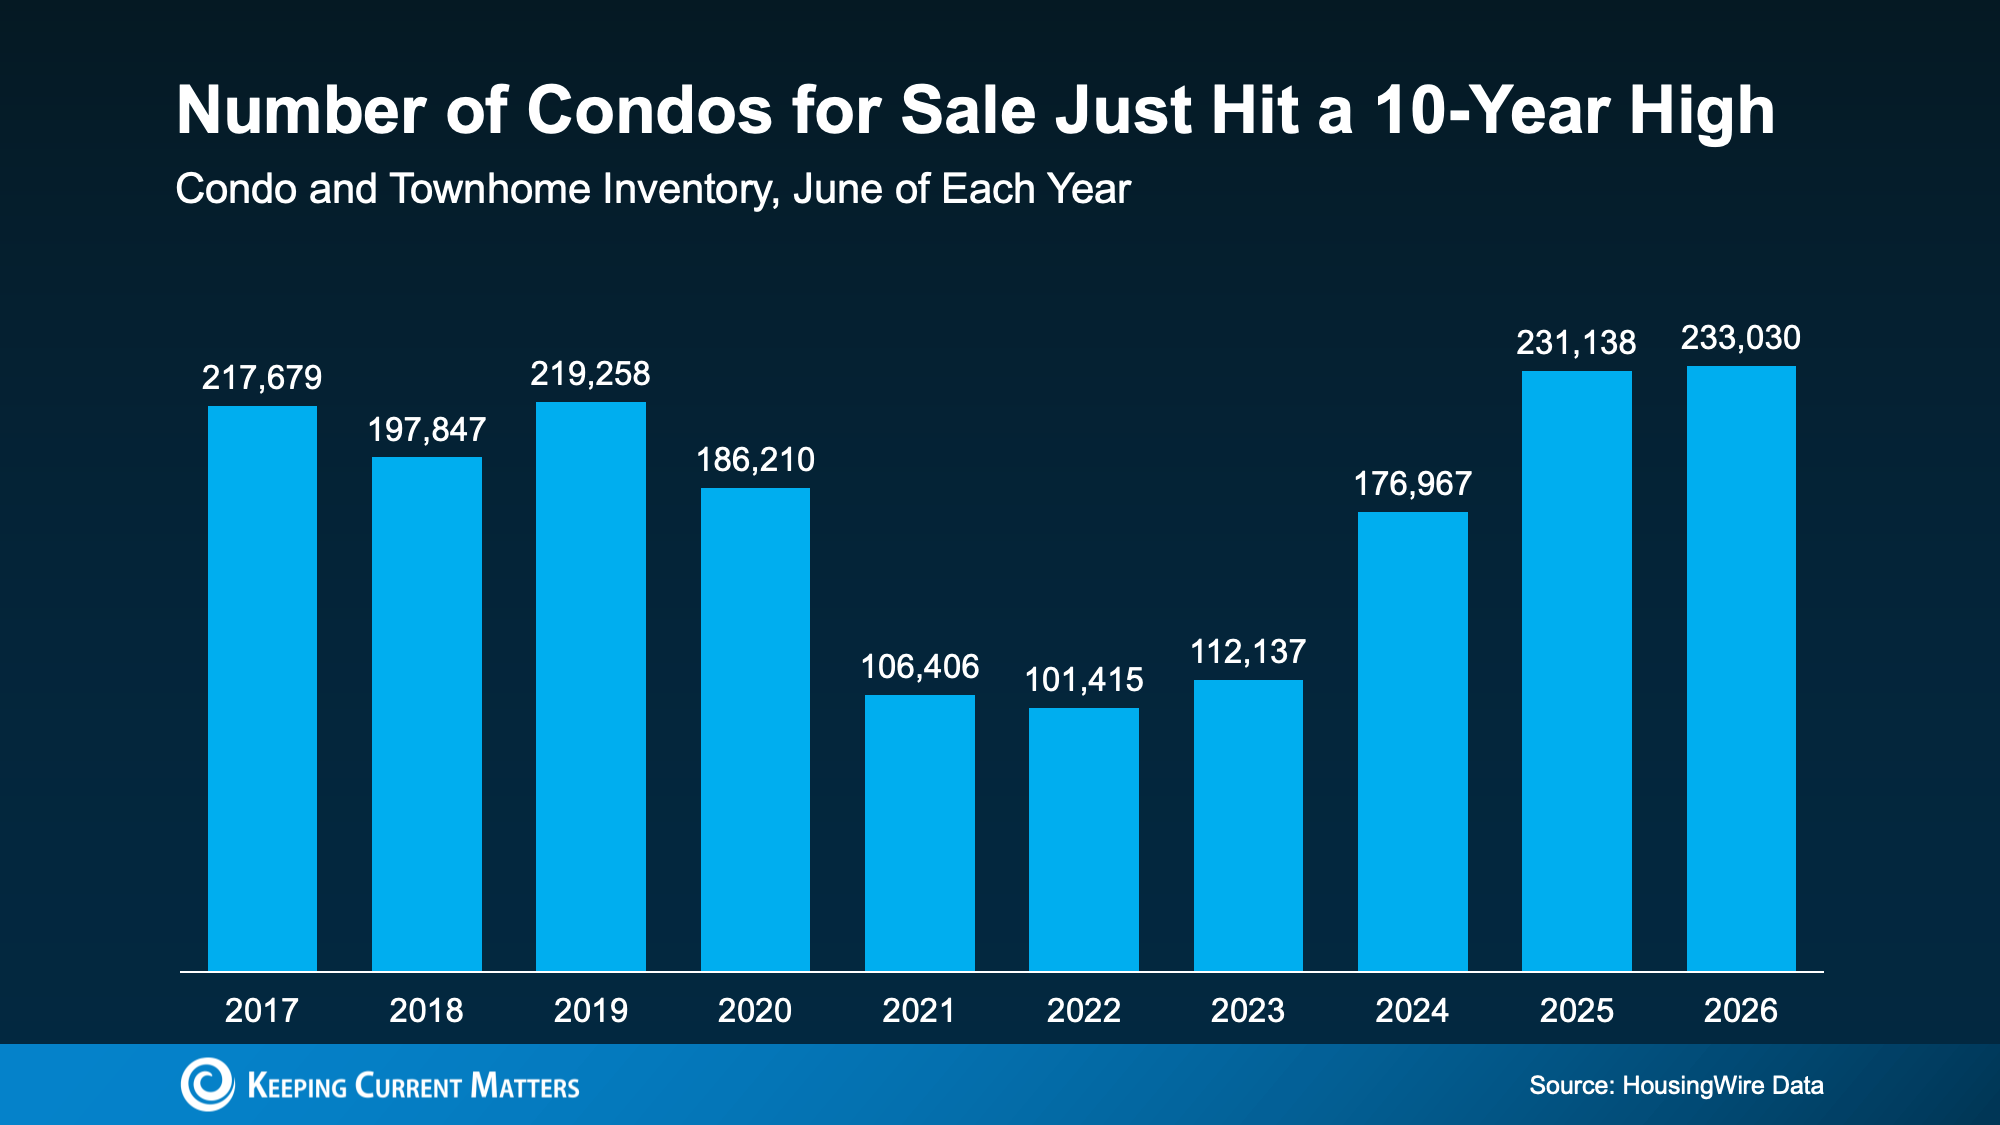
The number of condos and townhomes for sale reached 233,030 in June 2026, giving buyers the most inventory shown in a decade. Source: HousingWire.
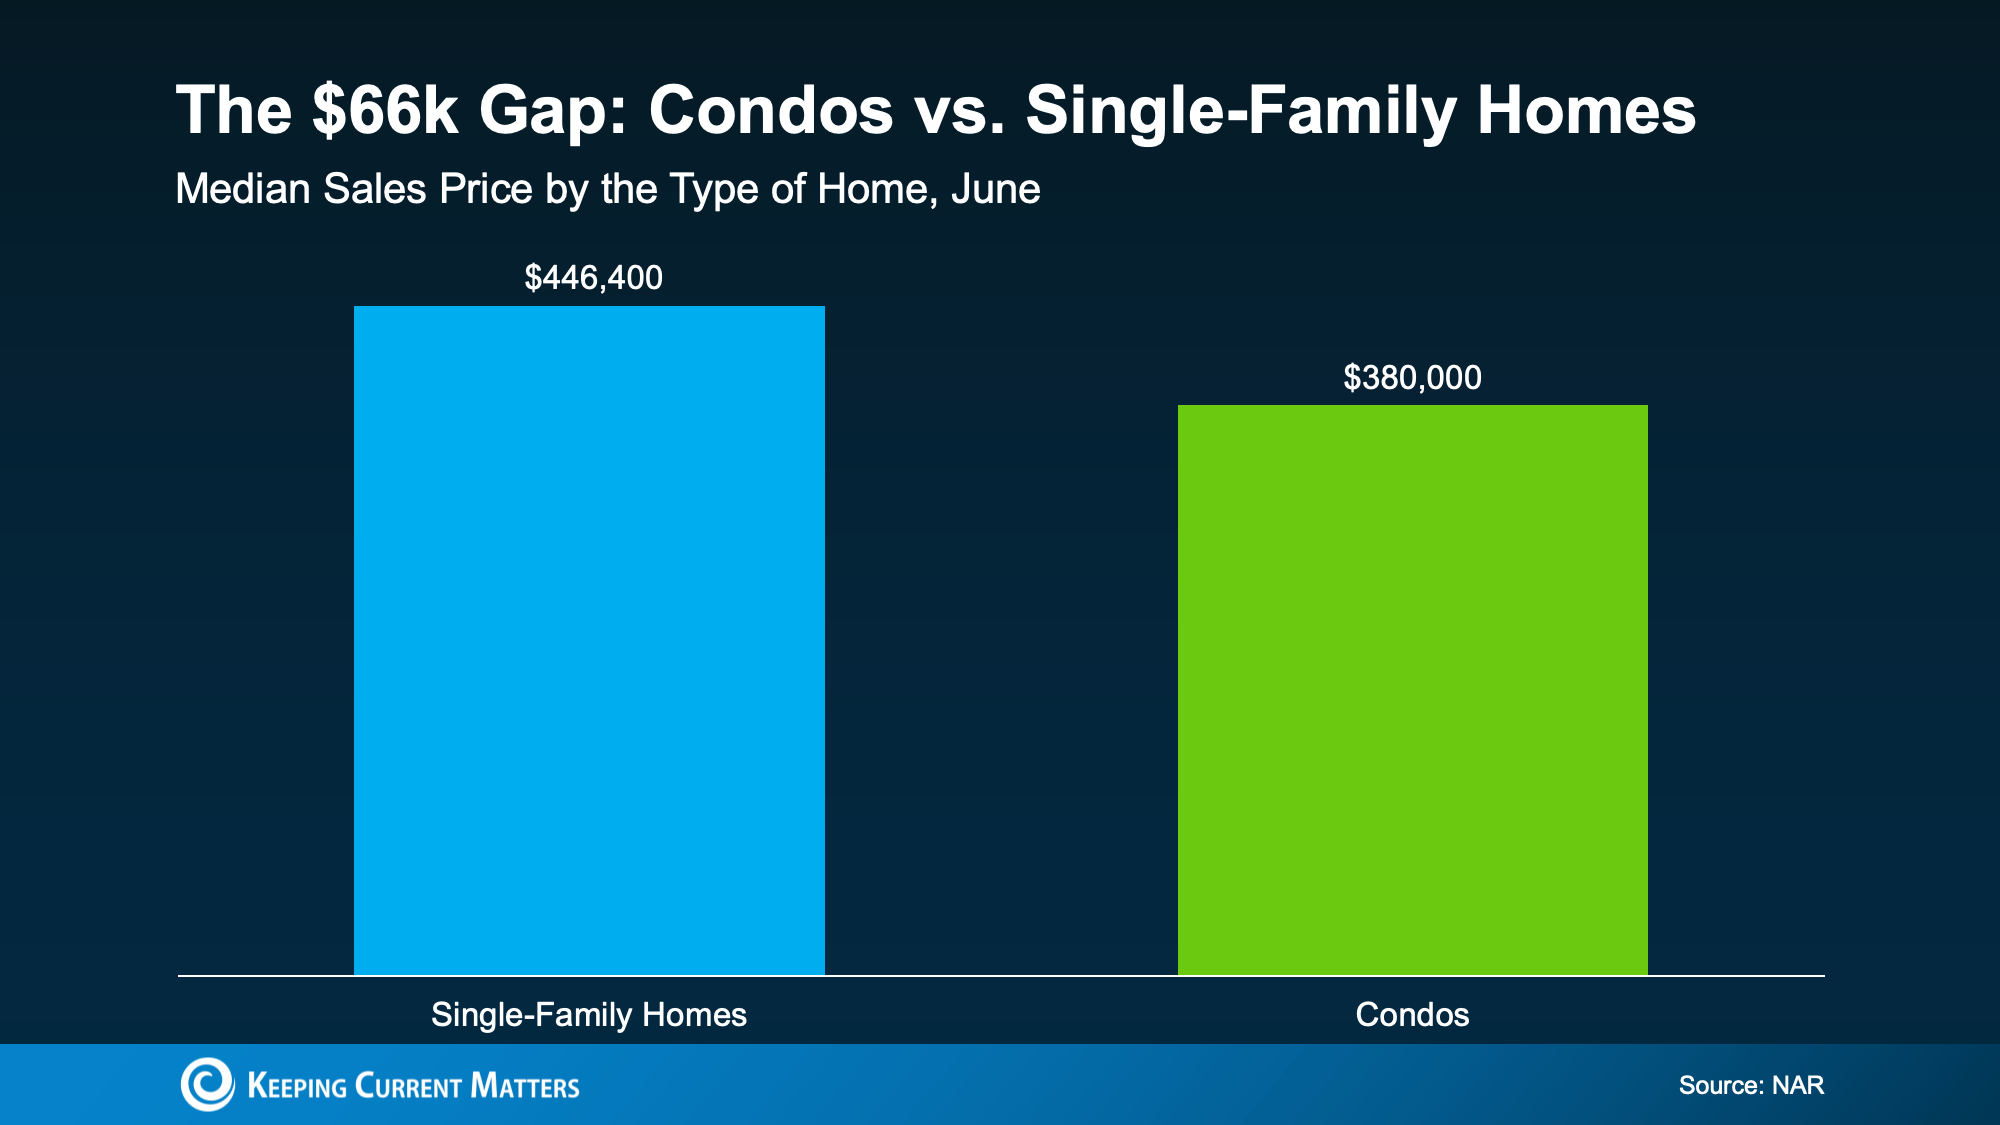
A lower median sales price may make condos a more attainable alternative for buyers priced out of single-family homes. Source: NAR.
Although the terms are sometimes used interchangeably, condos and townhomes aren’t necessarily the same.
Condos
-
Ownership: You own the interior living area of your specific unit. Shared building elements and community spaces are jointly owned by all residents.
-
Amenities: Access to shared amenities like workout rooms, pools, or community spaces.
-
Upkeep: Minimal individual exterior maintenance responsibility. Comes with shared building decisions, shared walls, and regular HOA fees to cover common area upkeep and exterior repairs.
Townhomes
-
Ownership: You own the multi-level building structure and the specific lot beneath it.
-
Layout: Typically multi-story attached structures, sharing at most two side walls.
-
Upkeep: Provides greater autonomy over design and repairs, with exterior maintenance duties usually shared or managed under specific HOA guidelines.
A condominium is technically a form of ownership rather than a particular building style. A condo could be located in a multistory building, resemble a traditional townhome, or even be detached. Likewise, a townhome may be sold with its land or organized legally as a condominium.
Summer Housing Market Guide: More Choices, Better Prices
If you paused your home search over the past few years, you likely ran into two major hurdles: asking prices that kept climbing and a frustrating lack of homes for sale.
This summer, both challenges are starting to ease in many markets. Buyers are seeing more homes for sale, while more sellers are reconsidering their asking prices.
Here’s a closer look at current summer real estate market trends and what they mean for your home search.
Sellers Are Pricing Homes to Attract Buyers
Sellers are adjusting their strategy to meet current market reality. According to Realtor.com data, the national median asking price was $430,000 in June, nearly $11,000 lower than last year.
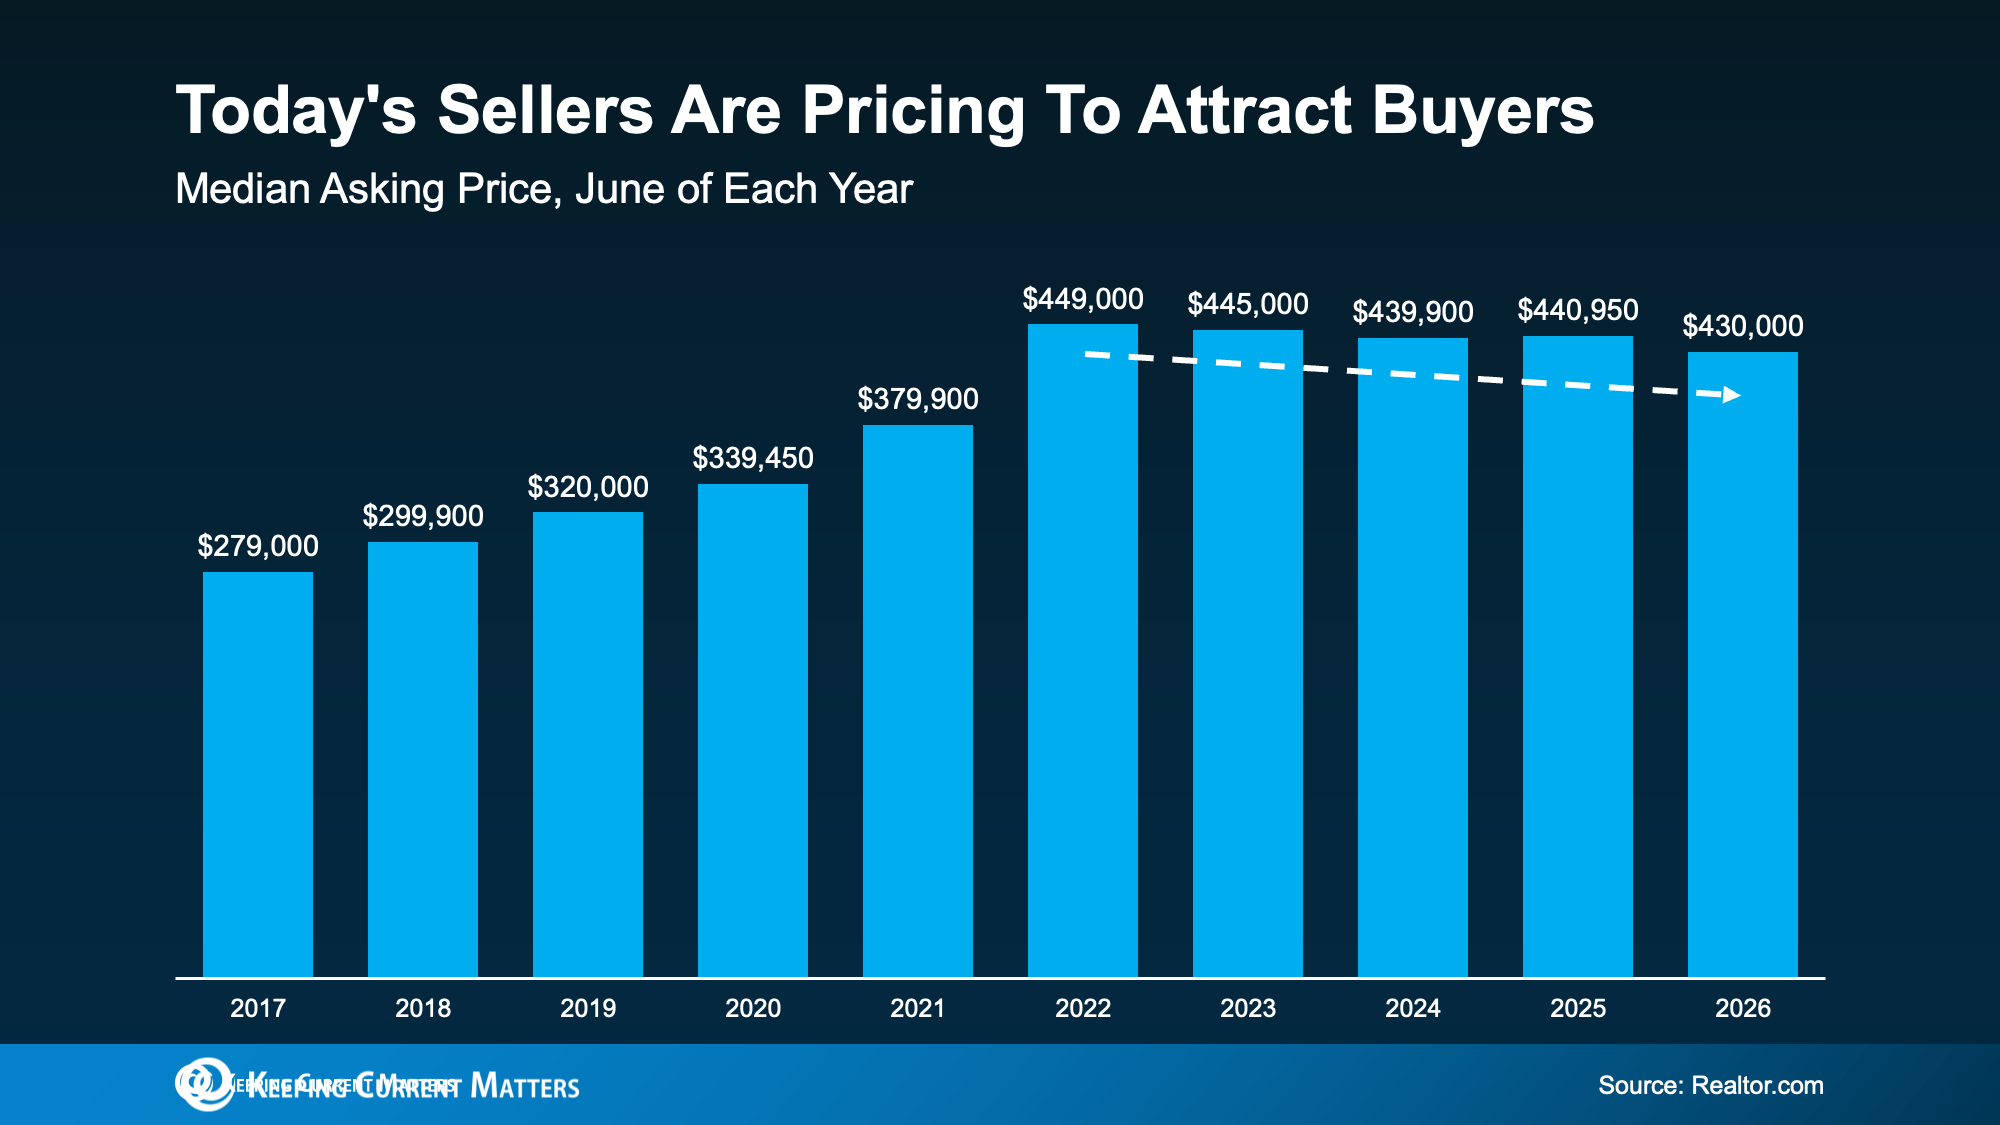
June also marked the eighth consecutive month in which the typical asking price was lower than it had been during the same period one year earlier.
While ongoing price drops might sound concerning at first, it’s not a sign of a market crash. This data tracks asking prices rather than final sold prices, signaling that sellers are setting realistic expectations right from the start.
As Danielle Hale, Chief Economist at Realtor.com, explains:
“Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids. This is a welcome sign that we are in a functioning market.”
Asking prices were never going to rise indefinitely. Now that listing prices are settling closer to realistic buyer budgets, the market is moving toward a healthier, more balanced state.
Housing Inventory Is Catching Up
If you spent previous seasons watching properties disappear before you could even schedule a showing, this is welcome news.
Realtor.com reports that the number of homes listed for sale in June reached its highest June level in three years.
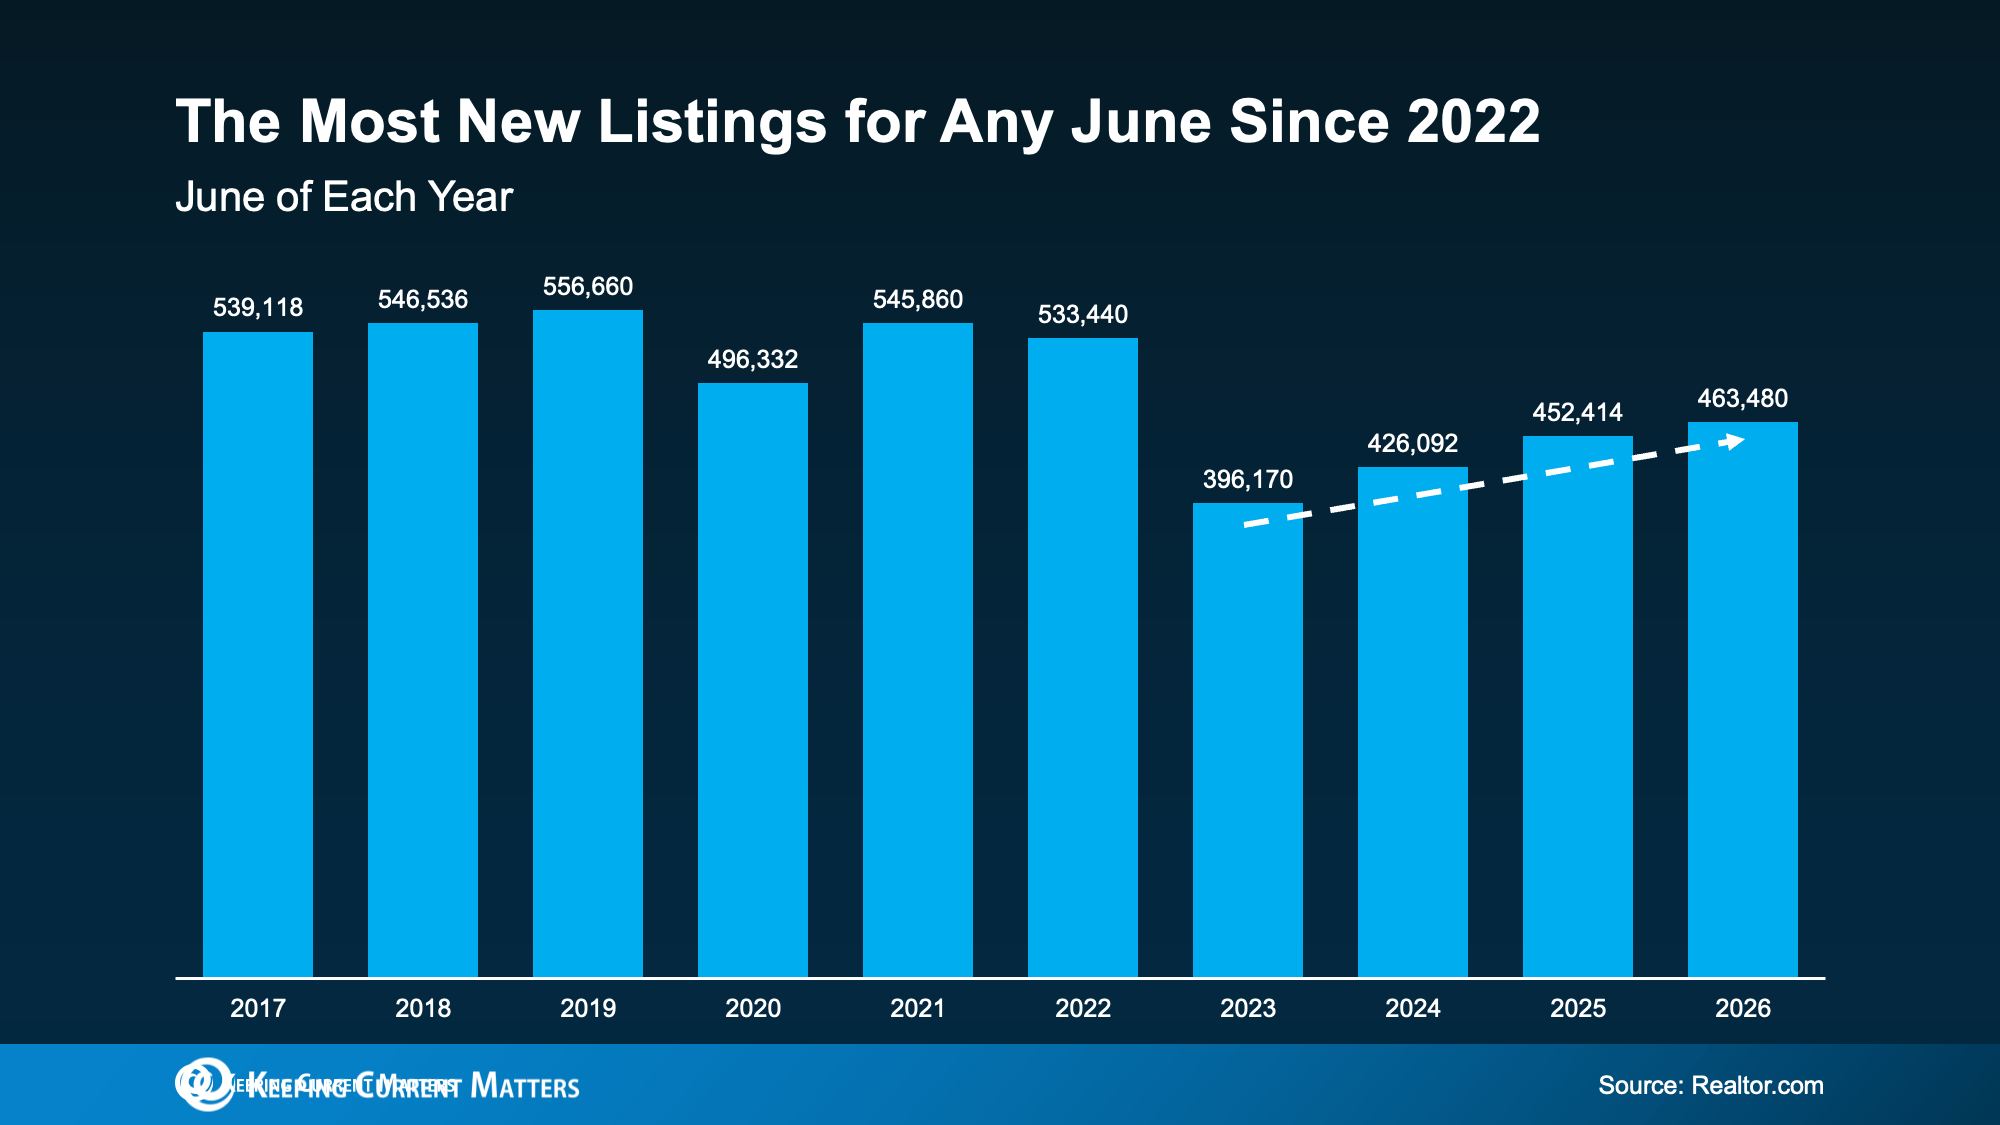
While overall supply has not fully returned to pre-pandemic levels seen between 2017 and 2019, increased listing activity can give buyers:
- More Options: You can evaluate a wider selection of properties rather than settling for what happens to be available.
- Less Urgency: Reduced competition per property means you do not have to rush an offer just to remain in contention.
- Greater Negotiation Leverage: With more inventory on the market, you have more room to negotiate terms and pricing than buyers had a year ago.
Great News for First-Time Home Buyers
These trends are especially encouraging for first-time buyers looking for homes at lower price points.
Mischa Fisher, Chief Economist at Zillow, explains:
“The lowest price tiers are exhibiting some softness in terms of price, they also had the most listing-activity growth, the first time since 2022 that’s been the case.”
In other words, buyers looking for more affordable homes may encounter a little more selection and some additional flexibility on price.
That doesn’t mean every home will be an easy purchase or that competition has disappeared. But it does mean that first-time buyers who paused their home search may be pleasantly surprised by this summer’s market.
Bottom Line
If steep home prices or a lackluster selection caused you to pause your plans, this summer may be a good time to look again.
More homes for sale and lower asking prices could give you additional choices, less pressure, and more room to get a better deal on a house you love.
If you’re ready to restart your search this summer, browse available homes now or contact us today to connect with an expert local agent.
Down Payments Are at Their Lowest Since 2021
Saving for a down payment is often the biggest obstacle to buying a home. With the challenges of affordability today, it’s easy to wonder how anyone manages to save enough cash right now.
But here’s some good news: some buyers are getting into homes with smaller down payments than they may have expected.
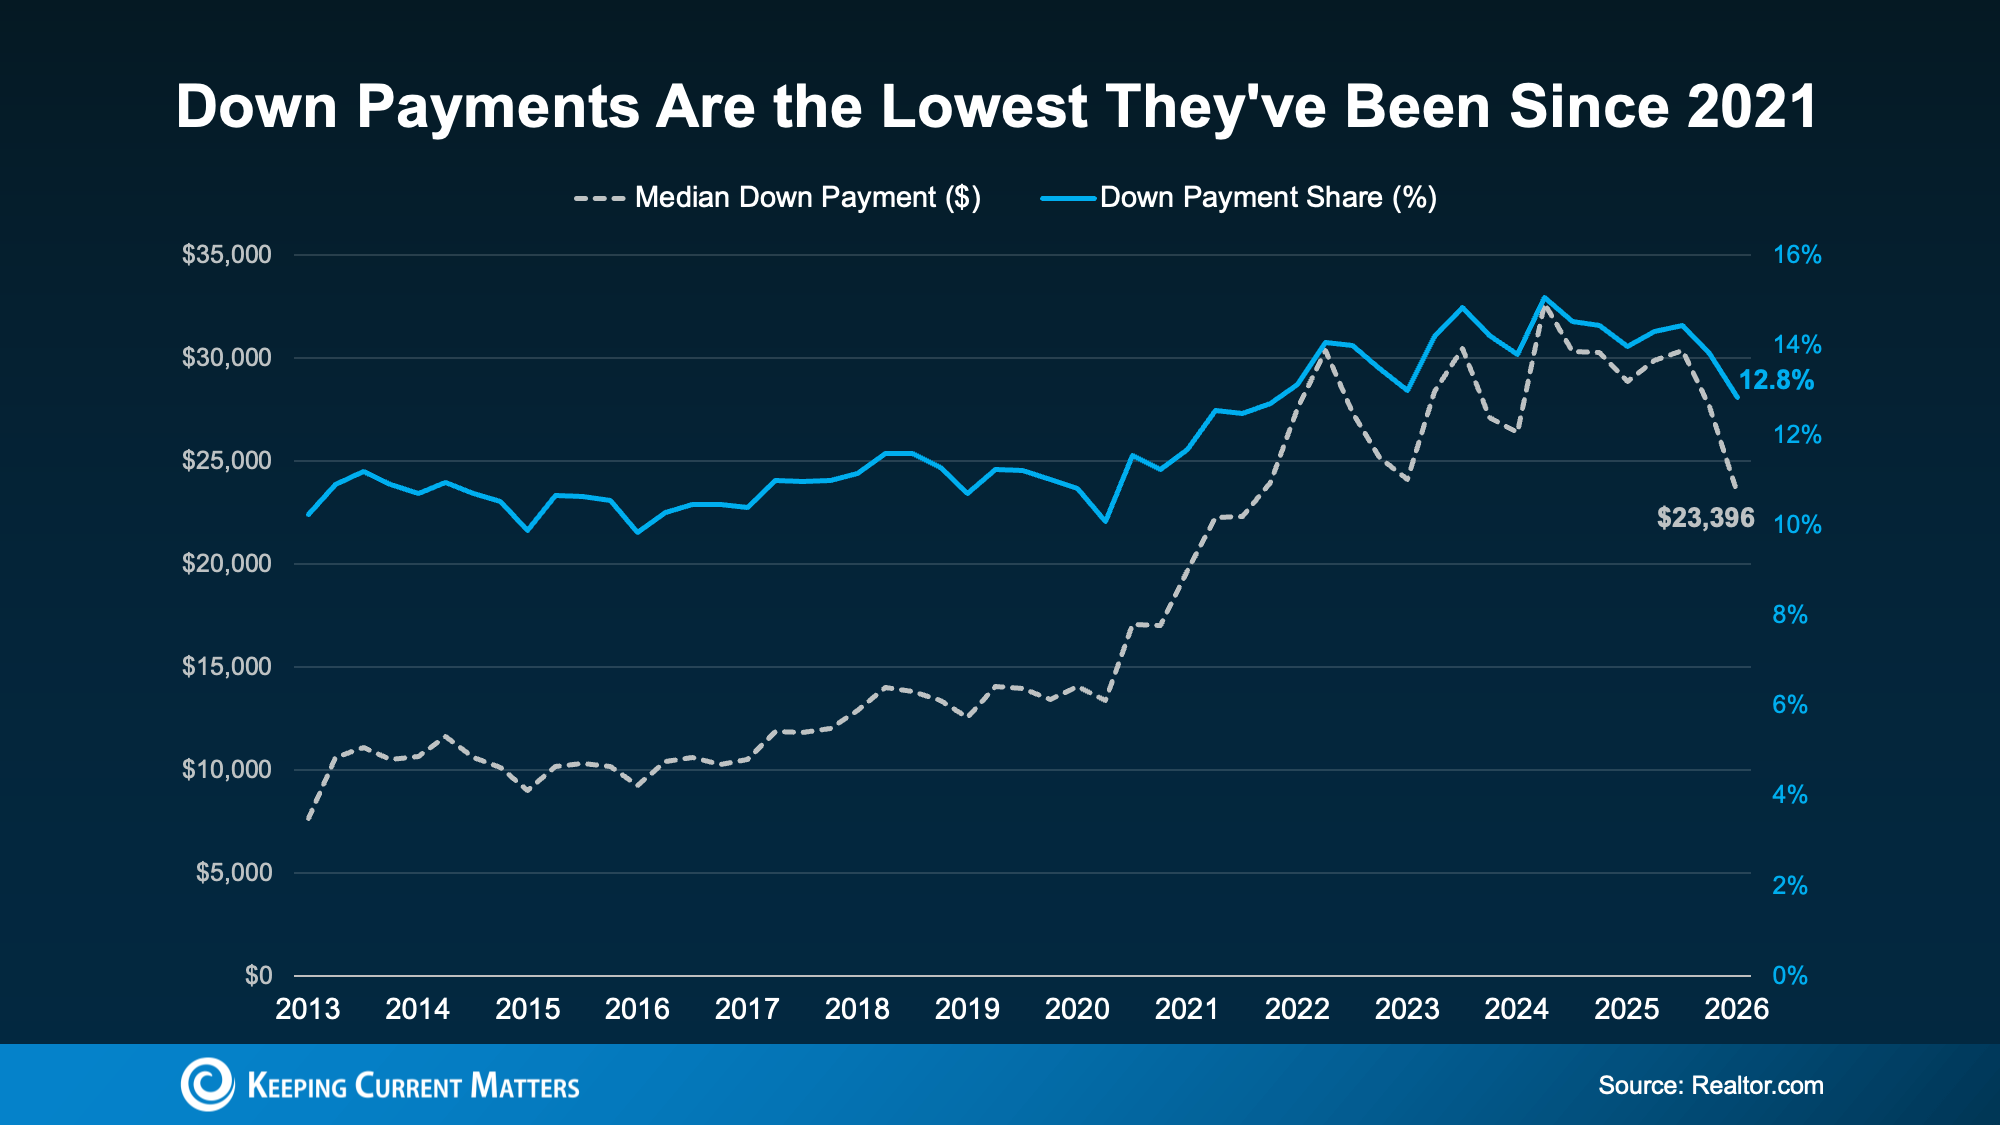
According to Realtor.com, the typical buyer put down about $23,400 in early 2026. That’s about $5,000 less than the year before, a 19% year-over-year drop. It’s also the lowest typical down payment level since 2021.
3 Reasons Why Down Payments Are Shrinking
Why are buyers putting less money down today? Three major shifts in the housing market are driving this trend:
-
Less Competition Between Buyers
In the most competitive markets of the past few years, some buyers felt pressure to put more money down to make their offers stand out.
Today, conditions are more balanced in many areas. With less intense competition, buyers are less pressured to offer a huge down payment to make an offer stand out.
-
Home Price Growth Has Moderated
Your down payment is typically based on a percentage of the purchase price. When home price growth slows or levels off, the dollar amount needed for a down payment can shift too.
In many markets, prices have cooled from the rapid pace seen in recent years. Some areas have even seen slight price dips. That can help reduce the upfront amount some buyers need to save.
-
More Buyers Are Using Lower Down Payment Loan Options
More buyers are also turning to loan programs that often require less money upfront. Government-backed loan options, like FHA loans and VA loans, often allow eligible buyers to purchase with a lower down payment or, in some cases, no down payment. According to Mortgage Professional America, FHA loans have made up more than 24% of purchase mortgages for five straight quarters, while VA loans recently reached their highest share in more than a decade.
Of course, not every buyer will qualify for every program, and any down payment is a huge amount of money to save. To make up the difference, buyers are relying on two things: payment assistance programs and family support.
Financial Help You May Not Know You Qualify For
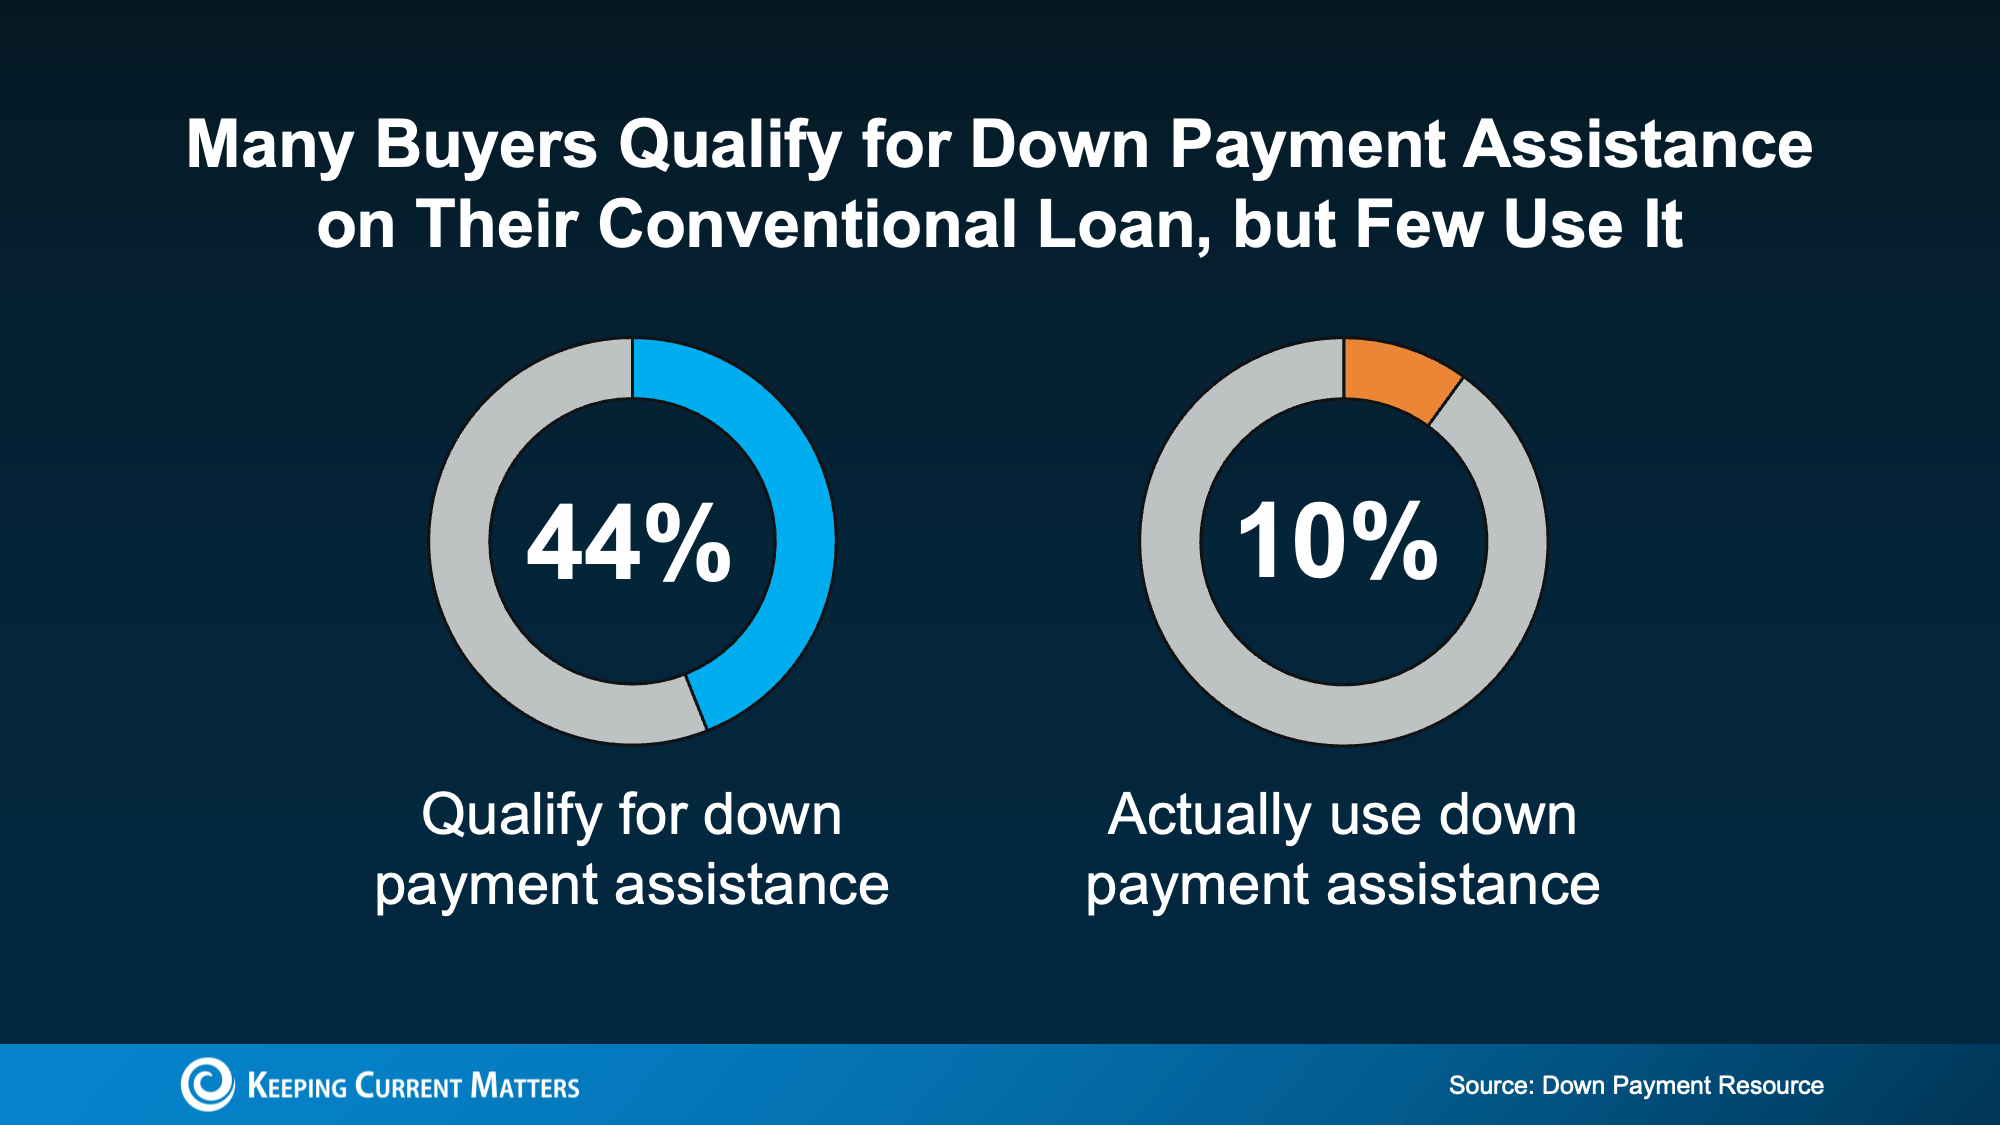
Down payment assistance is one of the most overlooked resources in real estate. A study by the Urban Institute and Down Payment Resource looked at the 10 largest U.S. metros and found that nearly 44% of recent buyers already qualified for a down payment program. Surprisingly, only 10% of those buyers actually used the help when closing on their loan.
There are more options available than many buyers realize. According to Down Payment Resource:
-
There are more than 2,600 down payment assistance programs available.
-
More than half (62%) are designed specifically to help first-time buyers.
-
38% have no first-time buyer requirement, meaning you may qualify even if you’ve owned a home before.
-
62% are open to buyers earning $100,000 or more.
So, don’t assume you’re priced out of a home or ineligible for help. A lender or knowledgeable real estate professional can help you ask the right questions and explore programs that may fit your situation.
A Helping Hand from Loved Ones
A growing number of buyers are also getting help closer to home. Research from Veterans United shows about 59% of parents have provided or plan to provide financial support to help their child buy a home.
That support usually goes toward the down payment, followed by helping the buyer qualify for a mortgage and covering closing costs.
Chris Birk, VP of Mortgage Insight at Veterans United, explains it this way:
“For many families, helping a child buy a home has become less of an optional gesture and more of a practical response to today’s affordability challenges.”
Not everyone has family or loved ones who are able to help. But for buyers who do, it can speed up how quickly they’re able to buy a home.
Bottom Line
Down payments are smaller than they’ve been in years, opening the door for more buyers to enter the market. Between down payment assistance programs and support from family, you may have more paths to homeownership than you realize.
Always consult with a trusted mortgage professional to review your financial situation. If you’re ready to start exploring neighborhoods and discussing your goals, contact our brokerage today to connect with an experienced local real estate agent.
Will Home Prices Crash Soon? What Expert Forecasts Say
A lot of homebuyers are still sitting on the sidelines, waiting for home prices to drop.
Some are waiting for a crash so they can get a better deal. Others are worried they’ll watch their home’s value drop if they buy now.
Nobody wants to feel like they overpaid or bought too early. But there’s an important question to ask:
What if the crash you’re waiting for never happens?
Based on the latest data from experts, a nationwide housing crash isn’t on the horizon.
Experts Are Not Predicting a Housing Market Crash
You’ve probably seen headlines or social media posts lately saying home prices are about to come crashing down.
It’s true that some markets are seeing small price declines. But a local price shifts are not the same as a nationwide housing crash.
According to Realtor.com data, home prices are still rising in 71% of housing markets across the country.
Unfortunately, negative news tends to get more attention. Stories about price declines in a handful of markets can make it seem like prices are falling everywhere, even when most markets show the opposite.
So, how can buyers get a clearer picture of where home prices may be headed?
One trustworthy source is the Home Price Expectations Survey (HPES) from Fannie Mae.
The 5-Year Home Price Forecast
Each quarter, the HPES asks more than 100 economists, housing experts, and market analysts where they believe home prices are headed based on the most current data.
Even amid today’s ongoing market uncertainty, these experts agreed on one key point:
They do not think a housing crash is coming.
Instead, the average of their forecasts shows home prices rising every year for at least the next five years.
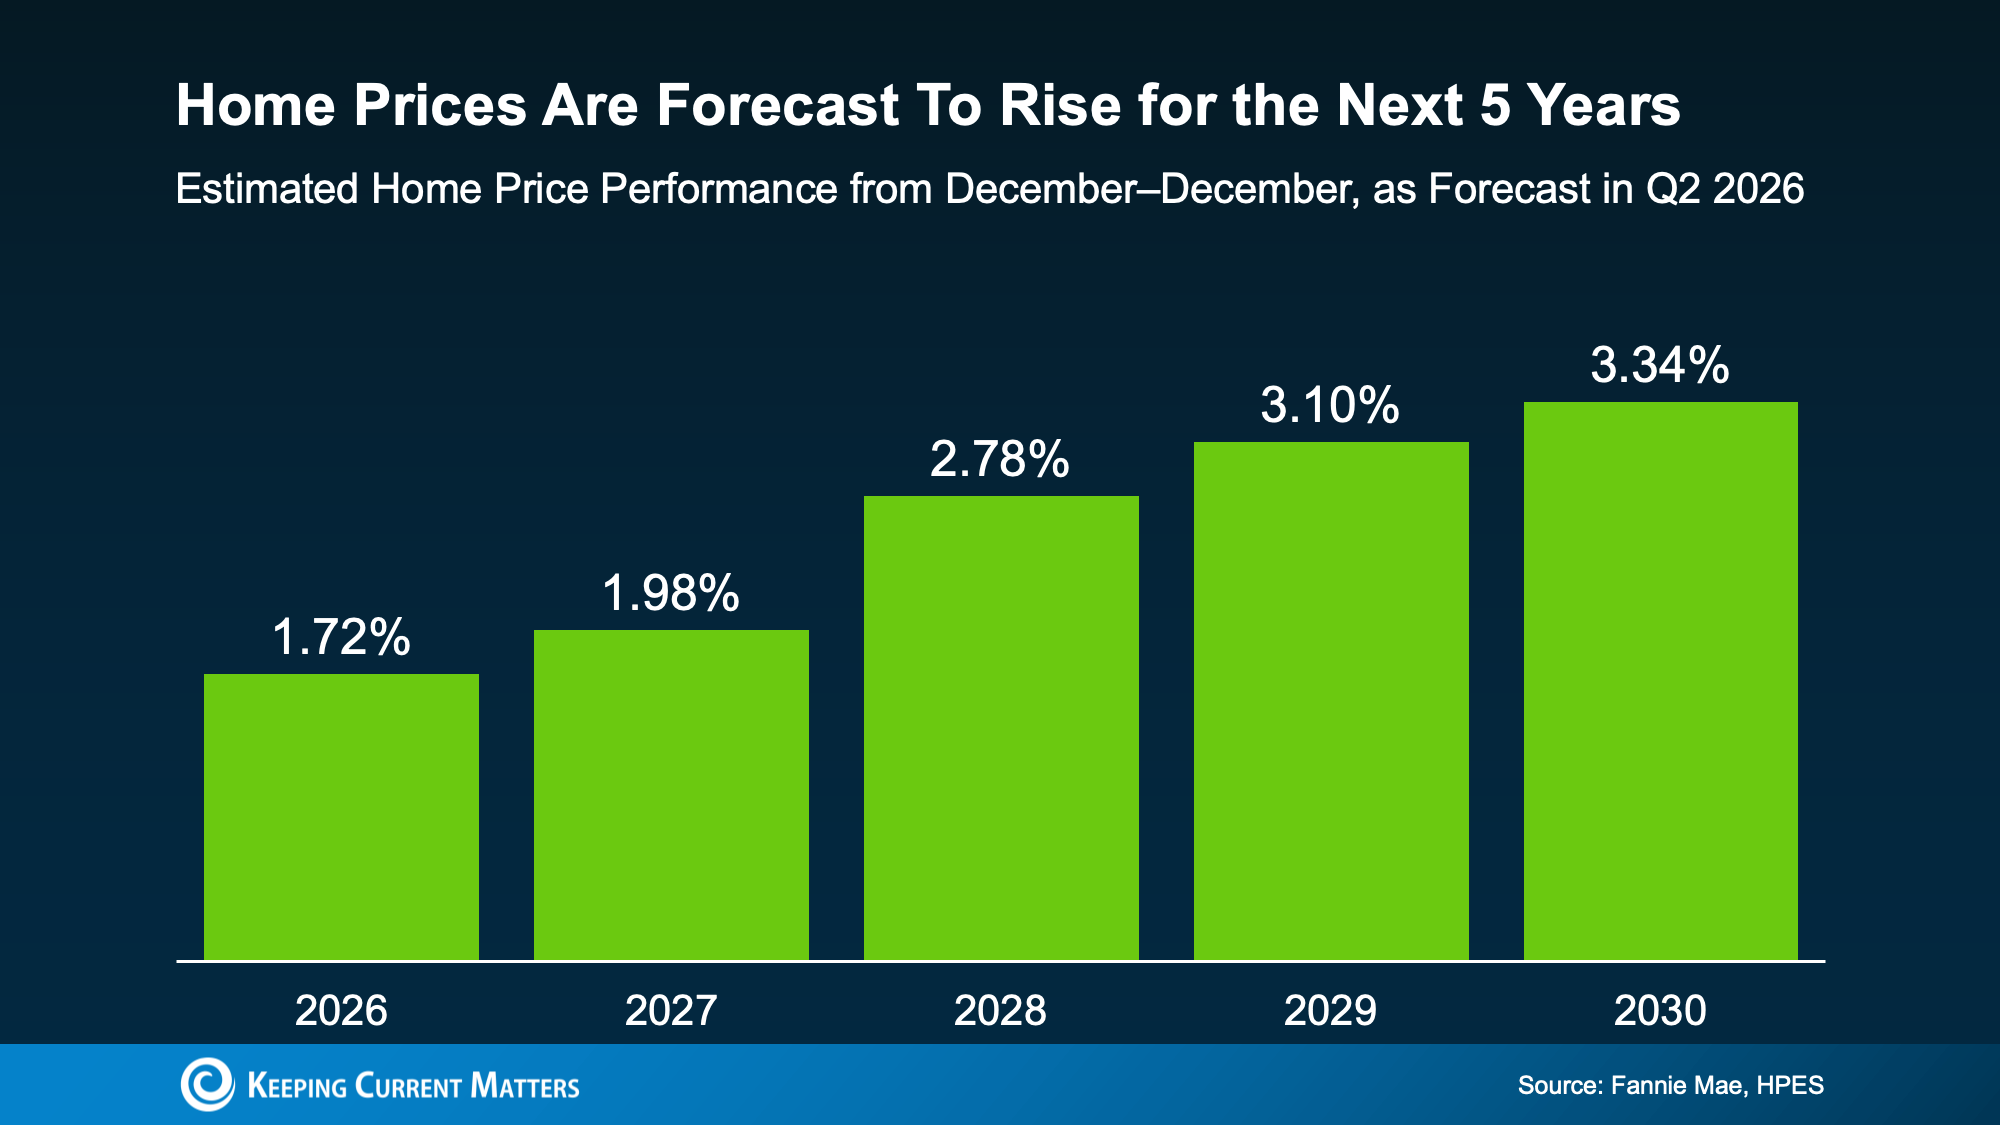
The expectation is for home prices to grow at a more normal pace, unlike the spikes we saw five years ago.
Even the Pessimists Expect Growth
One reason the HPES is useful is that it doesn’t only include optimistic forecasts.
Researchers divided the panel into groups based on how bullish or bearish they were regarding the housing market. Even the most pessimistic group still forecasted that home prices would climb over the next five years.
- The Optimists: Forecast roughly 4.0% annual growth.
- The Pessimists: Forecast roughly 1.0% annual growth.
- The Average: Expects 2.6% annual growth.
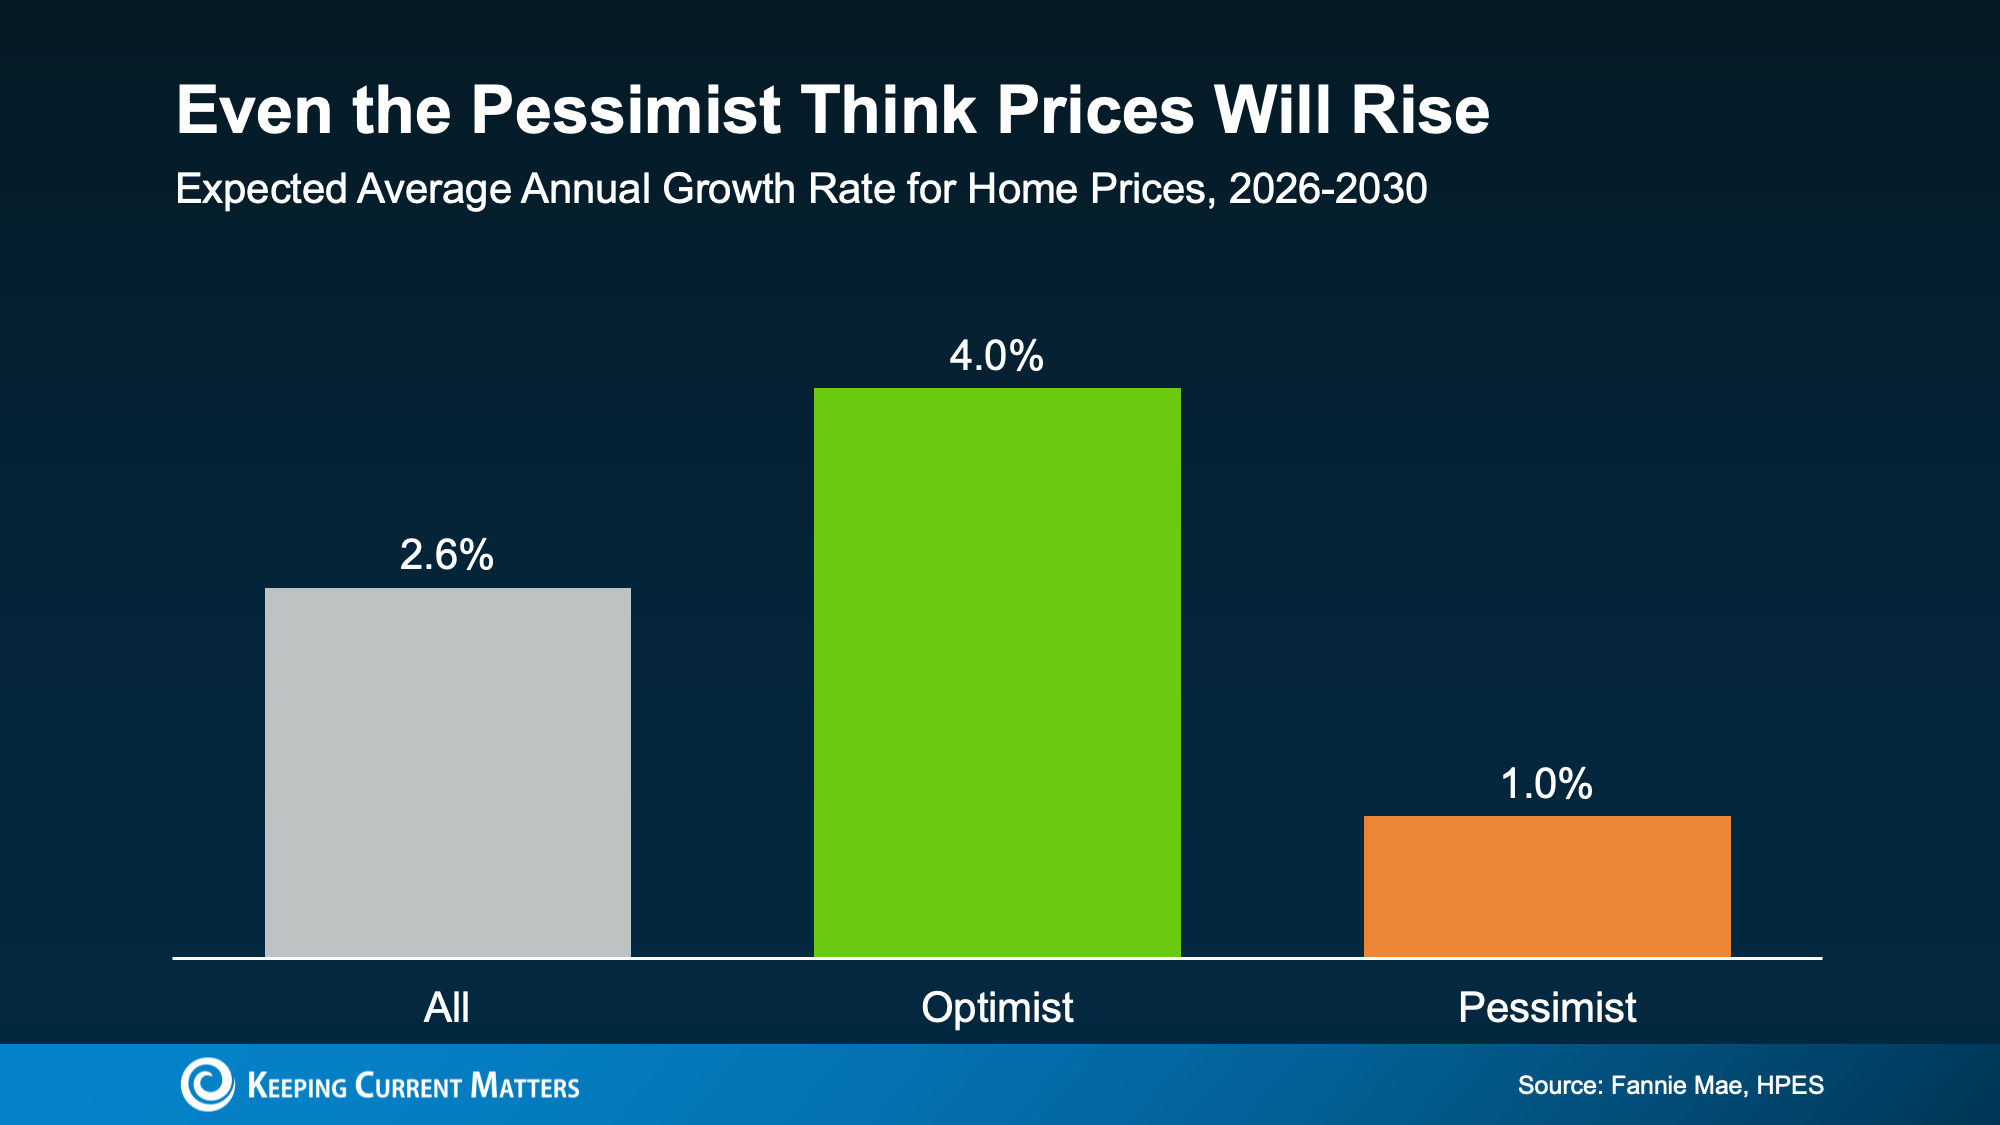
The current debate among housing experts isn’t about whether prices will crash, but rather how much they’ll rise.
That is very different from what many buyers may be seeing on social media.
Waiting for Prices To Fall Could Cost You
If you’re waiting to buy until prices come down, you may be disappointed.
Based on the HPES forecast, a buyer who purchased a $400,000 home this January could gain nearly $40,000 in equity over the next five years from appreciation alone.
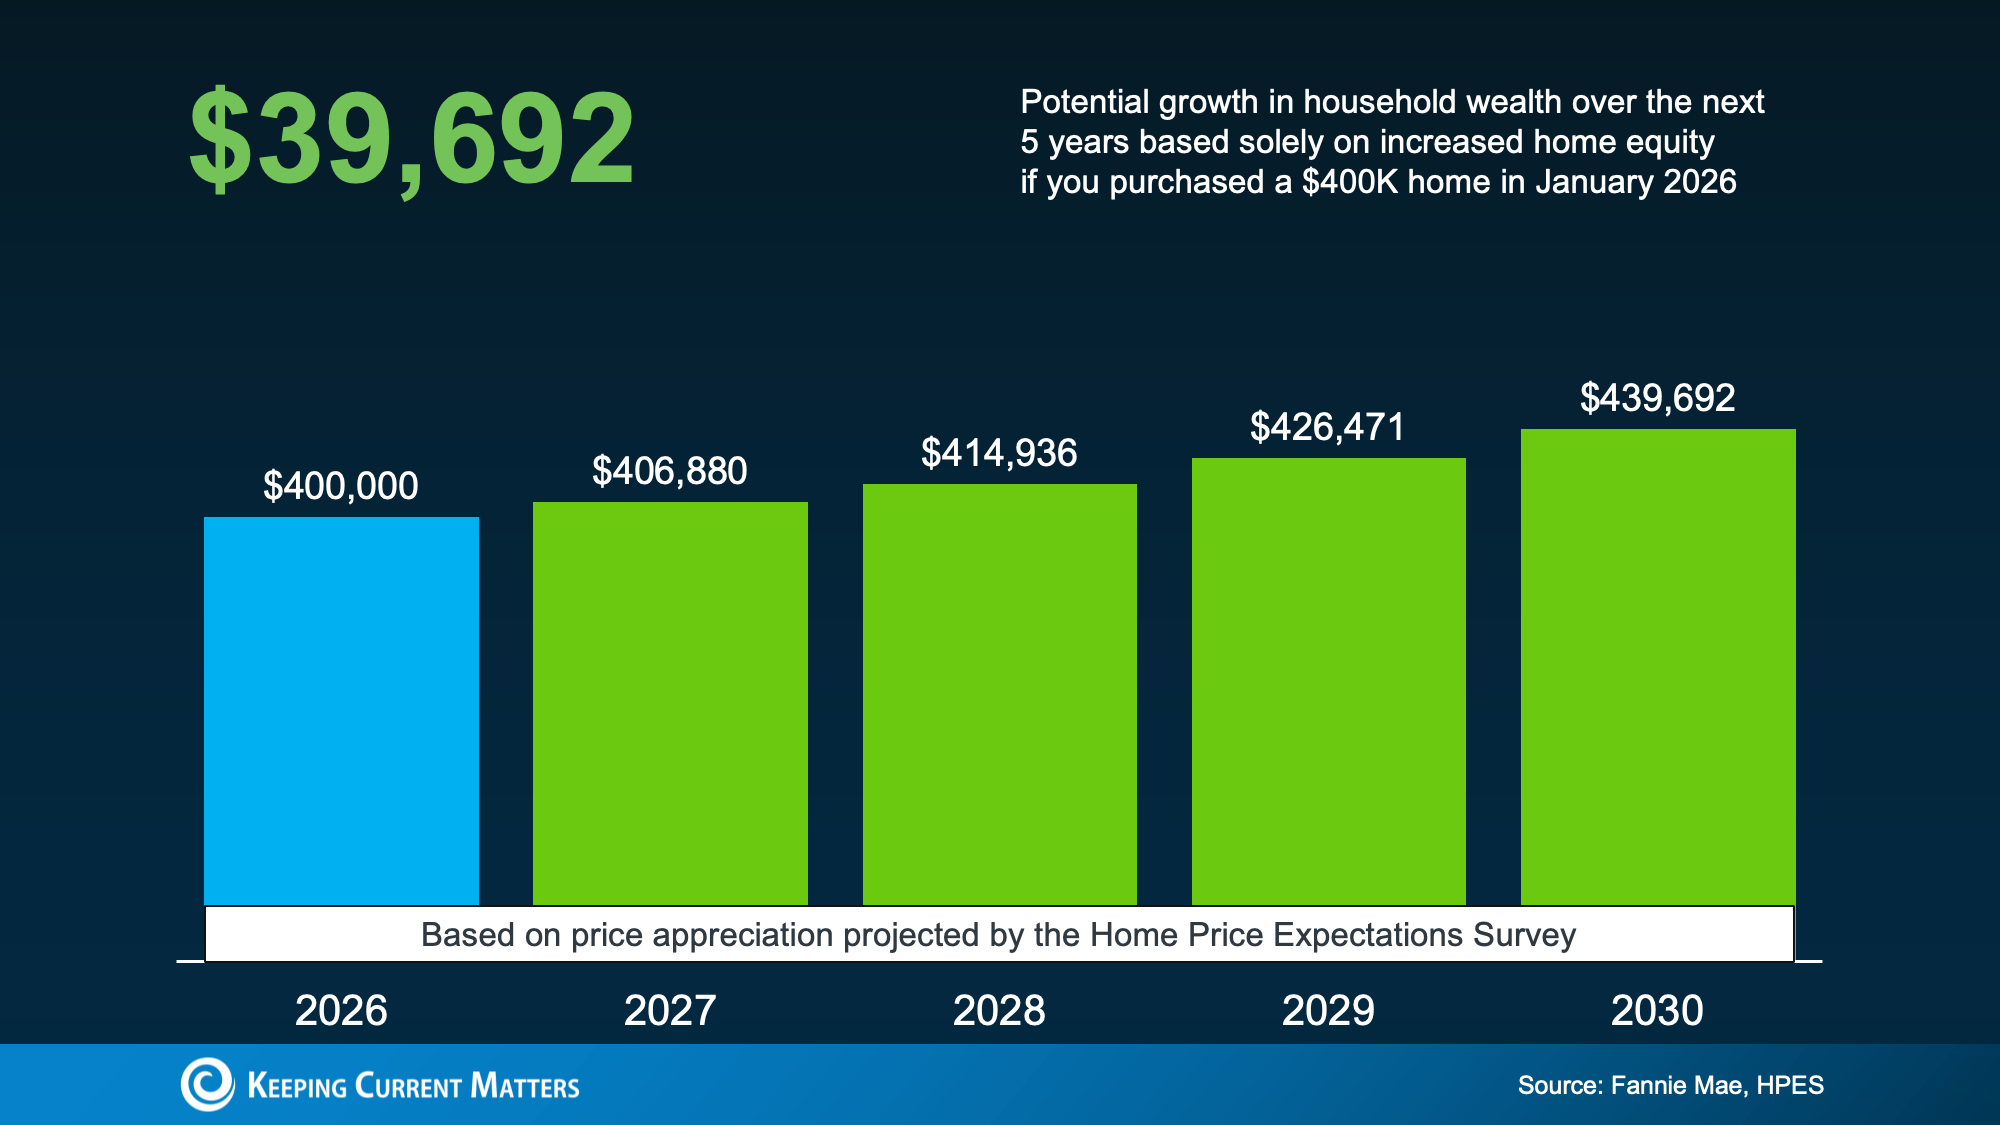
Of course, that is based on a national forecast. Real estate is local, and every market behaves differently.
But broadly speaking, the risk for buyers may not be buying before a crash. It may be waiting for a crash that never happens.
Depending on your specific market, holding off could mean missing out on considerable equity or having to pay tens of thousands of dollars more for the same house five years from now.
Bottom Line
Many buyers are waiting because they believe home prices will fall, but that’s not what experts are predicting.
Home prices are expected to rise more moderately over the next several years, and even the more cautious experts don’t expect a major drop.
Before you put your plans on hold, talk with a local real estate agent who can walk you through what’s happening in your market and help you decide what makes sense for your next move.
Two Big Reasons This Summer May Be the Right Time To Move
A lot of hopeful buyers and sellers are asking the same question right now: “Should I move this summer, or wait until later this year?”
Waiting can feel like the safer choice, especially if you’re hoping mortgage rates will drop or market conditions will feel more predictable. But there’s something important to keep in mind: rates aren’t expected to change much, so waiting may not create the advantage you’re hoping for.
Summer has historically been one of the strongest seasons of the year for both buyers and sellers. And if you delay your move until fall or winter, some of the best seasonal opportunities may start to fade.
Here are two big reasons a summer move may be worth considering.
1. Buyers May See More Fresh Inventory in Summer
One of the biggest challenges buyers have faced in recent years is a lack of affordable options.
Maybe this sounds familiar:
- You find a home you like, but it’s outside your budget.
- You find something in your price range, but it doesn’t fit your needs.
- Or nothing new and interesting hits the market for weeks.
The Summer real estate market often helps with this.
Looking at data from the Realtor.com, summer months consistently bring more sellers into the market than later in the year. This gives buyers a real window of opportunity to see fresh listings.
According to the data, any given summer month typically sees about 32% more fresh options than the average month from September through December.
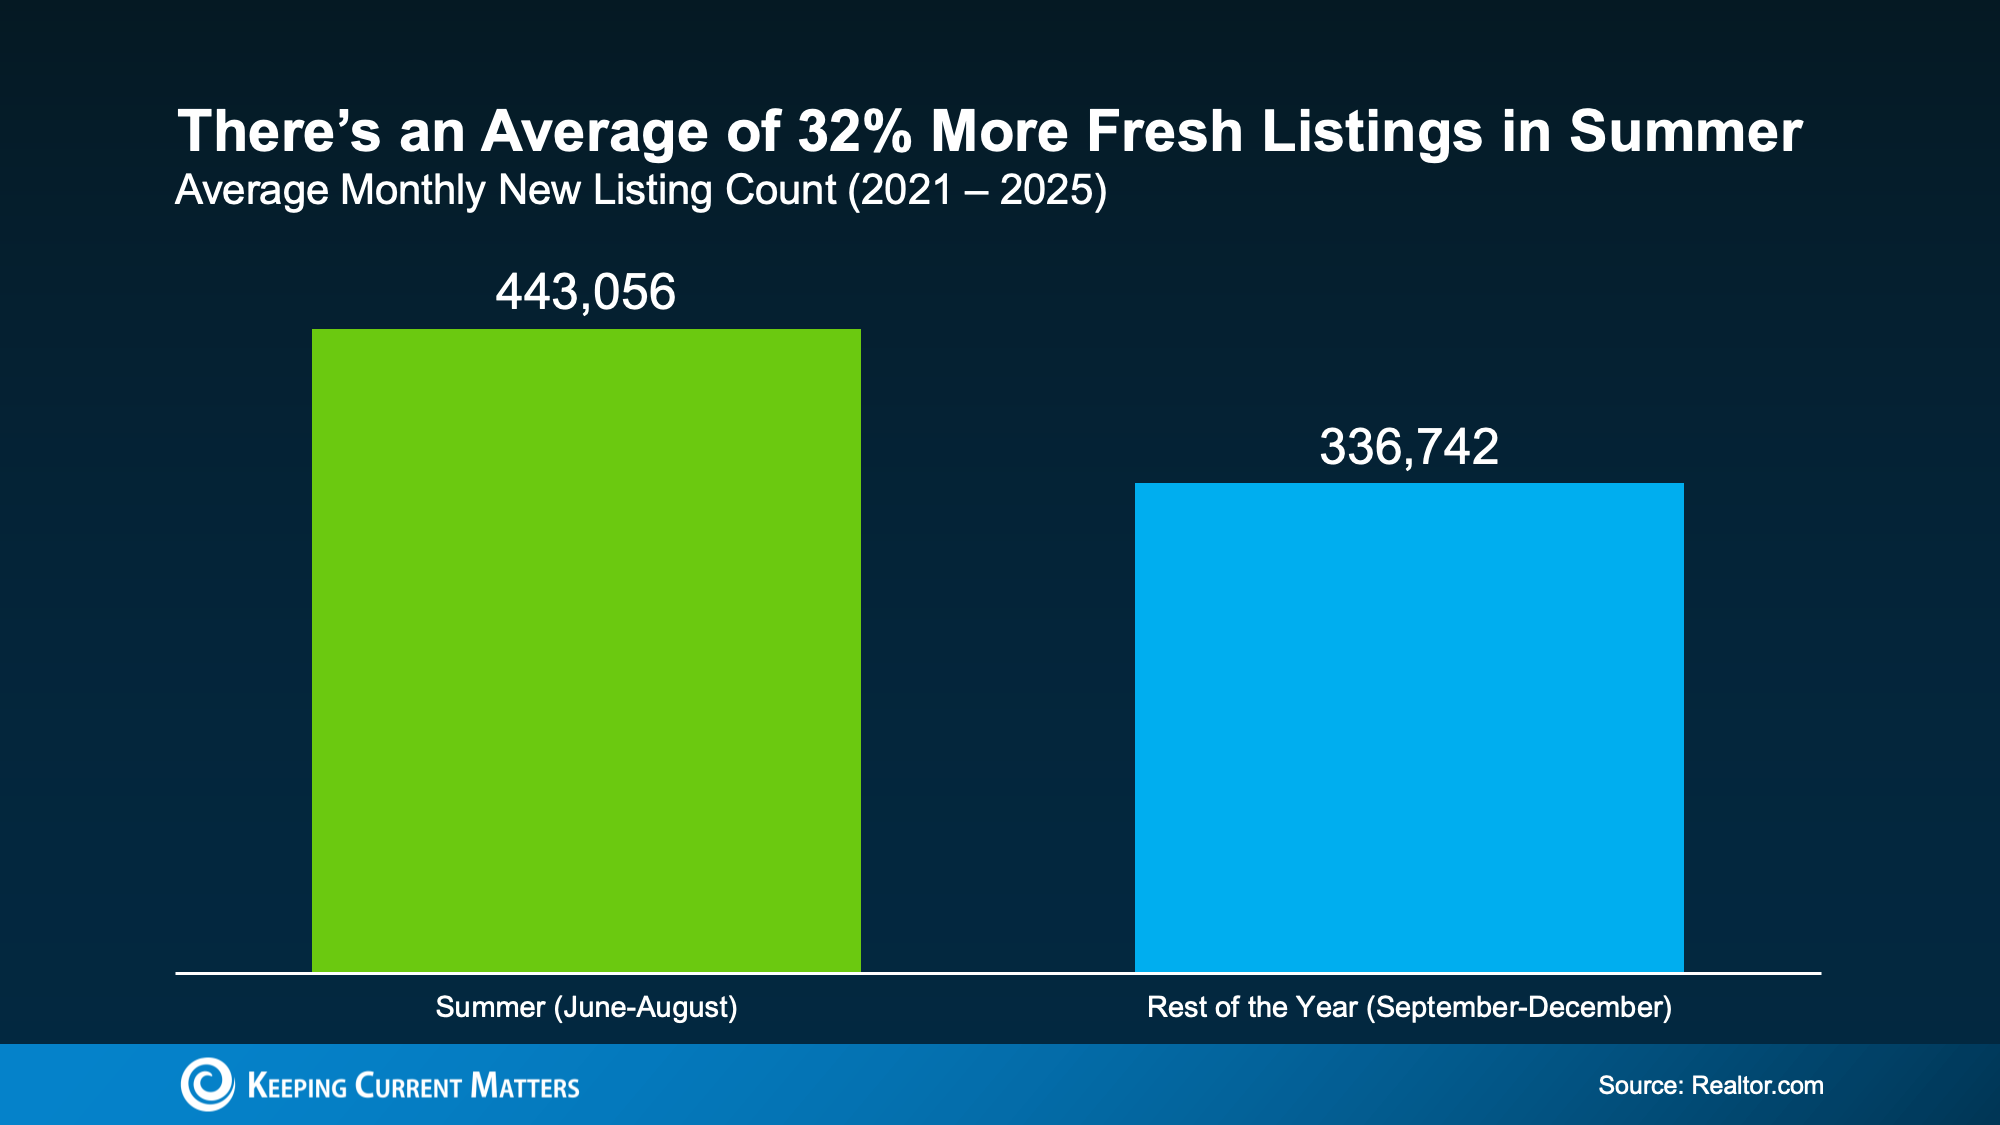
As a buyer, more newly listed homes can increase your chances of finding one that fits both your wish list and your budget. After all, it takes is the one right home hitting the market to change your whole search.
Why Waiting May Limit Your Choices
The summer listing window doesn’t stick around: new inventory tends to slow once summer ends.
By fall, many homeowners who planned to sell have already listed. Some buyers and sellers who were aiming to move before school-year schedules resume may have already made their move or started the process. As a result, new listing activity usually cools heading into fall and winter.
Every year is different, and every local market has its own patterns. But if finding the right home at the right price has been your biggest challenge, waiting until later in the year may not necessarily give you more options.
2. Sellers Often Benefit From Summer Seasonality
If you’re thinking about selling, you may be wondering whether now is the right time. Headlines about lower asking prices, price reductions, and softer market conditions in some areas can make it feel like the moment has passed.
But those headlines don’t tell the full story.
The market is becoming more balanced, and some areas may be experiencing price declines. Still, that does not mean sellers have missed their chance. Seasonality can still work in your favor, depending on your local market and your pricing strategy.
According to the National Association of Realtors (NAR), homes sold during a summer month usually sell for about 4% more than homes sold during the typical month from September through December.
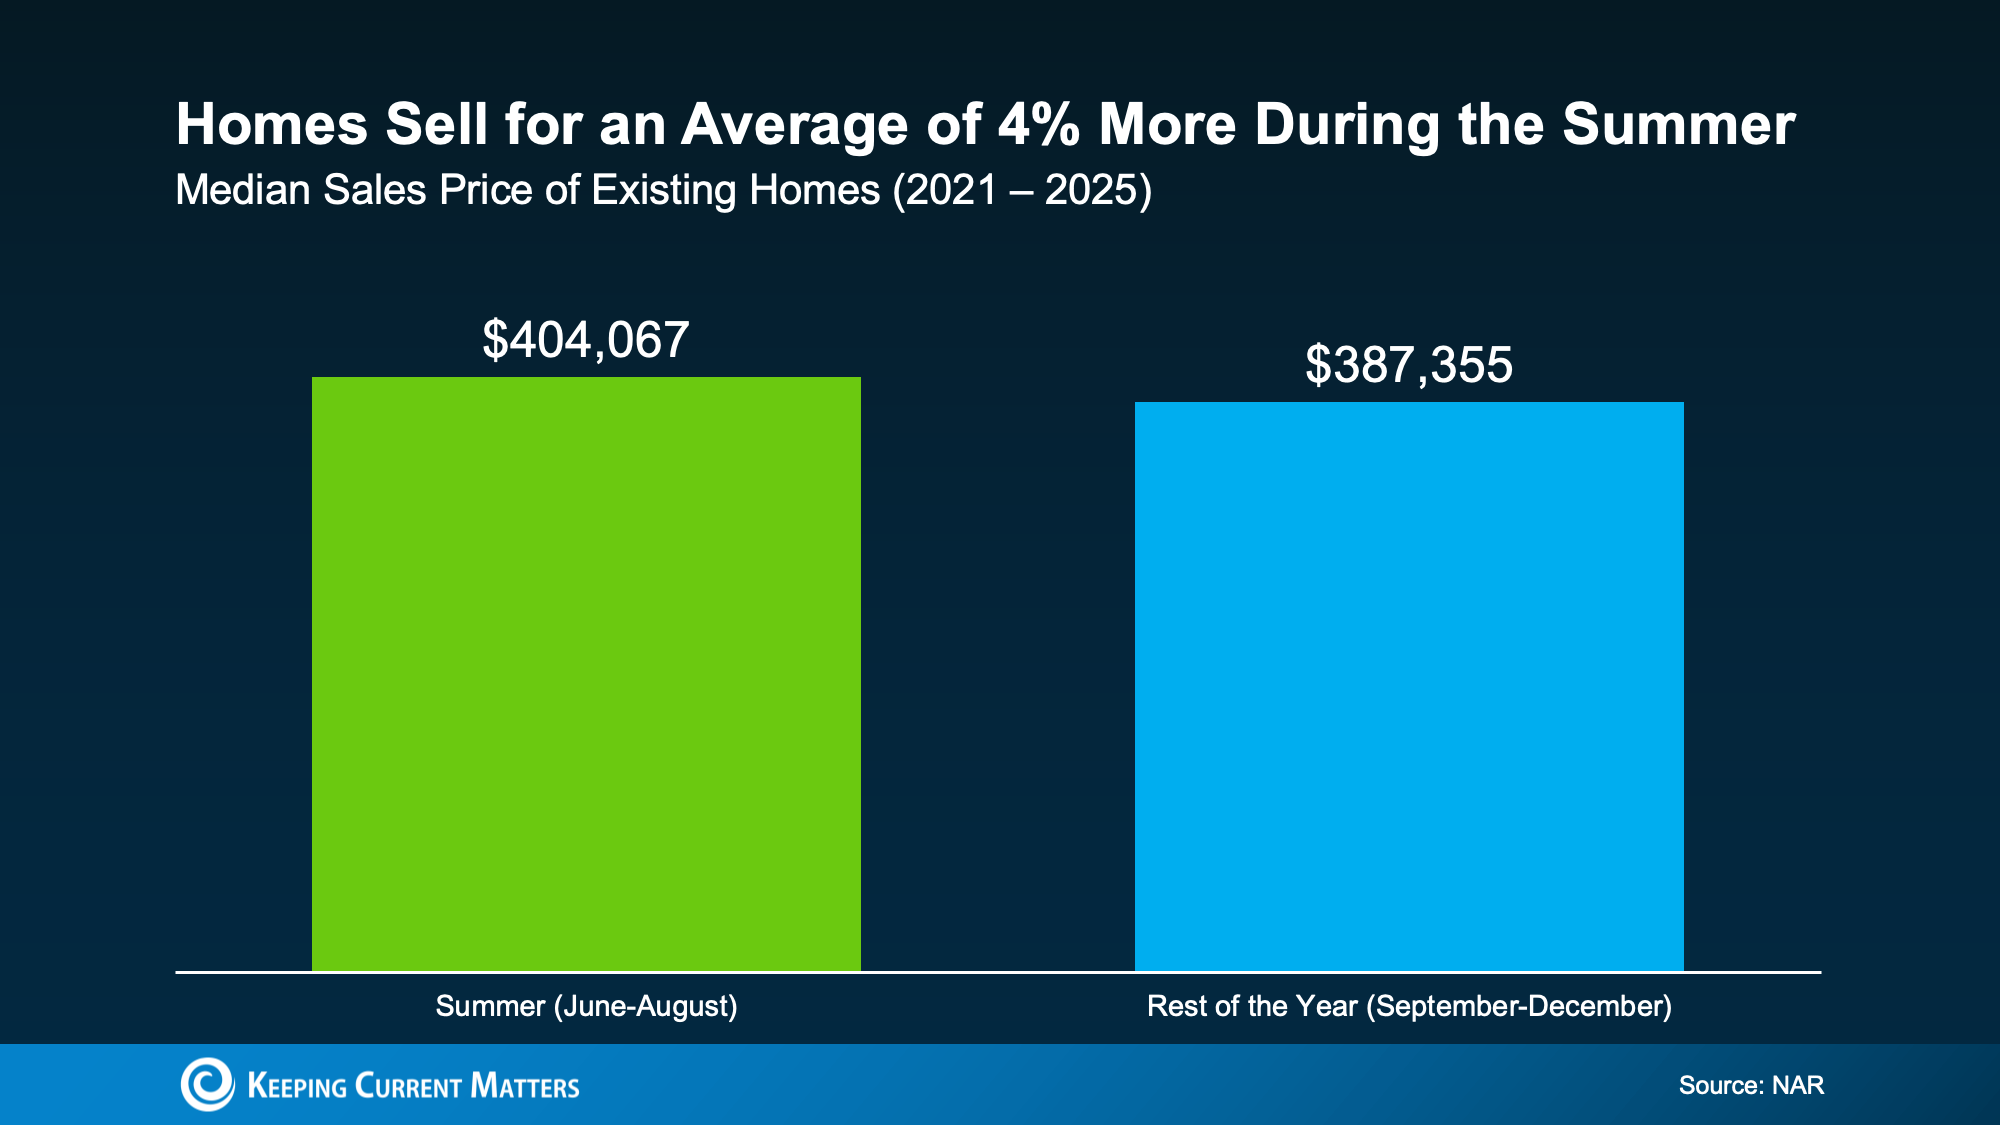
With that said, this doesn’t mean you should price your home 4% higher. In today’s market, overpricing can turn buyers away and cause your home to sit longer than expected.
Instead, consider the timing of your listing. If your goal is to sell for as much as you reasonably can, listing during summer may be a stronger move than waiting until later in the year, when there are typically fewer active buyers.
Why Summer Buyers May Be Motivated
Summer buyers often have a timeline in mind. They may want to move before the next school year, take advantage of warmer weather, or use available time off to tour homes and coordinate a move.
That sense of timing can lead to stronger activity and, in some cases, better offers.
Again, this depends on your local market, your home’s condition, and how well it is priced. But if you were already considering a move in 2026, summer timing deserves a closer look.
Bottom Line
Can you still buy or sell later this year? Of course. But understanding the strengths of the summer market could make a big difference.
For buyers, summer can bring more fresh listings and better odds of finding a home you like. For sellers, summer seasonality may support stronger buyer activity and better pricing opportunities than later in the year.
If you’re planning a move in 2026, connect with a local real estate professional to talk through your goals, timeline, and market conditions. Depending on what matters most to you, summer could be the right time to make your move.
Mid-Year Housing Market Update 2026
If you’re feeling confused by the housing market right now, you’re not alone.
Mortgage rates have risen. Home sales haven’t picked up as quickly as many experts expected. And buyers and sellers are still waiting for affordability to improve and market activity to turn up.
The short answer? A lot changed during the first half of 2026.
At the end of 2025, economists were forecasting a stronger housing market for the year ahead. Many expected mortgage rates to come down, affordability to improve more noticeably, and home sales to rebound.
But lingering inflation, economic uncertainty, and growing geopolitical tensions overseas pushed mortgage rates higher than expected. With rates staying elevated for longer, many buyers have continued to wait on the sidelines.
Unexpected factors like these have forced experts to revise their housing forecasts for the rest of the year.
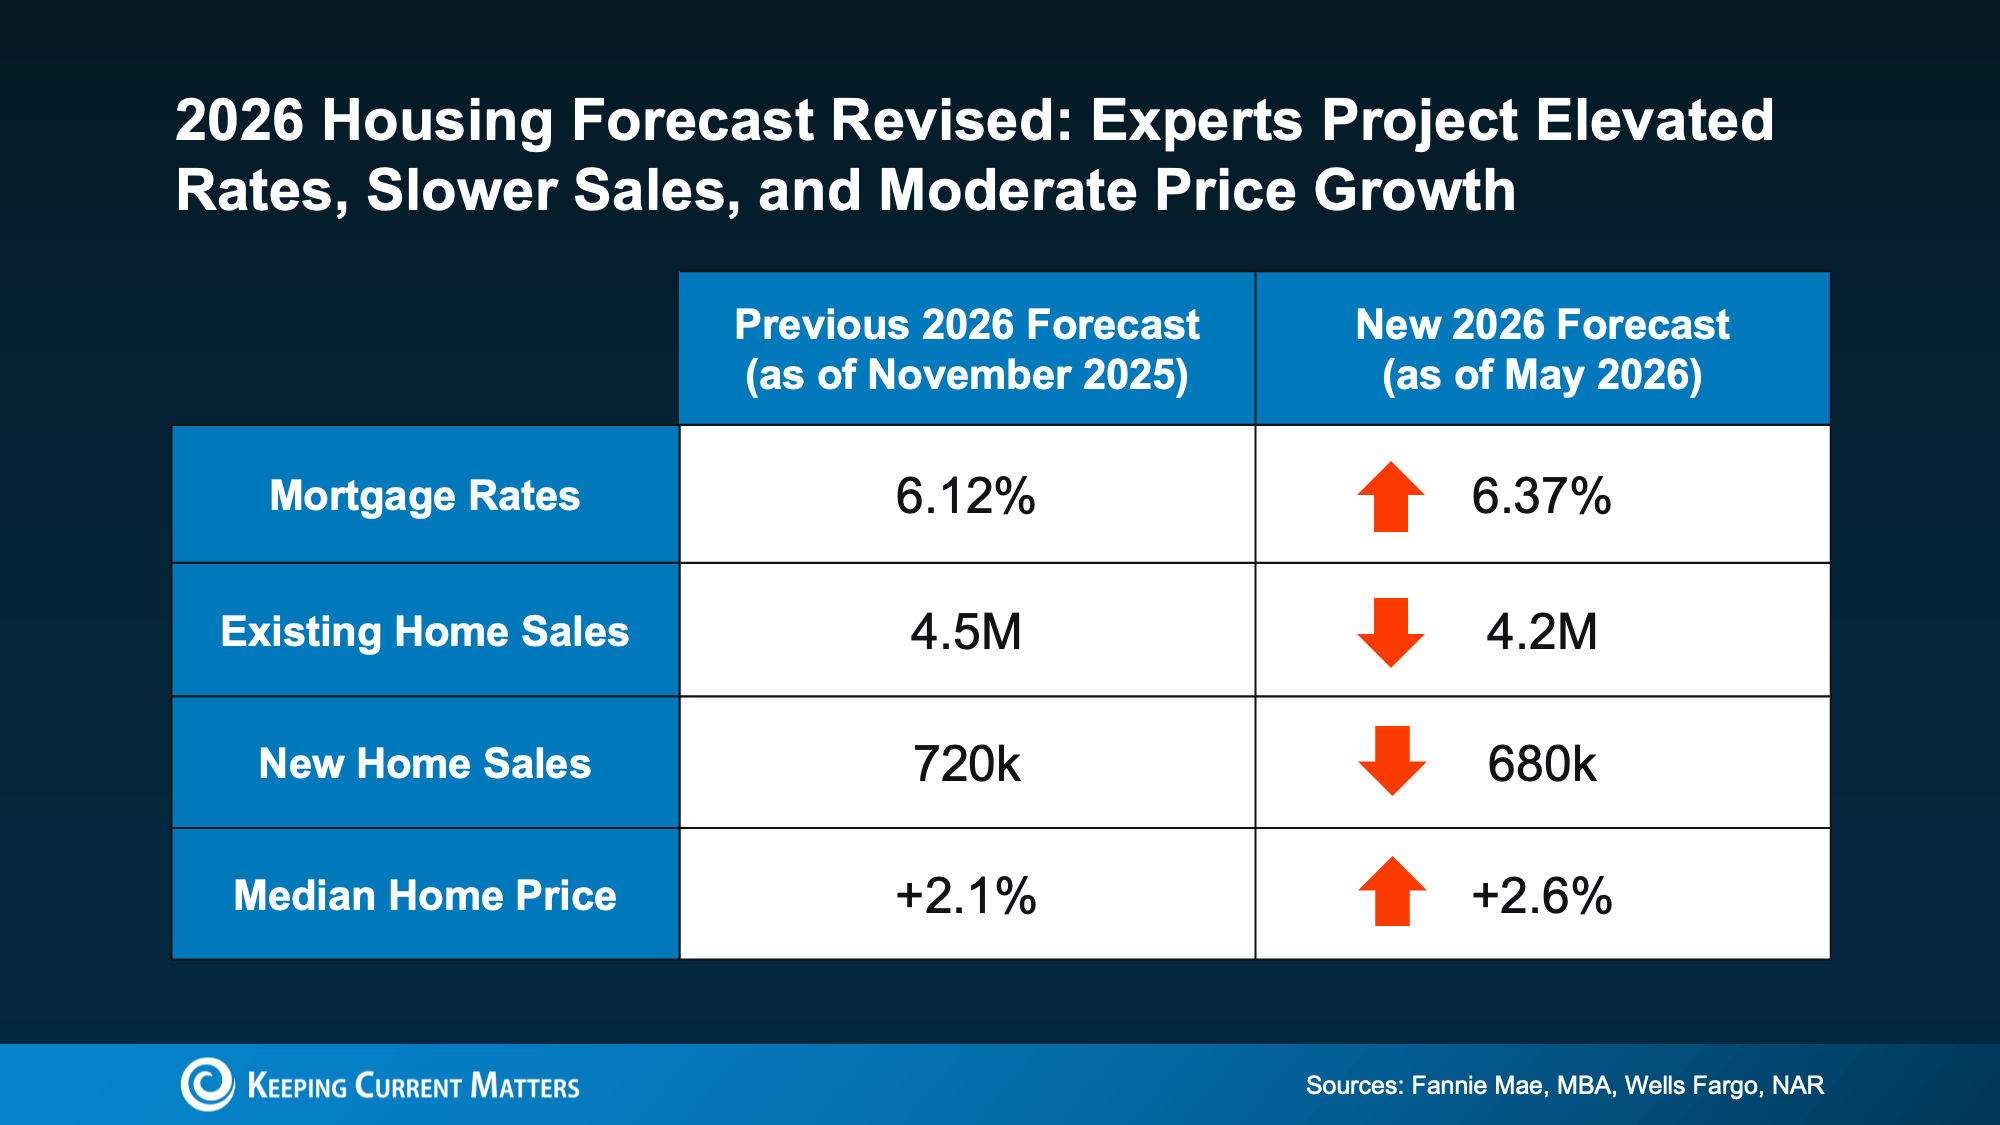
Experts are now projecting elevated mortgage rates (6.37%) and a dip in total home sales. However, home values remain resilient with a projected 2.6% growth in median prices.
So, what does this mid-year housing market update actually mean for you? Let’s break it down.
Mortgage Rates May Stay Elevated Longer Than Expected
Just about everyone would like to see mortgage rates return to the upper 5s or low 6s we saw earlier in the year. But based on current forecasts, experts don’t expect that to happen this year.
Instead, many industry organizations now expect mortgage rates to stay closer to the mid-6% range in 2026. The good news is that this is still lower than rates were a year ago.
Of course, forecasts can change. If inflation cools or overseas conflicts ease, mortgage rates could shift again. But for buyers waiting for a major rate drop, the payoff may not be as big or as immediate as hoped.
For many buyers, the better question may be: Can you comfortably afford a home at today’s rate? If the answer is yes, waiting may not automatically put you in a stronger position.
Existing Home Sales Were Revised Lower
At the end of 2025, experts expected existing home sales to average around 4.5 million in 2026. That forecast has now been revised down to about 4.2 million.
That change tells us something important: affordability is still a challenge, and many buyers remain hesitant.
Higher mortgage rates have made monthly payments harder to manage, especially for first-time buyers. As a result, the market has moved more slowly than originally expected.
But there is still some positive news. Even with the revised forecast, experts still expect more homes to sell this year than last year.
There’s also a pool of buyers who may re-enter the market once rates settle and uncertainty eases. As Lawrence Yun, Chief Economist at NAR, explains:
“There is sizable pent-up demand that could be released into the market.”
Recent improvements in pending home sales also suggest some buyers are starting to move forward again, even with rates still elevated.
For today’s buyers, that’s a big deal. If you can afford a home now, buying before more buyers return could mean less competition than you might face later.
New Home Sales Also Slowed
Builders also expected a stronger year.
Earlier forecasts projected new home sales would top 700,000 in 2026. Now, economists expect new home sales to come in just under that number.
Once again, mortgage rates are a major reason why.
But for buyers, there may be an upside. When new home sales slow, builders may become more motivated to sell available inventory. Depending on the market, that could create opportunities for:
- Builder incentives
- Closing cost assistance
- Price flexibility
- Negotiation on upgrades or finishes
This doesn’t mean every builder will negotiate, and incentives vary by location. But in areas with more new construction, buyers may have more leverage than they would in a a more active market.
Home Prices Are Still Expected To Rise
Here’s one of the biggest takeaways from this mid-year housing market update: even though sales activity has slowed, experts did not revise national home price forecasts downward.
They still expect home prices to rise nationally this year.
Why? Because buyer demand has softened, but the overall number of homes for sale remains relatively limited. That imbalance continues to support prices, even in a slower market.
Local conditions can vary; some markets are cooling more than others, and pricing trends depend heavily on inventory, buyer demand, property condition, and location.
Still, experts are projecting steady price growth rather than a major decline, at least at the national level.
That can be reassuring whether you’re buying or selling. Sellers generally don’t want to see a sharp drop in values. And buyers may feel more confident about a major purchase when prices aren’t expected to fall significantly right away.
What This Means for Buyers
For buyers, the updated 2026 housing market forecast is a reminder to focus on what you can control.
Mortgage rates may not fall as quickly as hoped, but that doesn’t mean buying is off the table. A local real estate agent can help you understand what’s happening in your specific market, including inventory levels, price trends, and negotiation opportunities.
Before making a move, think about reviewing:
- Your current budget
- Estimated monthly payment at today’s rates
- Available homes in your preferred price range
- Local competition from other buyers
- New construction options and possible builder incentives
You should also speak with a trusted mortgage professional to understand loan options, rate scenarios, and affordability based on your situation.
What This Means for Sellers
For sellers, slower sales activity doesn’t point to a stalled market.
Buyers are still active, but many are more selective thanks to tighter affordability. That makes pricing, preparation, and marketing even more important.
A strong selling strategy should include:
- A realistic pricing plan based on current local data
- Thoughtful preparation before listing
- Professional marketing that highlights the home clearly
- Flexibility around buyer questions, timelines, and negotiations
With home prices still expected to rise nationally, many sellers may still be in a strong position. A successful sale will depend on understanding your local market, not relying on broader national headlines.
Bottom Line
The housing market hasn’t rebounded as quickly as experts originally hoped. Still, the market hasn’t totally stalled.
Higher inflation, economic uncertainty, and global tensions caused economists to revise their 2026 housing market forecasts. Mortgage rates are expected to remain higher than originally projected, and home sales forecasts have been adjusted lower.
Even so, more homes are still expected to sell this year than last year, and national home prices are still projected to rise.
The key is to make decisions based on your own local market, budget, and goals.
If you want to understand what this mid-year housing market update means for your next move, connect with our team. We can help you review local trends, explore your options, and decide what makes sense for the rest of 2026.
Housing Affordability Today: What Buyers Should Know
Let’s talk honestly about housing affordability today.
If you’ve been thinking about buying a home, selling your current home, or making a move, you’ve probably seen plenty of headlines about mortgage rates, home prices, inflation, and affordability. Some of those headlines are helpful. Others leave out critical information.
The truth is, affordability is not shaped by one factor alone. Mortgage rates matter, but they’re not the only piece of the puzzle. Wages, home prices, inventory, buyer competition, and your personal financial situation all play a role.
Here’s a clearer look at what’s happening right now: the good, the challenging, and what it could mean for your next move.
Mortgage Rates Have Been Rising
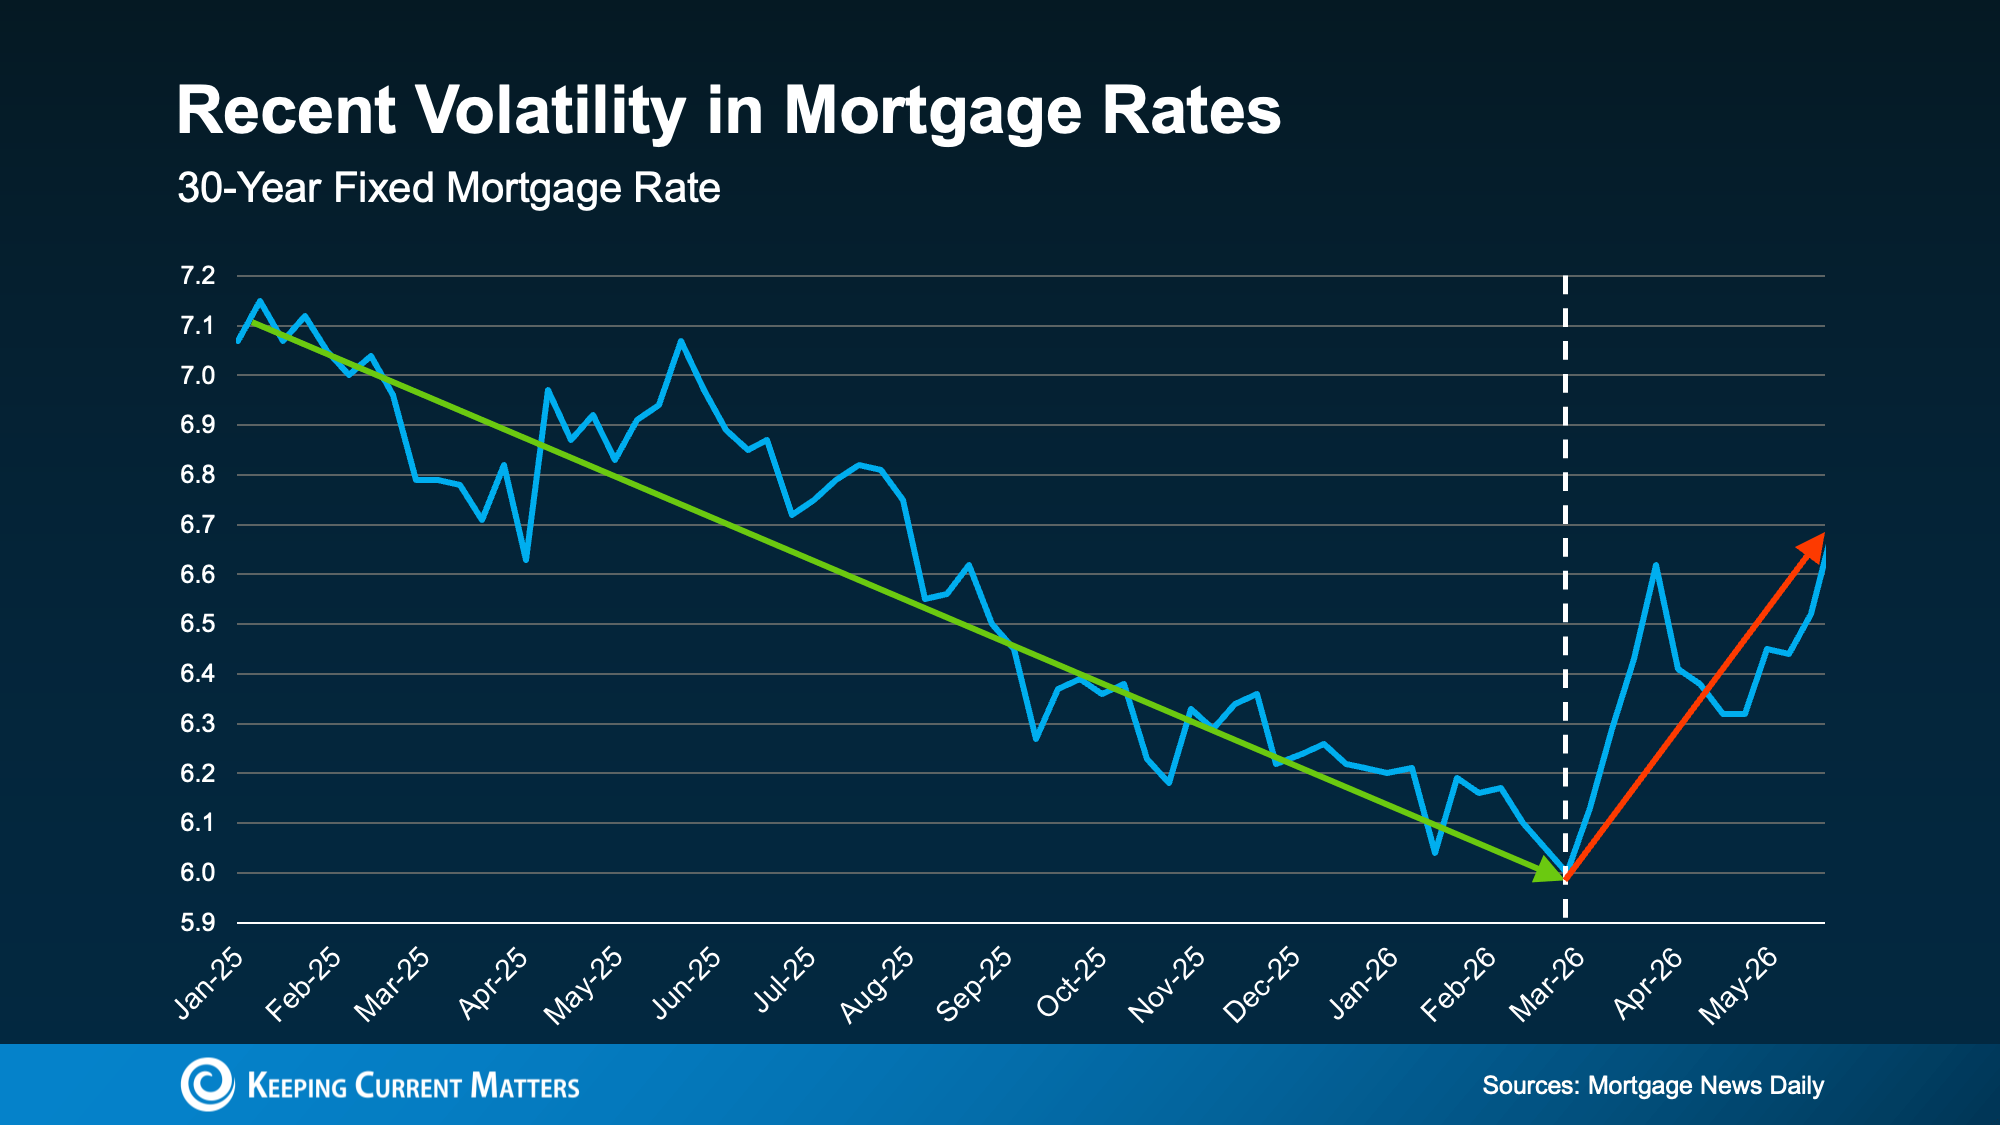
After a year or more of mortgage rates trending down, they’ve started climbing again. And for buyers, that’s incredibly frustrating.
So, why are rates moving higher?
A big reason is uncertainty. Mortgage rates are heavily influenced by broader economic conditions, and uncertainty often puts upward pressure on rates.
Ongoing global uncertainty, continued tensions in the Middle East, and inflation that has not fully cooled off are all having an impact. Colin Robertson, Founder of The Truth About Mortgage, explained it this way:
“You can’t have $100 a barrel oil and not expect inflation to rise, which translates to higher bond yields and mortgage rates.”
That matters because higher bond yields often lead to higher mortgage rates. And when mortgage rates rise, monthly payments can become more difficult for buyers to manage. Recent data from Mortgage News Daily illustrates the effect this has:
Should Buyers Wait for Mortgage Rates To Fall?
With unpredictable rates, it’s natural to wonder if waiting is the safer move.
If rates are higher now, will they come back down once uncertainty eases? Possibly. But there’s no guaranteed timeline.
Rates aren’t likely to drop until inflation cools further and global uncertainty improves. Even then, many experts believe rates may not drop dramatically. They may return to somewhere in the low- to mid-6% range we were seeing earlier this year.
That means waiting for a major rate drop could keep buyers on the sidelines longer than expected.
For many buyers, the question isn’t, “Will rates fall?”, but:
Can I afford the home and monthly payment based on today’s numbers?
If the answer is yes, and you find a home that fits your needs and budget, buying may still be worth considering. No one can predict exactly when rates will fall, how far they’ll fall, or what home prices and competition will look like when they do.
Wages Are Outpacing Home Prices
On the bright side, there’s also some encouraging news that doesn’t always make the headlines.
While inflation has made many parts of everyday life more expensive, recent data from the Federal Reserve Bank of Atlanta and Redfin show wages have been growing faster than home prices.
According to the data:
- Wages have recently been increasing around 4% year-over-year.
- Home price growth has been closer to 2% year-over-year.
That difference matters for home affordability.
When wages rise faster than home prices, buyers may slowly regain some purchasing power. It doesn’t solve the affordability challenge overnight, but it can help make a home purchase more manageable over time.
For buyers, every little bit of financial breathing room helps.
Existing Home Prices Have Held Steady
Another important part of the affordability picture is home prices.
National Association of Realtors data from the past four years show existing home prices have remained relatively steady. There hasn’t been a dramatic runup, but there hasn’t been a crash either. Instead, the market has seen more stability and slower growth.
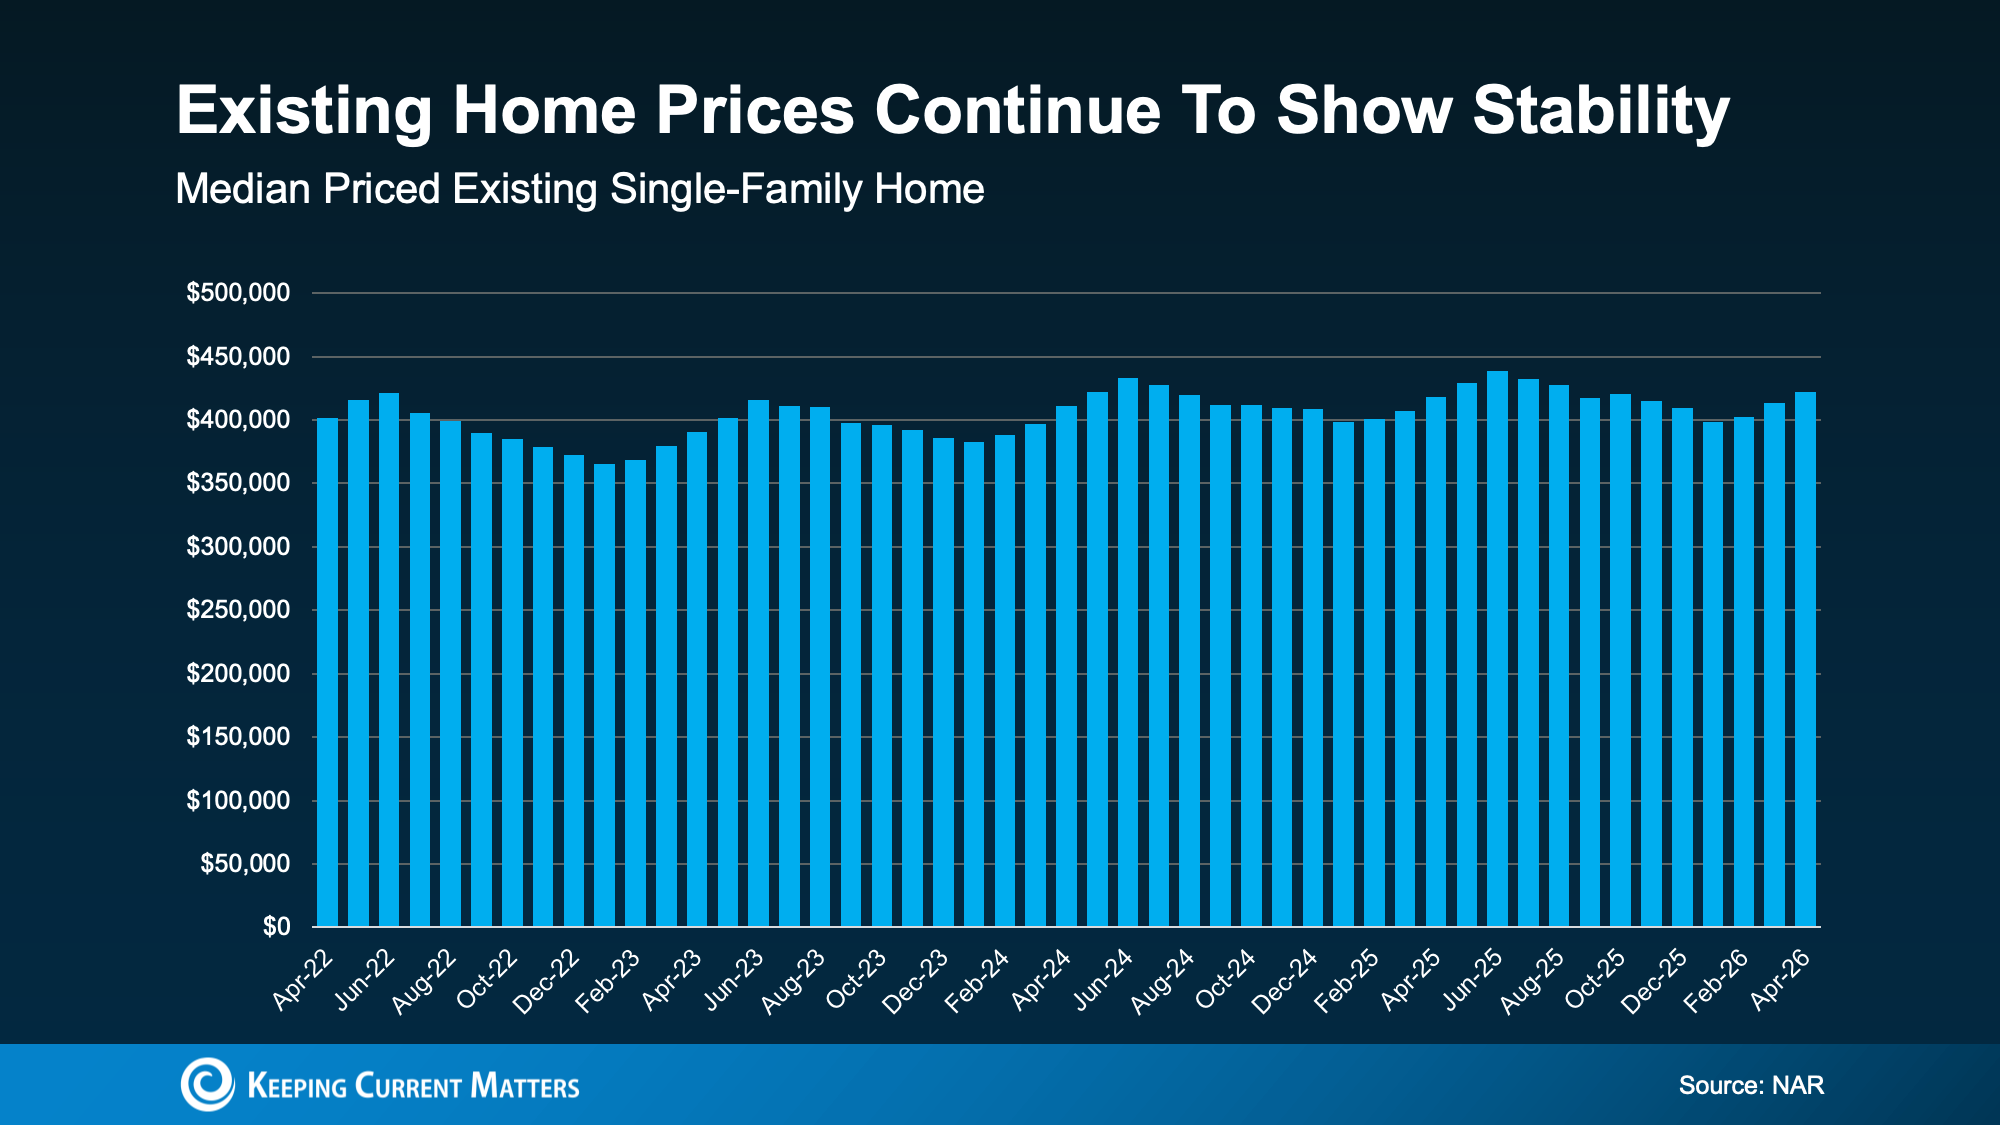
Price stability like this can give buyers a real helping hand.
Part of what’s keeping prices steadier is that buyers now have more choices than they did in the most competitive parts of the market. More inventory can create:
- Less intense competition
- More time to make decisions
- Better opportunities to compare homes
- More room for negotiation in some situations
Of course, this doesn’t mean every market is a buyer’s paradise. Local conditions always matter. But, having more options can help buyers find a home that better fits their lifestyle and budget.
What Housing Affordability Means for Your Move
Today’s housing market is not simple. Mortgage rates are higher than many buyers hoped they would be, and global uncertainty is keeping rates from settling down quickly.
But the full affordability picture is more balanced than the headlines may suggest.
Rates are still a challenge, but wages are growing faster than home prices, and existing home prices have stayed relatively steady. Buyers today might have more options to make stronger decisions than they did when the market was tighter and more competitive.
As always, the right move depends on your budget, goals, timeline, and local market.
Before deciding whether to buy now or wait, it’s worth running the numbers with today’s information. Not with guesses from last year, last month, or national headlines.
Bottom Line
Housing affordability today is about more than just mortgage rates.
Rates are still a major factor, but wages, home prices, inventory, and local market conditions all matter too. If you can afford the monthly payment and find a home that fit your needs, you may not have to wait for the “perfect” option.
Want to figure out the best move for your situation? Connect with a local real estate professional to review current homes, pricing, and your area’s unique market conditions.
VA Home Loan Benefits All Veterans Should Know
Almost half of Veterans (49%) feel homeownership is beyond their reach, according to a recent NewDay USA survey.
But many Veterans could be closer to buying a home than they think.
VA home loan benefits have been available for more than 80 years, but a lot of confusion remains about what’s actually covered. Some buyers assume they’ll need an impossibly large down payment. Others believe they’ll have high closing costs or monthly private mortgage insurance (PMI).
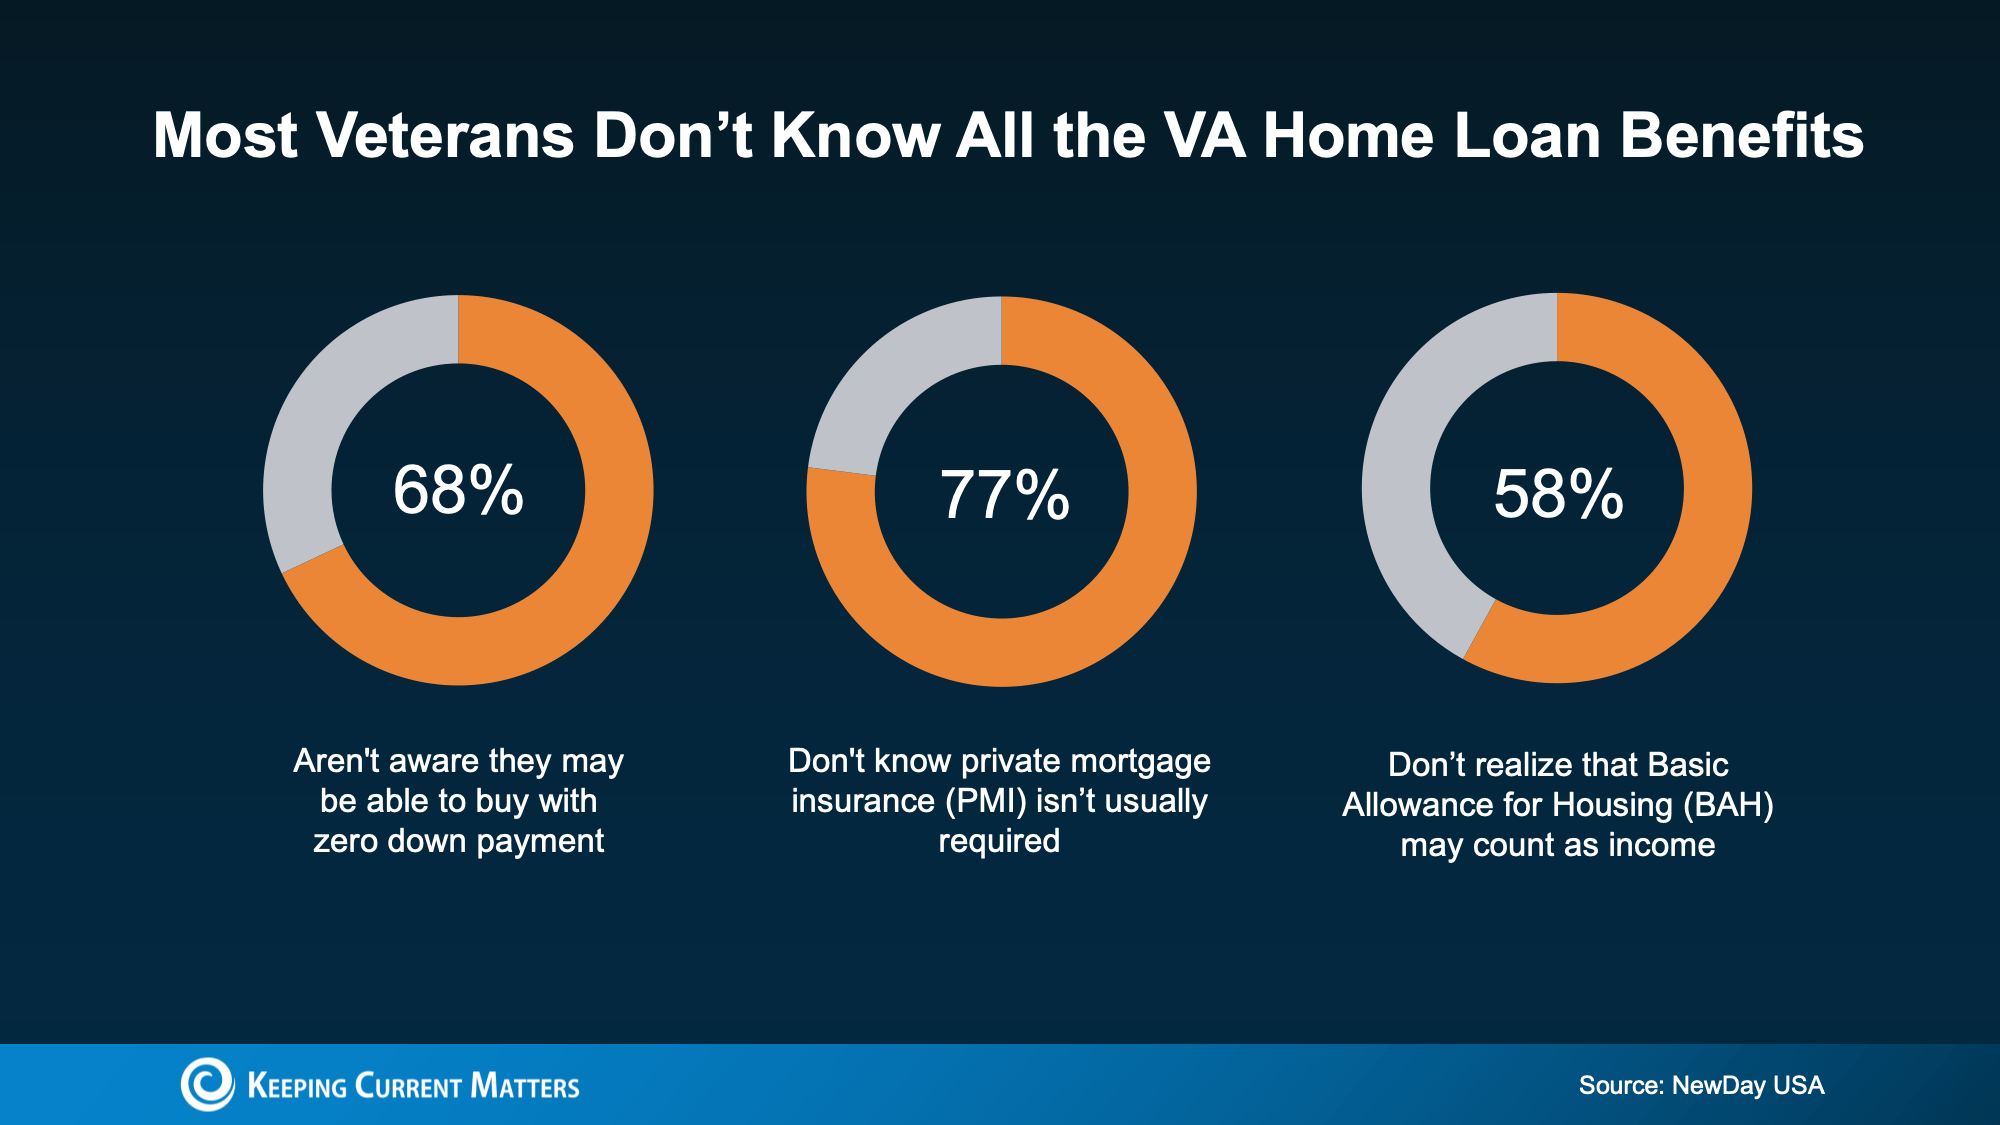
Misunderstandings like these can make homeownership feel farther away than it may really be.
VA Home Loan Benefits Many Veterans Overlook
A VA loan can offer several advantages for eligible buyers. While every buyer’s situation is different, these benefits may help reduce some of the upfront and monthly costs that often make buying a home feel financially overwhelming.
Let’s walk through a few of the biggest misconceptions.
You May Not Need a Down Payment
One of the most valuable VA home loan benefits is the potential to buy with zero money down.
That surprises many buyers. According to the NewDay USA survey, many respondents thought they would need to save between $10,000 and $19,900 before purchasing a home.
For some buyers, that kind of savings goal can take years. But with a VA loan, a large down payment isn’t always necessary. That can make the path to homeownership feel much more realistic for eligible Veterans and service members.
You May Have Lower Closing Costs
Closing costs are another area where VA loans can make a big difference.
According to the Department of Veterans Affairs, VA loans can include limits on the types of closing costs buyers are required to pay. That may help eligible buyers keep more money in their pocket on closing day.
When combined with the potential for no down payment, this benefit can lower the amount you need to save up before buying a home.
Your Monthly PMI Cost Could Be $0
Many loan programs require private mortgage insurance, commonly called PMI, when a buyer puts less than 20% down.
VA loans typically do not require monthly PMI, even when buyers use low or no money down.
That can make a meaningful difference in your monthly housing costs. If you use a conventional loan instead, you could pay $100 to $300 per month in PMI until you reach 20% equity, according to NewDay USA.
Over time, avoiding that monthly cost could add up to thousands of dollars.
Your BAH and BAS May Help You Qualify
For active-duty service members and qualifying reservists, Basic Allowance for Housing (BAH) and Basic Allowance for Subsistence (BAS) may count toward income qualification on a VA loan.
Since both BAH and BAS are non-taxable, they can help increase the amount you can qualify for. A trusted lender can help review your full financial picture and explain how these allowances might apply to your situation.
Why This Matters for Veterans and Service Members
If you have been assuming homeownership is out of reach, it may be worth taking a closer look at your VA home loan benefit.
A VA loan may help eligible buyers by offering:
- The potential for no down payment
- Limits on certain closing costs
- No monthly PMI in many cases
- The ability to include qualifying BAH and BAS income
These benefits don’t guarantee approval, and every buyer’s situation is different. But they may help remove some of the common barriers that keep Veterans and service members from exploring homeownership.
Bottom Line
VA home loan benefits can be a powerful tool for eligible Veterans, active-duty service members, and qualifying reservists.
If you’ve served, are currently serving, or know someone who has, connect with a trusted lender who understands VA loans. They can help you review your options, understand what you may qualify for, and decide whether buying a home makes sense for your goals.
New Home Prices Hit a 5-Year Low
If you’ve assumed a newly built home is out of reach, it may be time to take another look.
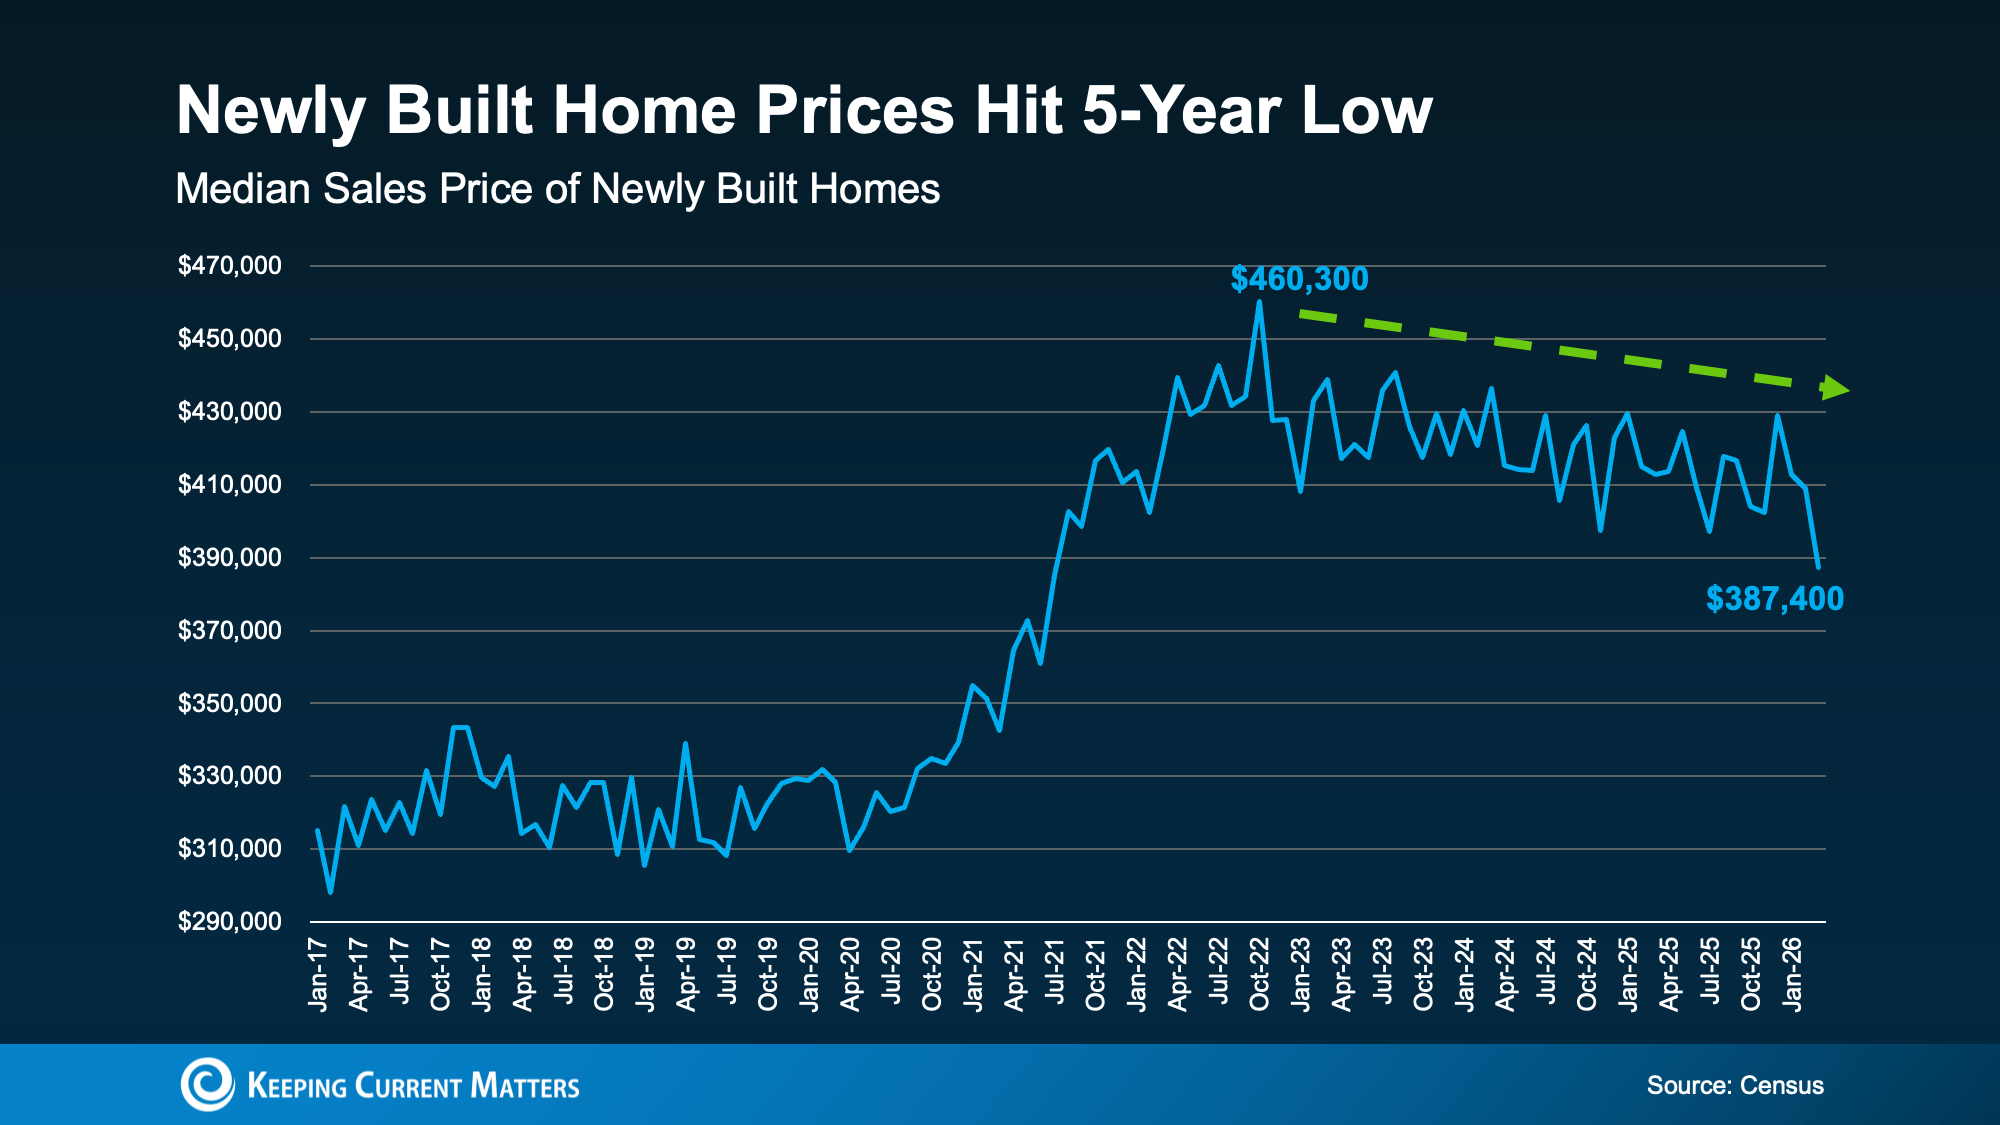
The median sale price of a newly built home has dropped to its lowest level since 2021, according to the latest United States Census Bureau data. At the same time, many builders are still offering incentives to help attract buyers.
New Home Prices Have Come Down
After climbing sharply during the pandemic years, new home prices have eased. The median sale price of a newly built home is now around $390,000, which is the lowest level in nearly five years.
Local markets can vary, but the national trend may work in buyers’ favor, especially in the entry-level price range. According to Zonda, prices in the entry-level new construction segment have dropped about 2.7% over the past 12 months, which is more than any other price tier.
This doesn’t mean every newly built home is suddenly affordable now. But, it does mean that buyers may be seeing some of the best new construction pricing since 2021.
Why Lower New Home Prices Do Not Mean a 2008 Repeat
Lower prices can make some buyers wonder whether the new home market is in trouble. But today’s conditions are very different from 2008.
Builders are being more intentional about how much inventory they bring to market. Instead of letting homes pile up, many are using pricing adjustments and incentives to keep inventory moving.
It’s also important to keep perspective. Even with recent price improvements, new home prices are still higher than pre-pandemic norms. This isn’t a market crash. It’s a builder strategy designed to match today’s buyer demand.
Builders Are Still Offering Buyer Incentives
Lower prices aren’t the only potential advantage for buyers. According to the National Association of Home Builders (NAHB), 60% of builders are currently offering some form of incentive to attract buyers.
Common builder incentives include:
- Closing cost assistance: Some builders may help cover upfront costs, which can reduce the cash buyers need at closing.
- Upgrade packages: Builders might include premium finishes, appliance packages, or design features at no additional cost.
- Mortgage rate buydowns: Some builders might pay to reduce a buyer’s mortgage rate, which can lower the monthly payment.
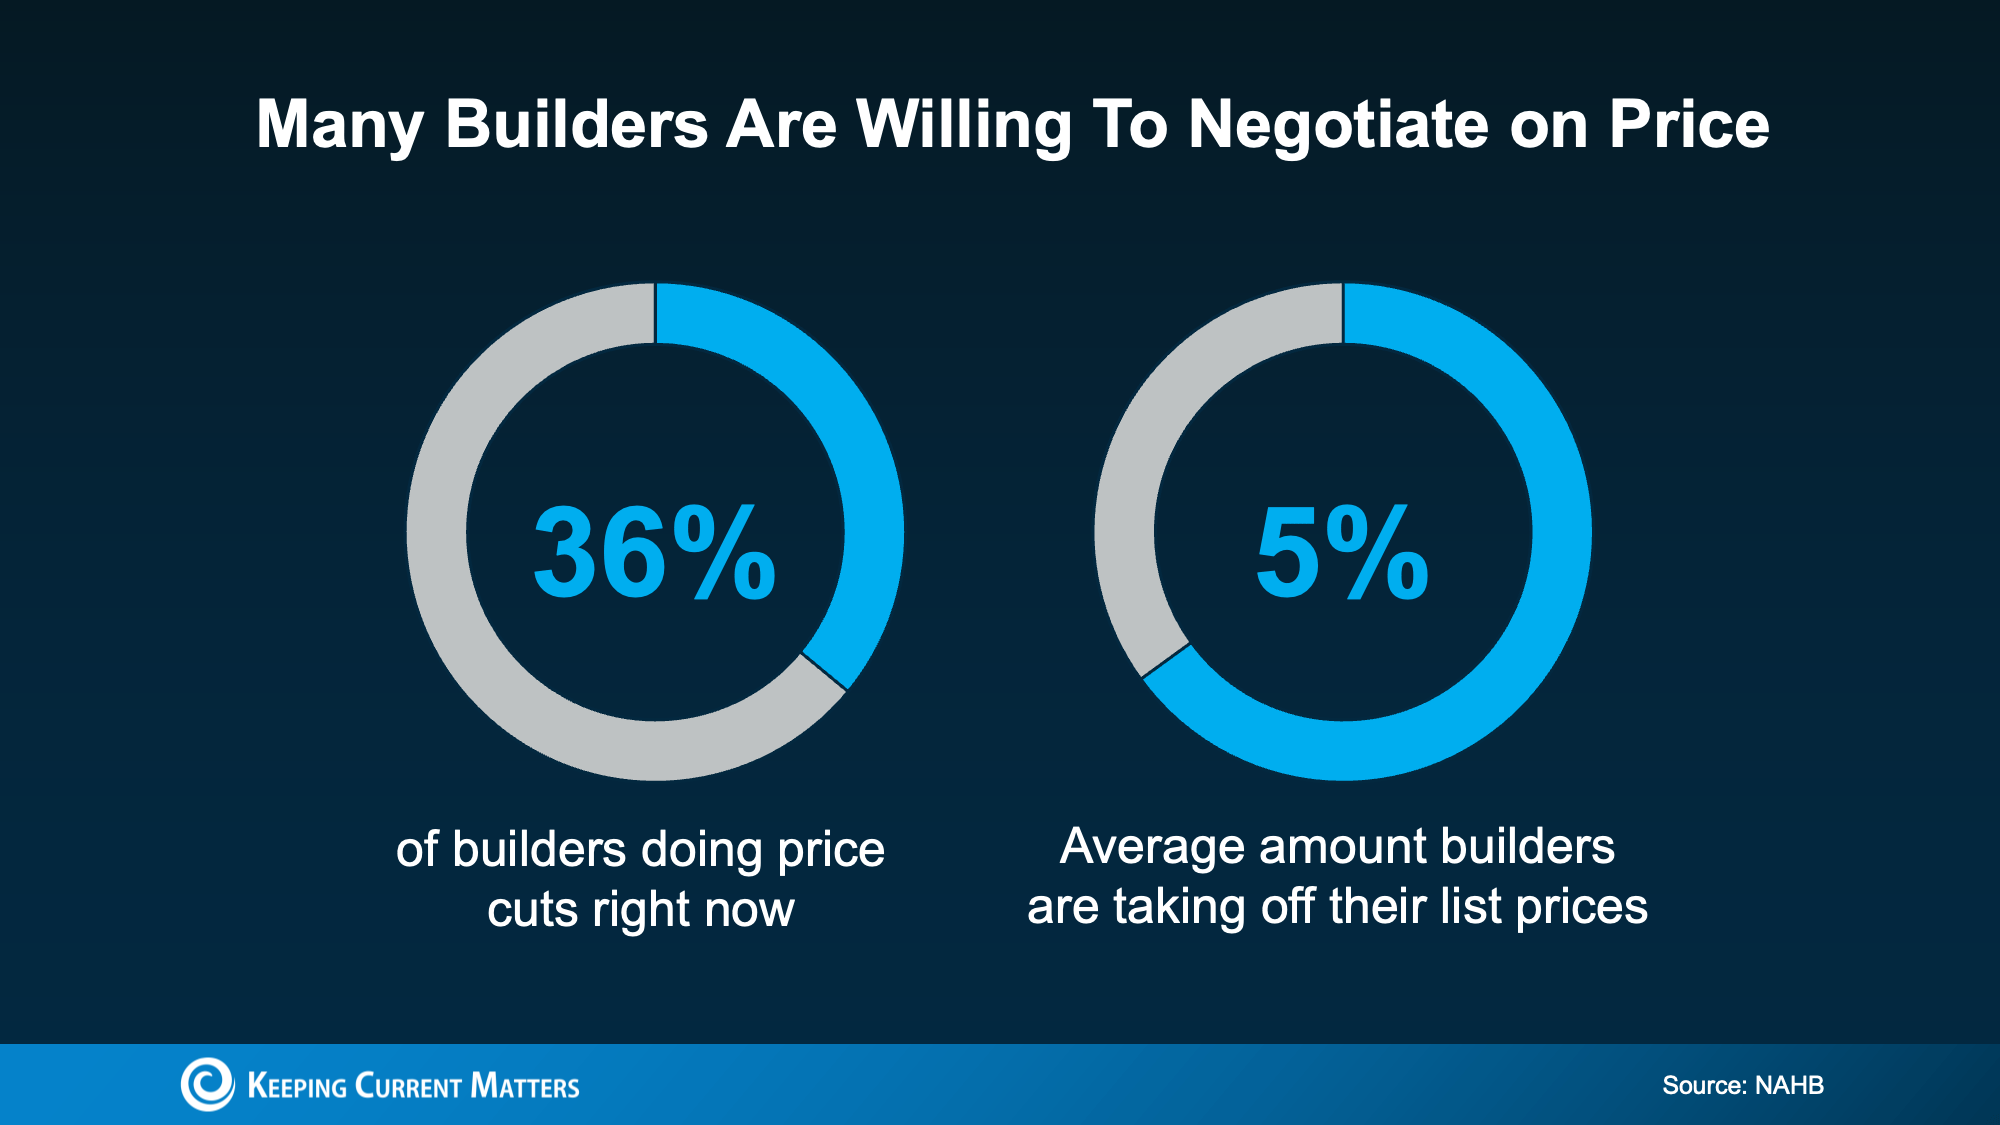
- Price cuts: More than one in three builders, or 36%, are cutting prices right now, with reductions averaging around 5% off list price.
Why Builders May Be More Flexible Than Sellers
Many buyers assume builders won’t negotiate on price. But builders often have different motivations than individual homeowners.
A homeowner may decide to take a listing off the market rather than accept a lower price. Meanwhile, builders usually need to sell the homes they’ve already built so they can keep projects moving.
As Joel Berner, Senior Economist at Realtor.com, explains:
“. . . many existing-home sellers resort to taking down their listing instead of taking less than their desired price, but builders are more motivated to sell their inventory than owner-occupants . . .”
That doesn’t mean every builder will negotiate the same way. But it does mean buyers should ask about current pricing, incentives, rate buydowns, and available inventory before assuming a new build is outside their budget.
What This Means for Home Buyers
If you’re shopping for a home, newly built homes may deserve a closer look. Between lower new home prices and ongoing builder incentives, some buyers may find opportunities they did not expect.
Before you make a decision, look at the whole picture:
- The purchase price
- Builder incentives
- Closing cost assistance
- Mortgage rate buydown options
- Included upgrades
- Monthly payment estimates
- Location, commute, and long-term housing needs
A local real estate agent can help you compare new construction homes with existing homes in your market, review builder incentives, and understand what questions to ask before you make a move.
Bottom Line
New home prices have eased, and many builders are still offering incentives to attract buyers. That could give today’s home shoppers more room to explore newly built homes than they’ve had in recent years.
If you’re curious about new construction homes in your area, connect with a local real estate professional to see what’s available and what builder incentives might be offered in your market.
Are Home Prices Going To Fall? Here’s What Buyers Should Know
One of the biggest questions buyers are asking right now is: Will home prices fall after I buy?
It’s a common concern. Buying a home is a major financial decision, and no one wants to feel like they bought too early, or too late. With headlines pointing to changing prices in some markets, it’s easy to want to play it safe by waiting.
But the short-term noise isn’t the whole story. While some local markets may see temporary dips, the bigger, long-term picture is much different: home prices historically rise over time.
What Housing Market Data Shows
When you look at long-term housing data, one trend becomes clear. Home values have generally moved upward for decades.
Yes, there have been exceptions. The housing crash of 2008 is the most dramatic example. And in some years, certain markets have seen slight declines. But outside of major disruptions, home prices have typically either held steady or increased, and data from Case-Shiller and Biello shows this.
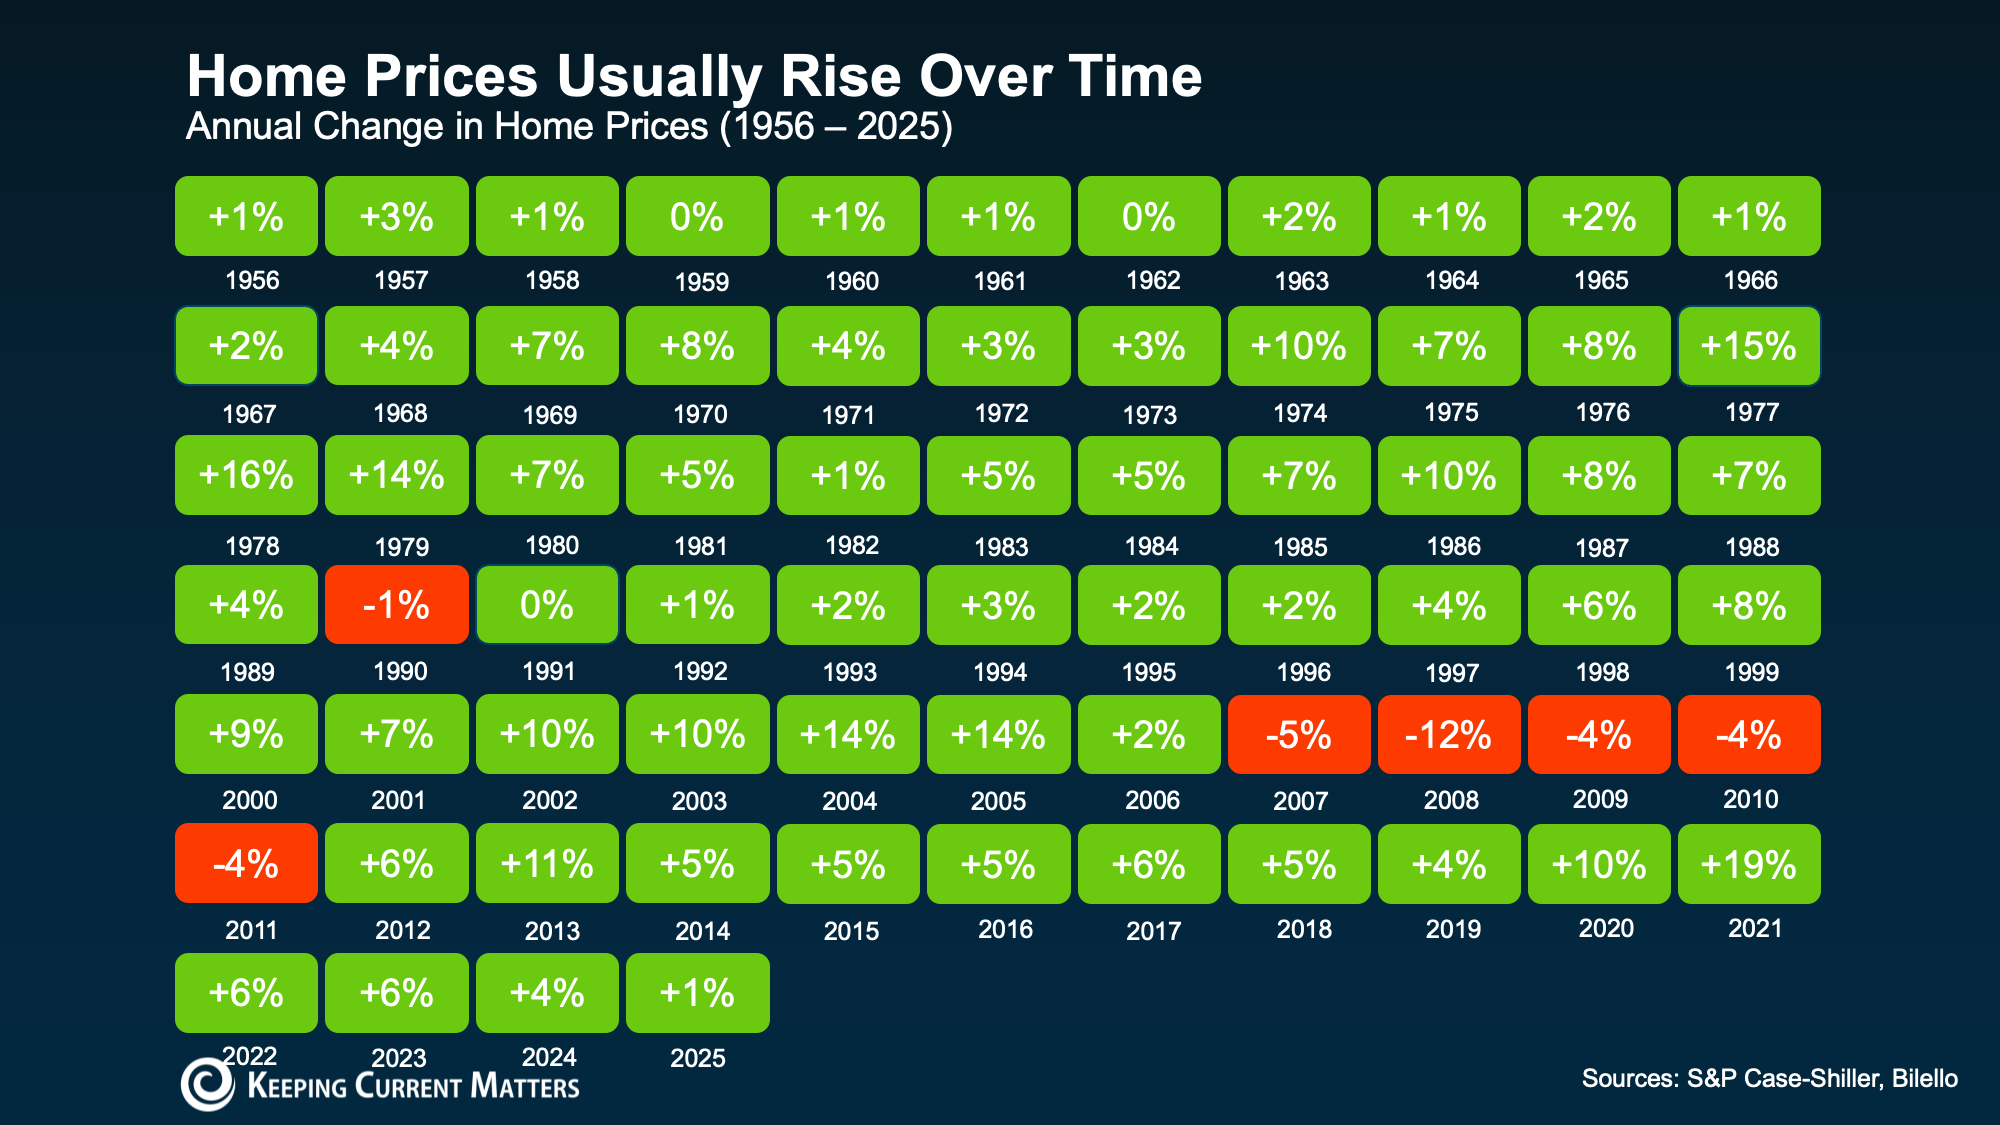
That long-term track record is important for buyers to understand. Real estate is not usually about what happens over the next few weeks or months. It’s about what happens over several years.
Short-term price drops can happen, especially in markets where inventory is rising or buyer demand has cooled. But historically, those dips have proven to be temporary.
Why Home Prices Tend To Rise Over Time
There are several consistent reasons home prices tend to increase in the long run.
People Always Need Homes
Life changes keep the housing market moving. People get married, have children, change jobs, retire, downsize, or relocate to be closer to family. No matter what the market is doing, people always need places to live.
Steady demand like this helps support home values over time.
Housing Supply Is Still Limited
Even though more homes may be available for sale than there were during the tightest years of the market, many areas are still dealing with housing shortages.
When there aren’t enough homes to meet buyer demand, prices tend to stay elevated. Even when demand slows, limited inventory helps prevent dramatic price drops in most markets.
Inflation Plays a Role
Over time, the cost of goods and services tends to rise, and housing is no exception. Land, labor, materials, and construction costs all influence home values.
As the everyday cost of living inflates, home prices naturally move higher too.
What This Means If You’re Thinking About Buying
It’s natural to worry about whether home prices will drop after you buy a home. That concern is especially common among first-time buyers trying to make a smart financial decision.
But what matters most is your own expected timeline.
If you’re planning to buy a home and stay there for several years, short-term market movements matter less. That’s because time gives your home more opportunity to appreciate in value, helping you ride out the kind of ups and downs we’re seeing in some markets.
That’s why many real estate professionals recommend buying only when you expect to stay in the home for at least five years. While there’s no guaranteed timeline, a longer-term approach often gives homeowners a better chance to benefit from rising values.
Real Estate Is Local
Another critical point to remember is that not all housing markets are the same.
Some areas may see home prices soften. Others may continue to rise because demand is strong and inventory remains low. National headlines can give you a general idea of what’s happening, but they don’t always reflect conditions in your specific city, neighborhood, or price range.
That’s why local market insight matters. A trusted real estate agent can help you understand whether prices are rising, flattening, or adjusting in your area.
Don’t Try To Time the Market Perfectly
Trying to buy at the exact bottom of the market is extremely difficult. By the time it’s clear prices have bottomed out, competition may already be increasing again.
Instead of focusing only on timing, focus on whether buying makes sense for your life, your finances, and your long-term goals.
Ask yourself:
- Can I comfortably afford the monthly mortgage payment?
- Do I plan to stay in the home for several years?
- Does buying now support my lifestyle and financial goals?
- Am I prepared for the responsibilities of homeownership?
If the answer is yes, buying may still make sense, even if prices fluctuate in the short term.
Bottom Line: Most Price Drops Are Temporary
So, are home prices going to fall? In some markets, small short-term declines are possible. Historically though, data shows home prices strongly tend to rise over time.
That’s why buying a home is often considered a long-term investment, not a short-term gamble.
You don’t have to buy before you’re ready. But if homeownership fits your goals and you plan to stay put for a while, today’s market headlines shouldn’t scare you away.
For the most reliable picture, talk with a local real estate agent who can explain what home prices are doing in your area and help you decide whether now is the right time to make a move.