Facebook
 X
 Pinterest
 Copy Link
How To Sell Your Home Fast in Any Market
When you list your house, you probably have two goals: sell for a strong price and sell your home fast. But in today’s housing market, homes are taking a little longer to move than they did during the ultra-competitive years.
But in every market, there’s one clear trend standing out:
Well-priced, well-presented homes are still attracting attention and going under contract quickly. The key is making sure your home stands out for the right reasons from the moment it hits the market.
How Long Does It Take To Sell a Home Today?
According to Realtor.com data, homes are selling in about 52 days from listing to closing. That may feel slow if you remember the days when homes seemed to sell almost overnight, but historically, that timeline is much closer to a normal market.
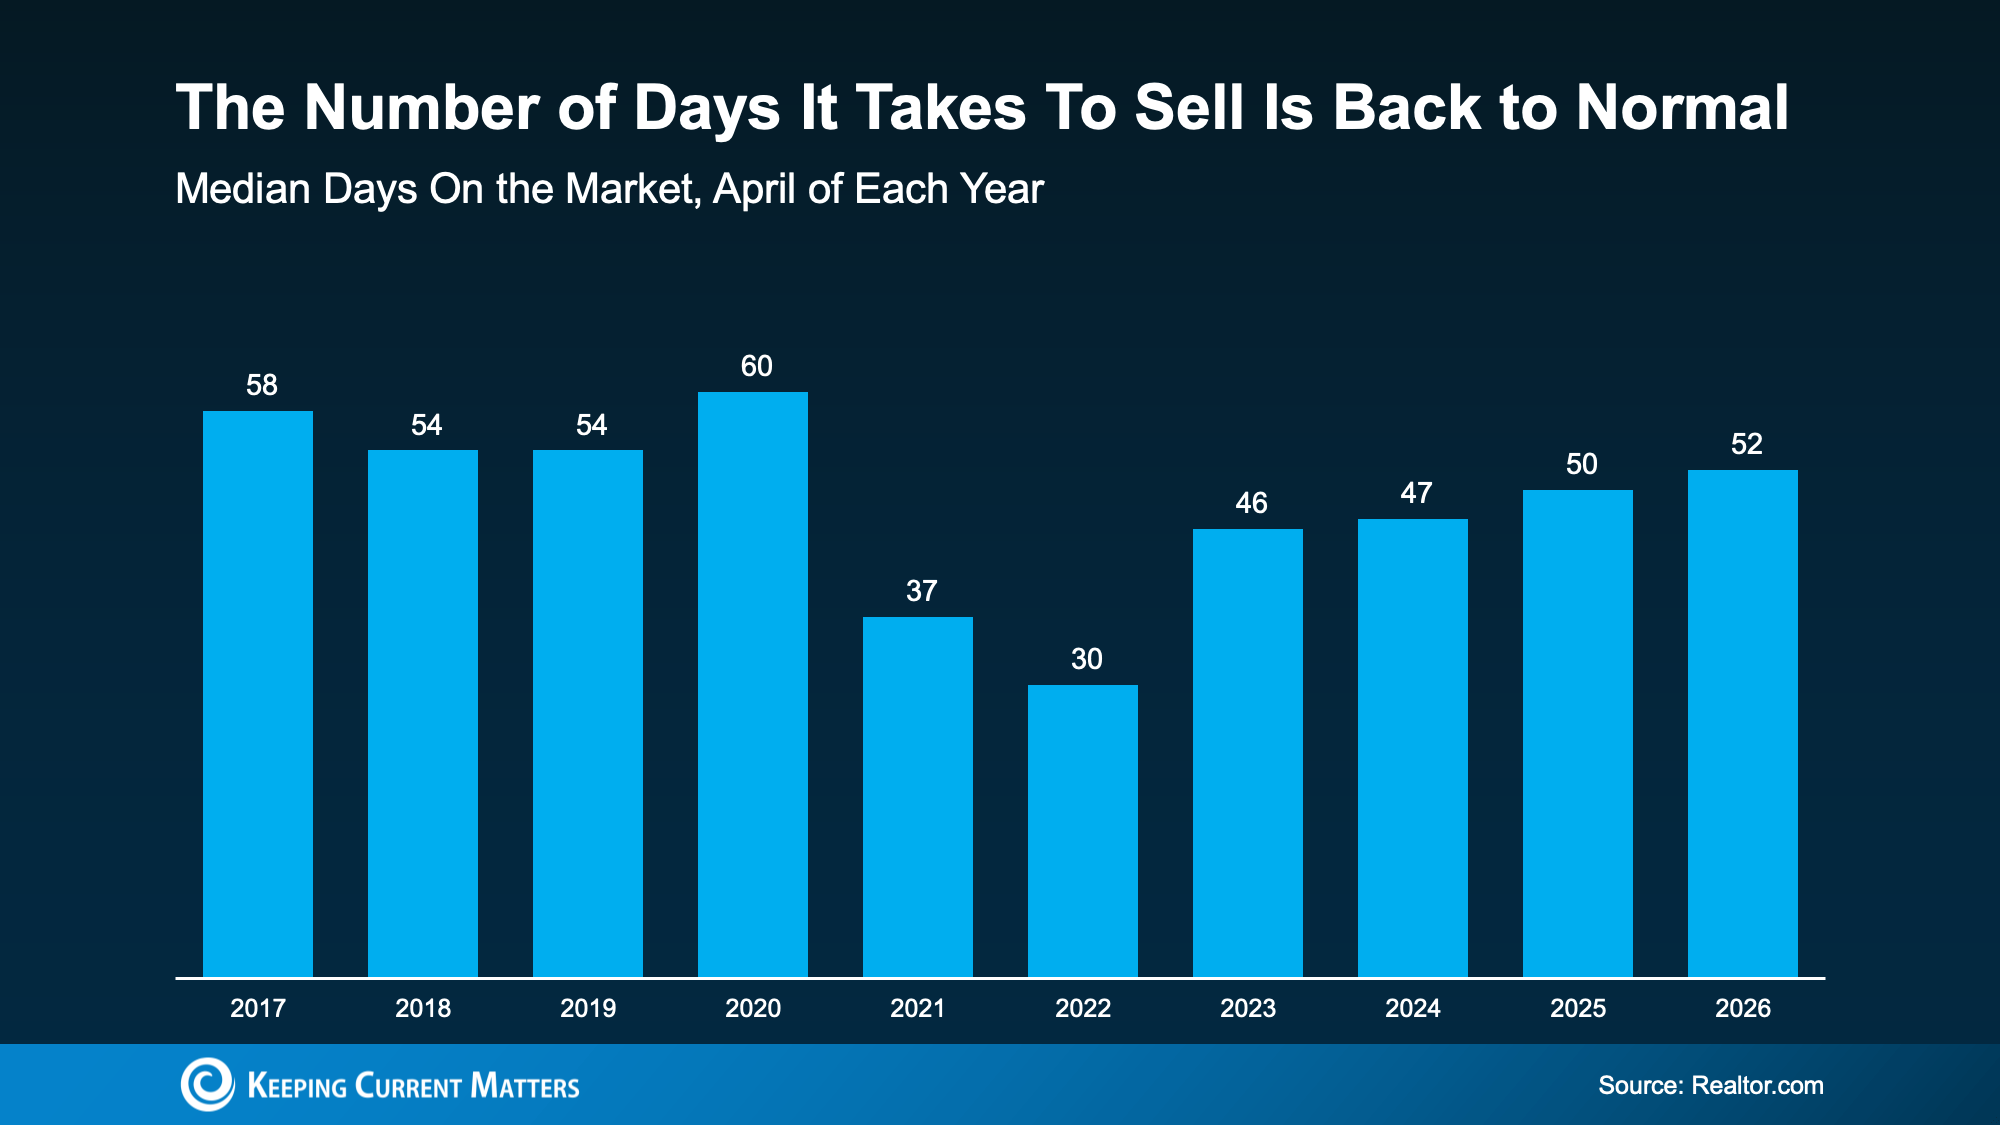
The important thing to understand is this: the market is normalizing, not stopping.
You may still receive an accepted offer much sooner than the full 52-day timeline. In fact, Zillow data says the typical home goes pending or under contract in about 19 days, and some homes move in as little as 7 days.
Why Some Homes Still Sell Quickly
If you want to sell your home fast, location can help, but it’s not the only factor. Even in slower-moving markets, some homes continue to get strong buyer interest because they are positioned correctly.
As Orphe Divounguy, Senior Economist at Zillow, says:
“The cream of the crop is still selling fast, even in markets that have slowed considerably. . .”
That’s the real takeaway. Buyers are still out there, but they’re more selective than ever. Buyers today are comparing homes carefully, looking at price, condition, photos, updates, layout, location, and overall value.
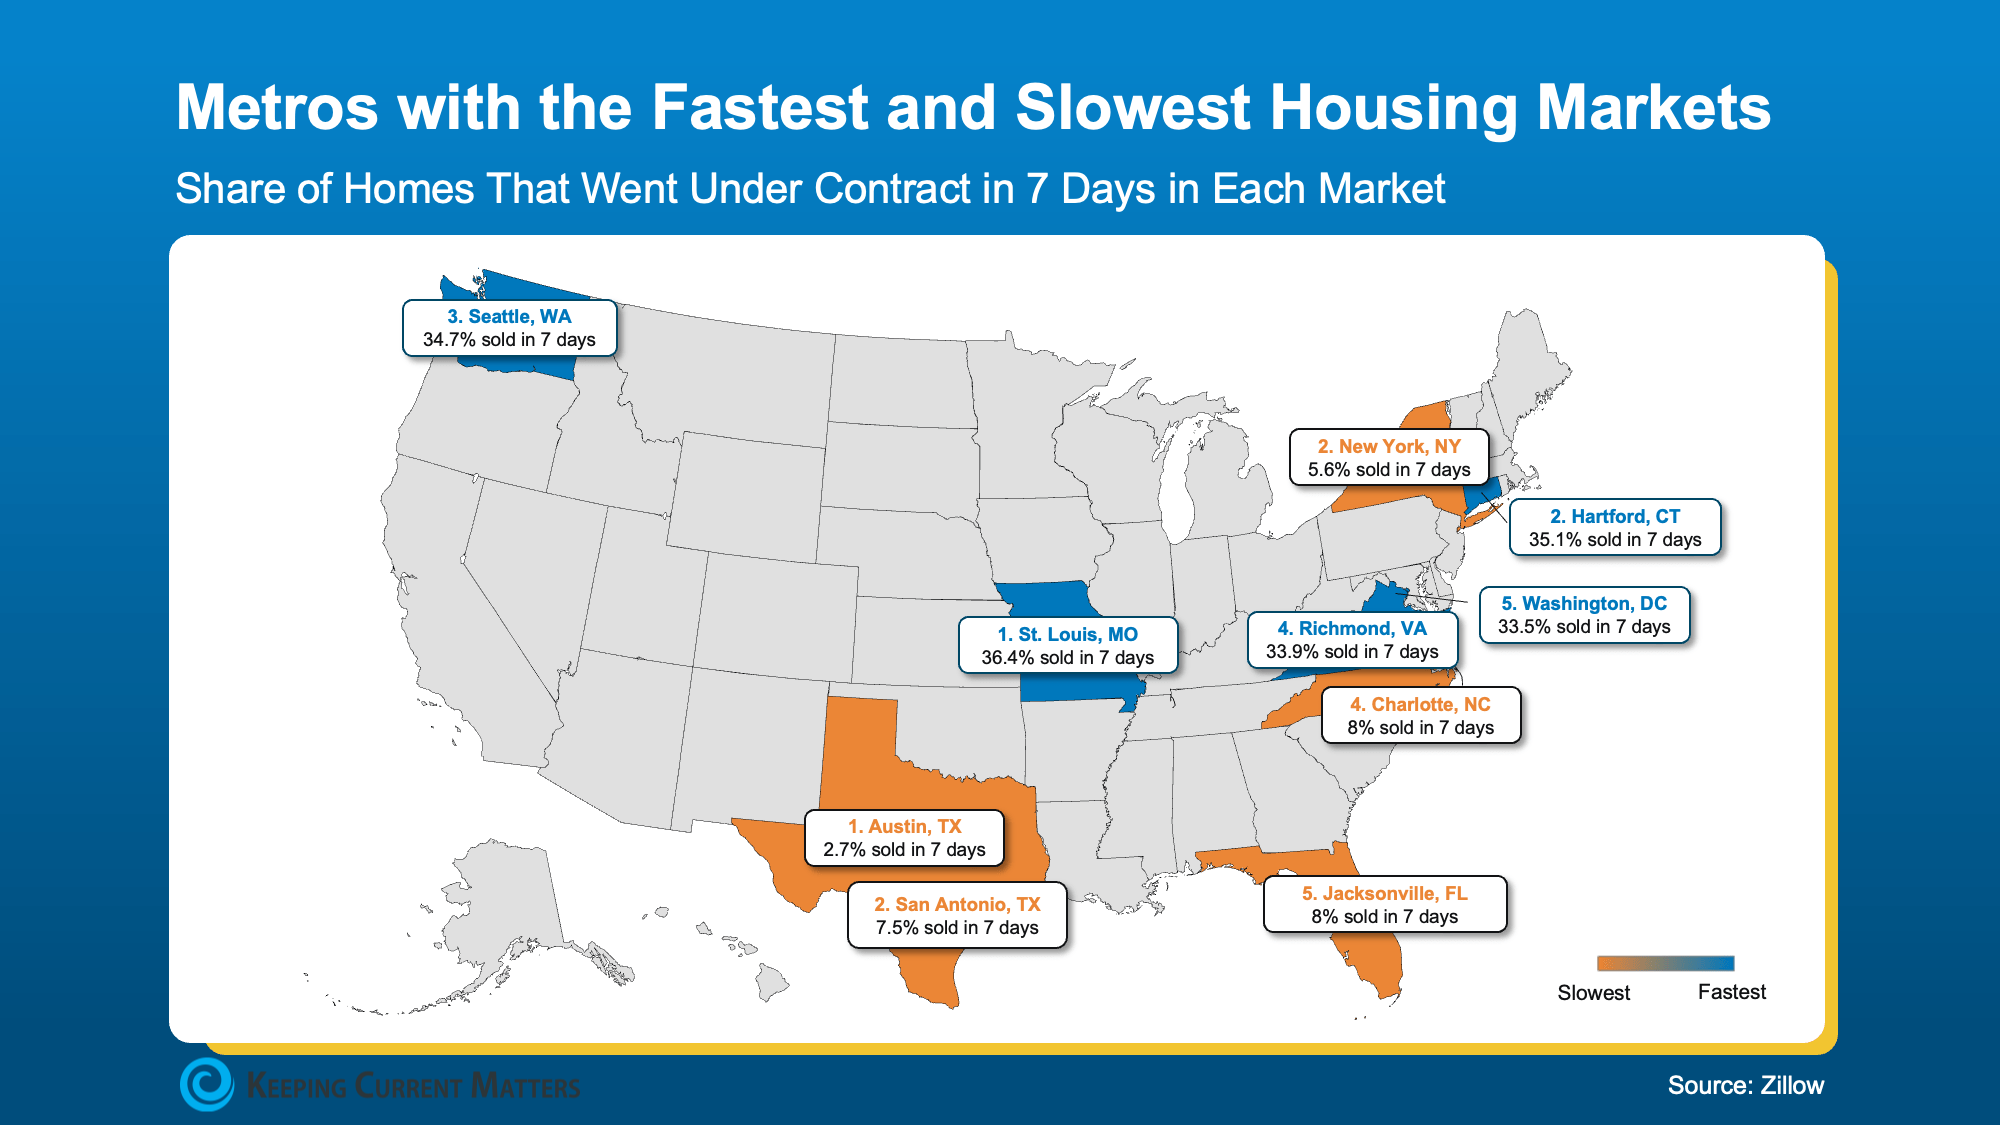
Homes that feel move-in ready and priced appropriately are the ones that tend to rise to the top, and sell the quickest.
The Biggest Reasons Some Homes Sit on the Market
In any market, homes are more likely to sit when they miss the mark on critical buyer expectations. Here are some of the most common issues buyers find:
- The home is priced too high for current market conditions.
- The property needs more work than buyers are willing to take on.
- Listing photos do not make the home look appealing.
- The home is not staged or prepared well.
- The marketing does not highlight the home’s best features.
The Wall Street Journal (WSJ) explains it this way:
“. . . some homes are still flying off the shelves. These houses are often in the Midwest or Northeast, where the lack of new construction keeps a lid on supply. Certain homes in other markets are selling quickly, too, often when a home is move-in ready.”
Move-in-ready homes often have an advantage because many buyers are already dealing with higher costs and tighter budgets. A home that feels clean, functional, and well cared is much more attractive.
How To Sell Your Home Fast
The best way to improve your odds of selling quickly is to focus on the things you can control before your home goes live.
1. Price It Strategically
Pricing too high can cause your home to sit, which can lead buyers to wonder what’s wrong with it. A local real estate agent can help you compare your home to similar listings and recent sales so you list at a price that attracts serious buyers.
2. Make a Strong First Impression
Buyers often decide whether they are interested before they ever schedule a showing. Professional photos, curb appeal, decluttering, and simple updates can make a big difference.
3. Highlight What Buyers Care About Most
Your listing should clearly show what makes your home valuable, whether it’s an updated kitchen, a flexible floor plan, a great location, outdoor space, or recent renovations made.
4. Work With a Local Market Expert
A local agent can help you understand what buyers in your area expect, how quickly homes are moving, and what changes might be needed if the market shifts after listing.
Bottom Line: Stand Out Strategically
Today’s real estate market still rewards sellers who use the right strategy. If your goal is to sell your home fast, focus on pricing realistically, preparing your home well, and working with an expert agent who understands your local market.
The homes that stand out are still selling, and sometimes even faster than sellers expect.
3 Things That Aren’t Going To Happen in Today’s Housing Market
There’s no shortage of uncertainty in today’s housing market, and that’s naturally fueling a lot of dramatic headlines. And if you’re trying to buy a home, that kind of noise can make your decision feel a lot more complicated.
In fact, a recent CNBC study asked homebuyers what they’re most concerned about, and the same three topics kept rising to the top:
- Mortgage rates
- The number of homes for sale
- Home prices
The challenge is that much of what people are hearing about these topics is driven by misconceptions, not facts. Let’s separate the headlines from what the data is really showing.
Misconception #1: “I Should Wait Because Mortgage Rates Are Going To Fall Dramatically”
One of the most common ideas circulating on social media is that mortgage rates are about to drop sharply, so waiting to buy is the smarter move.
But is that what experts are expecting?
While mortgage rates have eased a little in recent weeks, forecasts still aren’t predicting any major declines. It’s more likely that rates will stay in the low 6% range this year.
And that’s not a remarkable shift from the rates we’re seeing today:
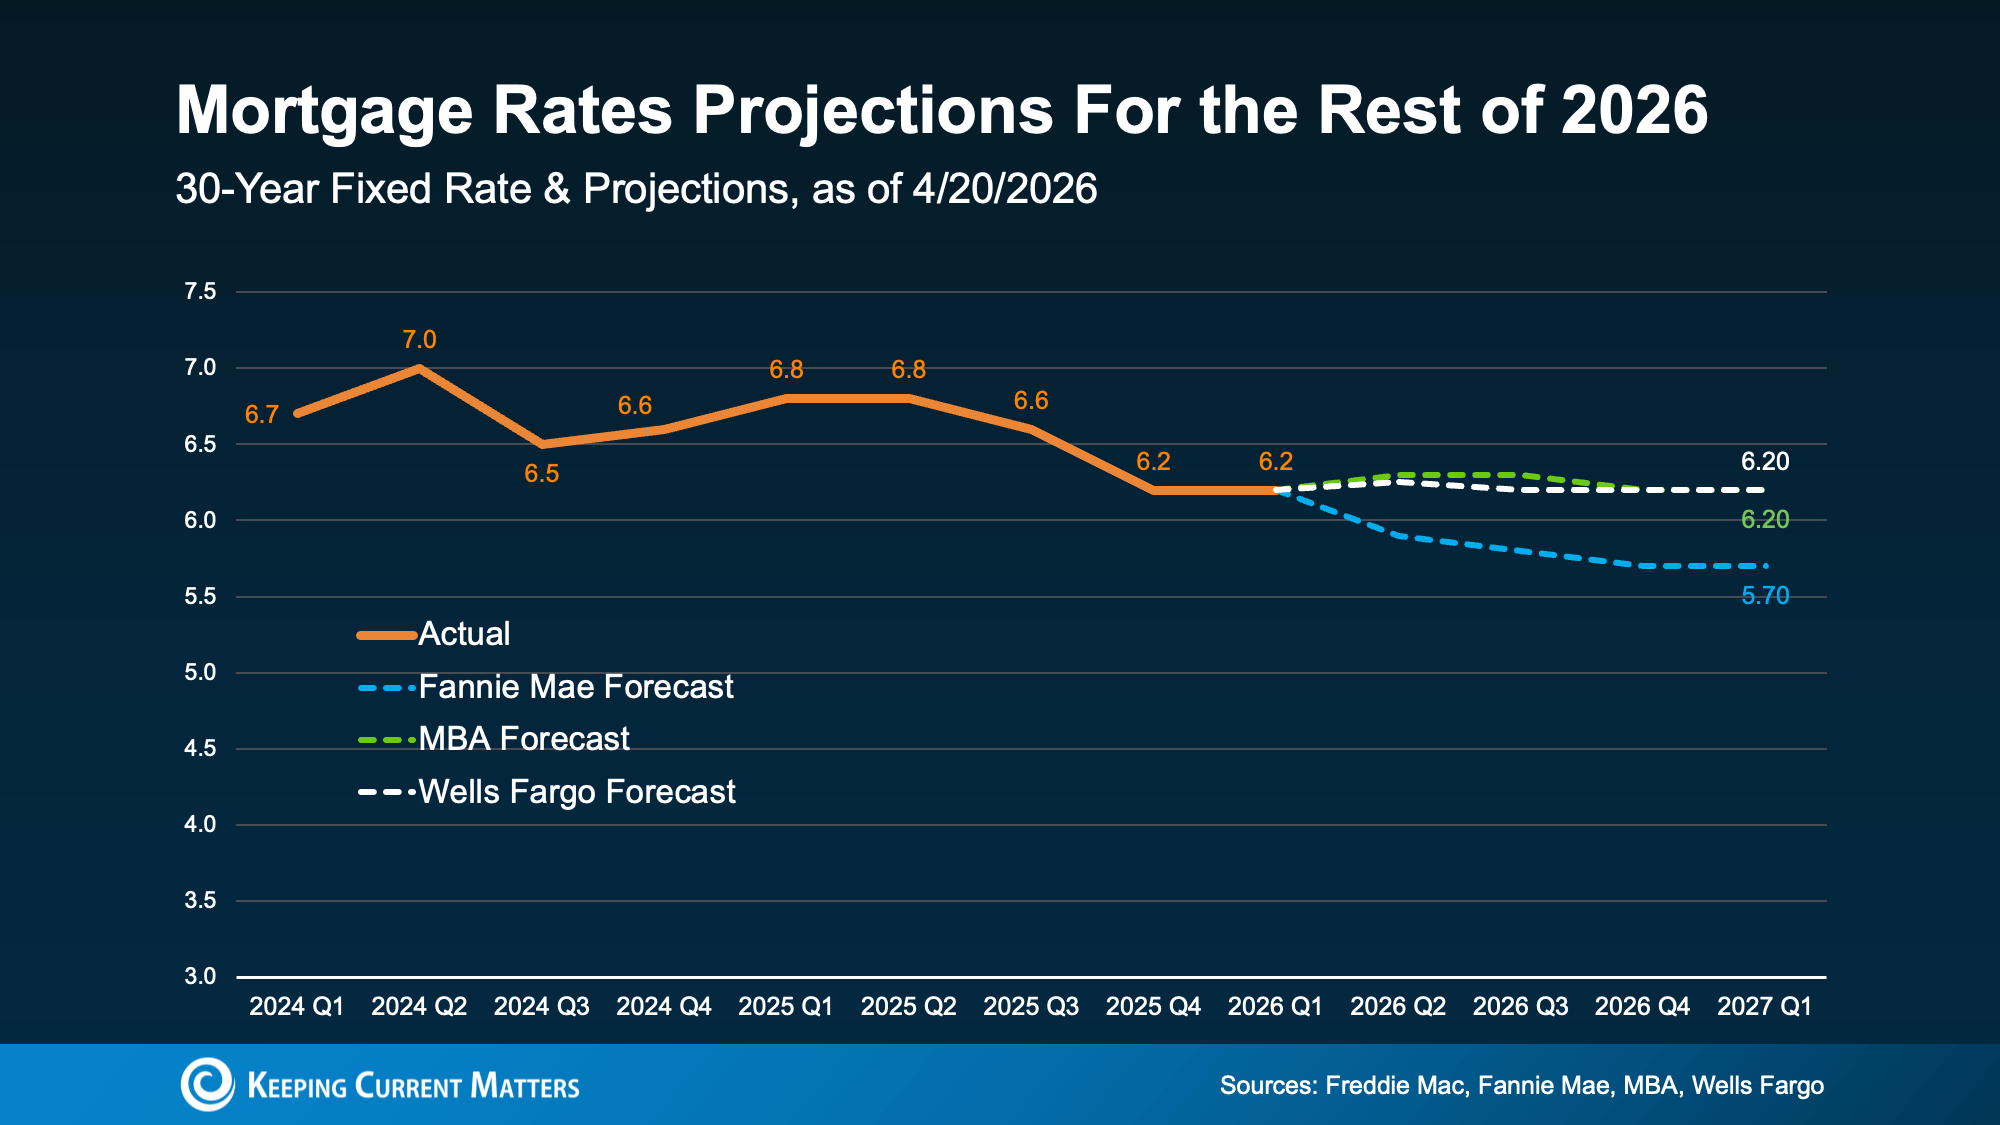
Obviously, a lot depends on inflation and the broader economy. But based on what we know right now, waiting for a big drop in mortgage rates may not play out the way many buyers hope. As U.S. News explains:
“Mortgage rates aren’t expected to change much over the next several quarters . . .”
And even with rates where they are today, buying a home is already more affordable than it was a year ago. Even if rates don’t drop in the near future, home affordability is better now than a year ago.
Misconception #2: “There Are Too Many Homes for Sale”
You may have heard that housing inventory is rising. Nationally, that’s true: the number of homes for sale is 8% higher than it was at this time last year. But that’s not bad news. In lots of markets, it’s easing the pressure on buyers.
The problem is that some headlines make good news sound like bad news. They focus on the fact that inventory is at its highest level since 2019 or highlight how many new homes builders are adding. That can make it sound like supply is growing too much, too fast.
But the bigger picture tells a different story.
According to new Realtor.com data, even though inventory is up over last year, it’s still nearly 14% lower than it was in the last normal housing market from 2017 to 2019:
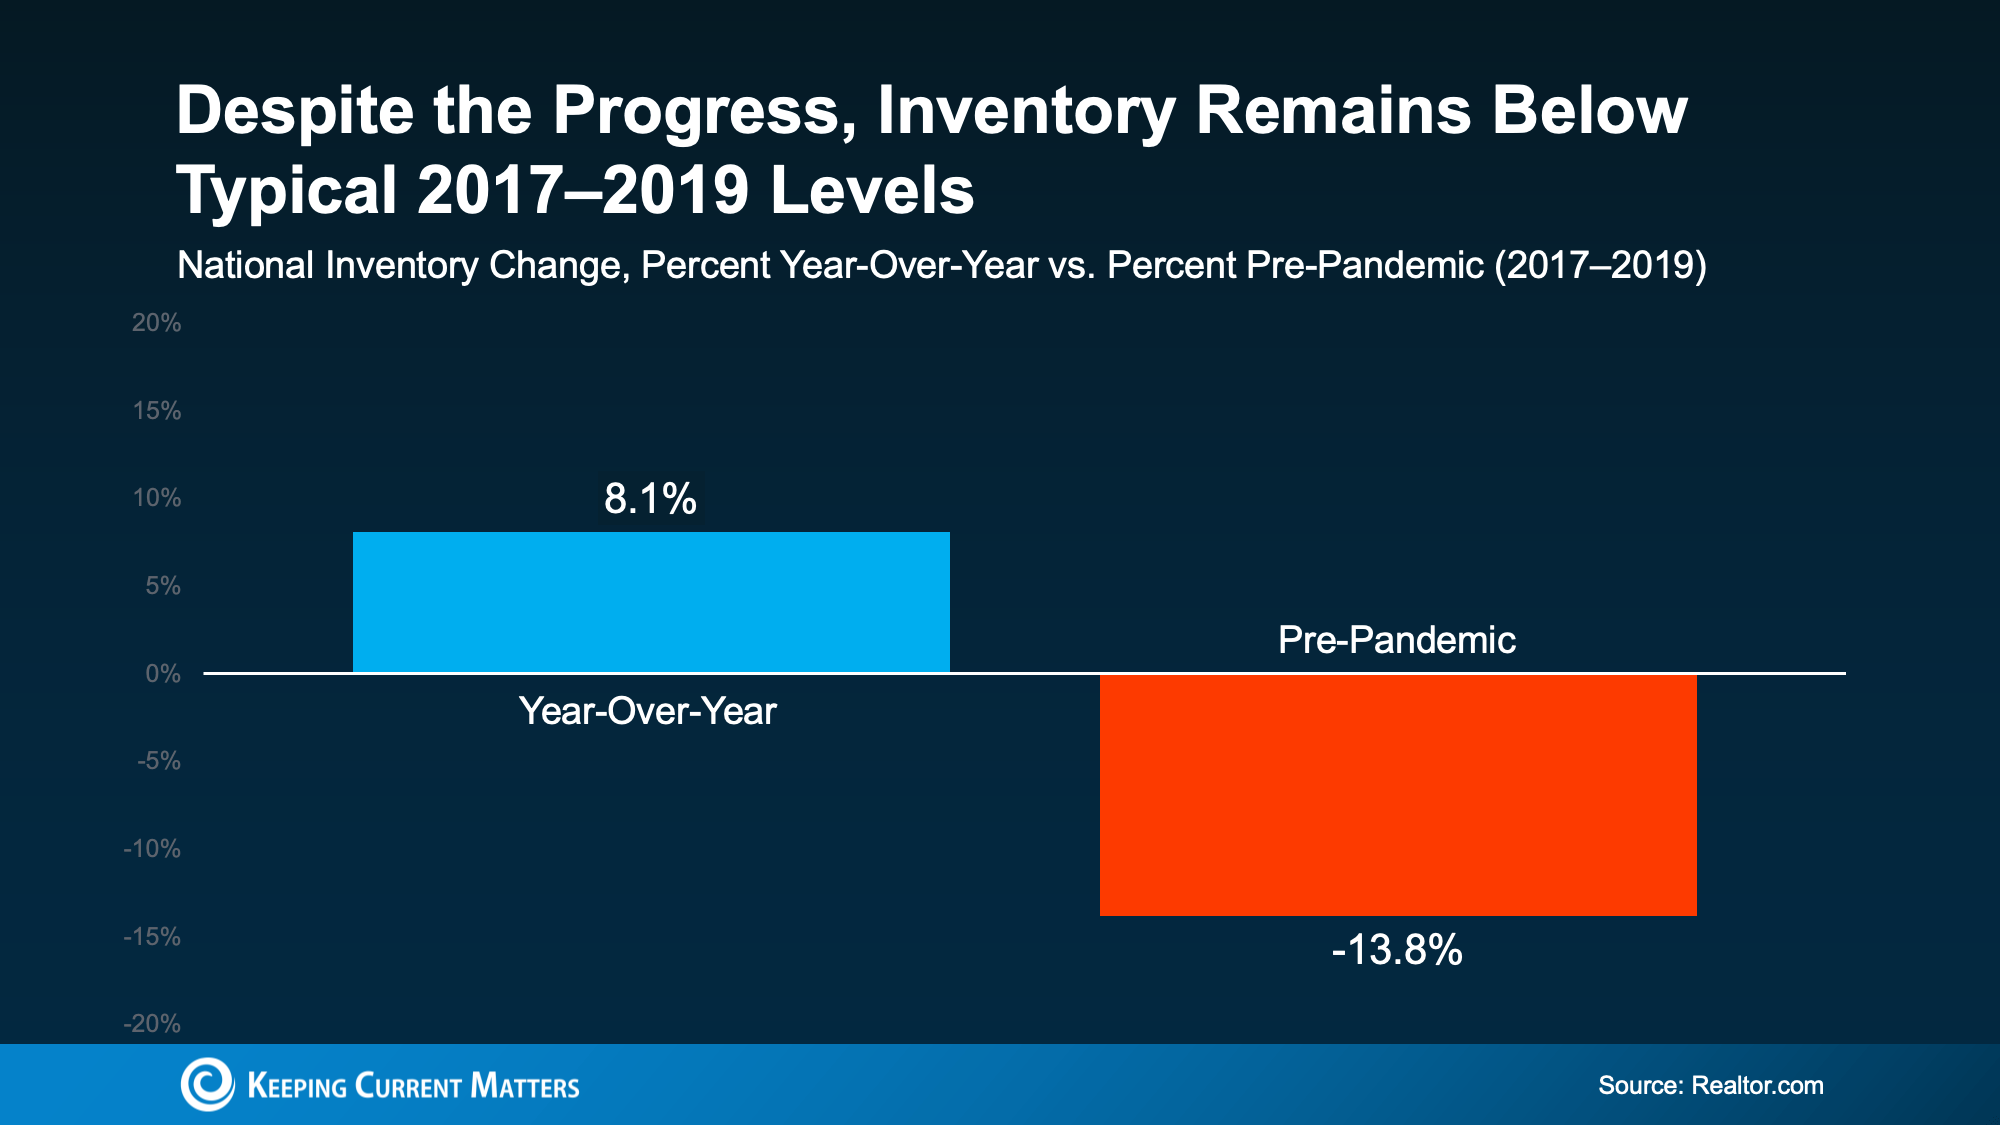
And while local conditions vary, only 9 states have more inventory now than they did before the pandemic. That’s a major reason there aren’t enough homes for sale to trigger anything like the 2008 housing crash.
Misconception #3: “Home Prices Are About To Crash”
This is another common headline you’ve probably seen. This misconception comes from the fact that a few metros are actually seeing small price declines. Influencers are pointing to this to claim home prices are crashing. But this is absolutely not true nationally.
In most markets, home prices are still rising, not falling. Here’s why:
- Many homeowners are choosing not to sell to avoid giving up the low mortgage rate they locked in a few years ago. That continues to limit how much inventory can grow.
- Inventory remains below pre-pandemic norms. There still aren’t enough homes for sale to cause a widespread price crash.
- Even in markets with more listings, some sellers are pulling their homes off the market instead of making major price cuts.
Those are three big reasons home prices are not on track for a crash.
And even in the areas seeing small price declines, those drops are nowhere near enough to erase the huge gains most homeowners have built over the past five years:
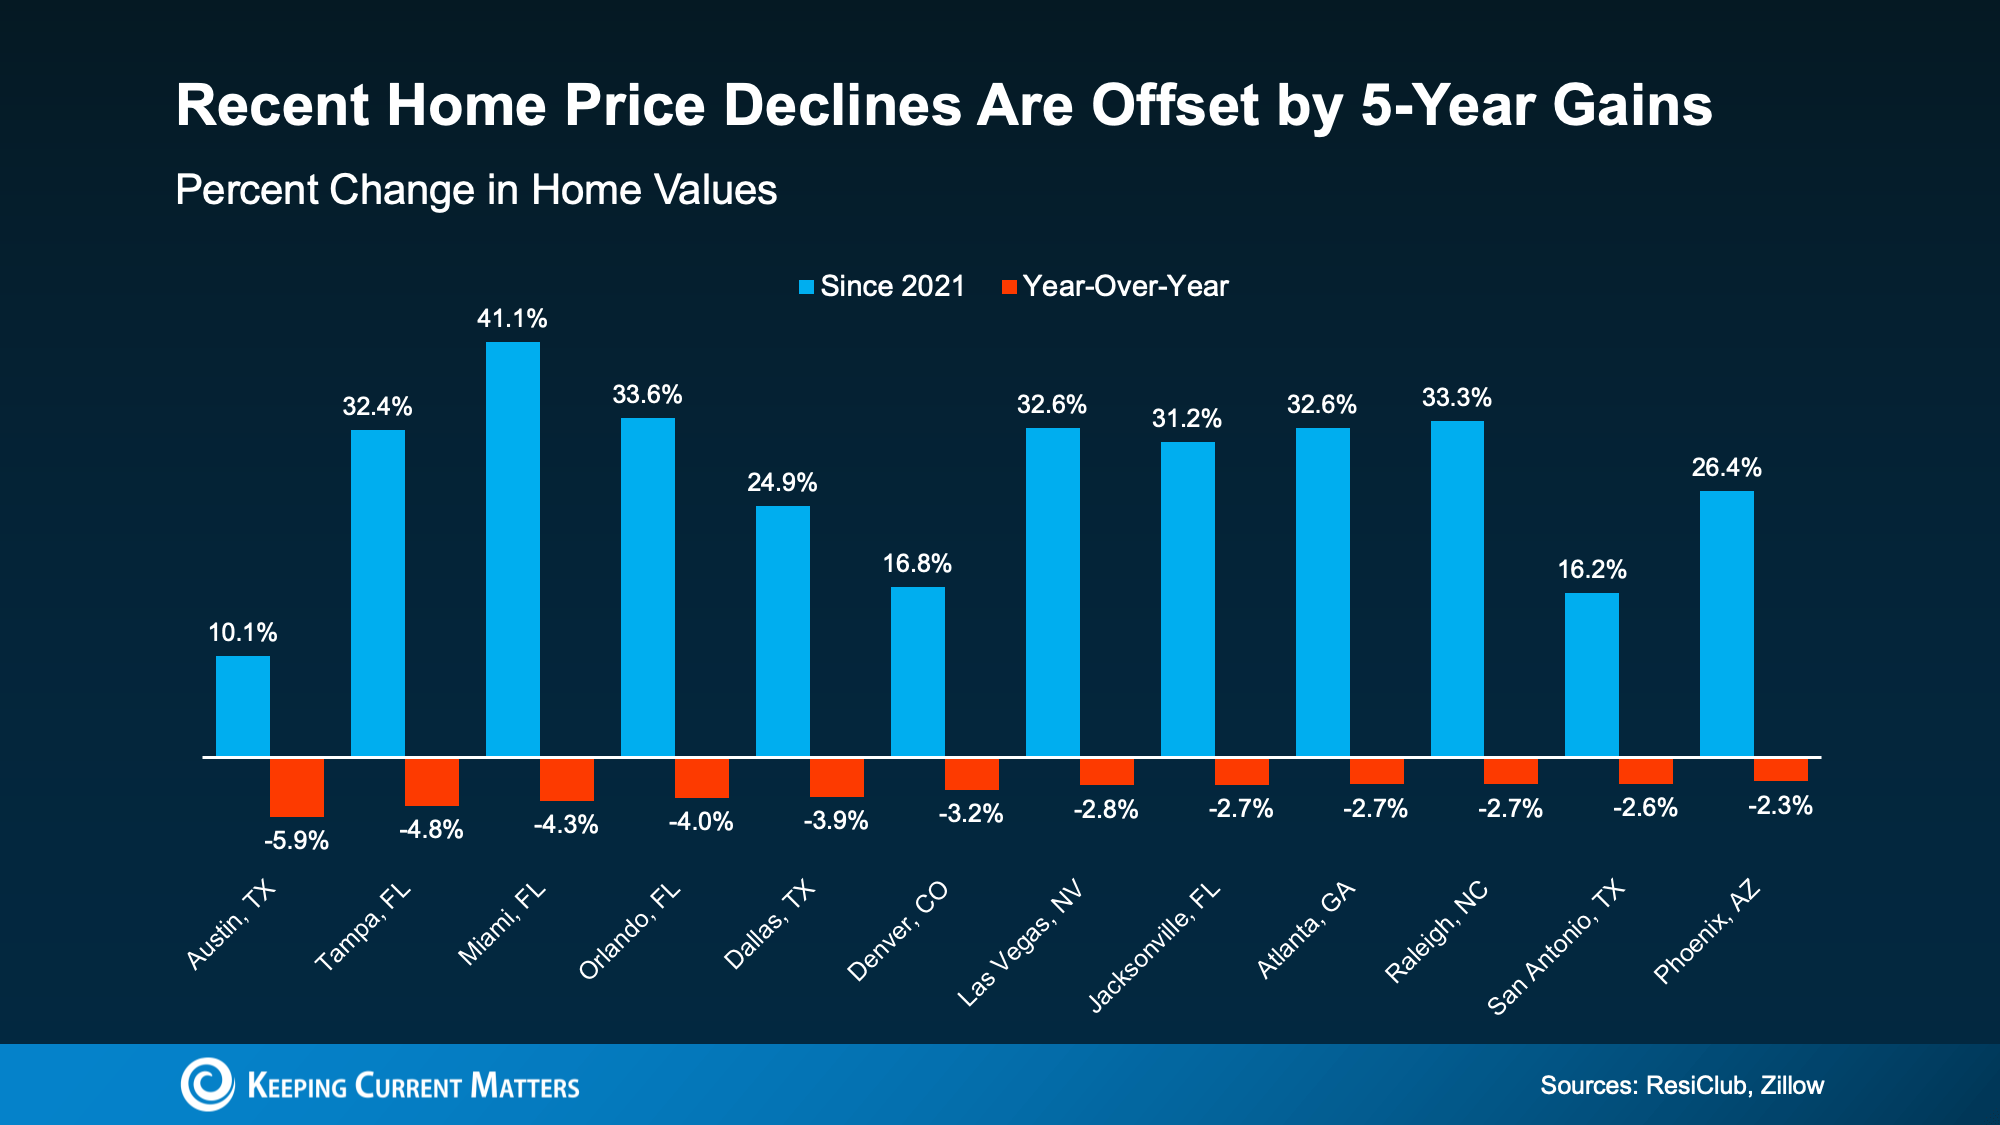
These drops don’t signal a crash. They show the market settling after a few years of record-breaking spikes in prices.
Bottom Line: Get the Facts on Your Market
The discussions we see online can often exaggerate the negative and ignore the positive, especially in housing. If you want a clearer, truer idea of what’s happening with mortgage rates, housing inventory, and home prices in your market, talk to a trusted real estate professional.
Connect with a local real estate agent so you have an expert who can give you the real story on your local housing market.
Should You Still Buy a Home Right Now? What Buyers Need To Know
Between nonstop economic headlines, global uncertainty, and ongoing concerns about affordability, it’s understandable to wonder whether now is still a smart time to buy a home.
The good news is this: current events may be influencing the housing market, but they have not taken homeownership off the table. For many buyers, the opportunity is still there. It just may require a more thoughtful strategy than it did a few months ago.
Mortgage Rates Have Risen Slightly. Here’s What’s Behind It
After trending downward for much of 2025, mortgage rates have climbed again over the past month. Experts point to a mix of global events and broader economic pressures as key reasons why.
As Mark Fleming, Chief Economist at First American explains:
“Mortgage rates have recently moved higher, driven by geopolitical uncertainty and rising energy costs that are contributing to inflation concerns.”
So what does that mean if you’re thinking about buying a home? Should you wait for conditions to settle before making a move?
Not necessarily.
Your Opportunity To Buy Hasn’t Disappeared
There’s no denying that buying felt a bit more affordable when mortgage rates were closer to 6%. Now that rates are hovering in the mid-6% range, monthly payments are naturally a little higher.
But it helps to take a step back and look at the bigger picture.
For example, if you’re financing a $500,000 home, a rate in the mid-6s could still mean a monthly payment that is roughly $300 lower than what buyers were facing early last year.
That means today’s higher rates have not erased all the progress we’ve seen. In fact, buying a home can still be more affordable than it was just a year ago.

Yes, your payment may have been lower a few weeks ago. But trying to perfectly time the market rarely works in your favor. Conditions can shift quickly, and hindsight always makes past decisions look easier.
Instead of waiting for the “perfect” moment, focus on making the best decision based on your goals, finances, and today’s market conditions.
Expect Mortgage Rate Volatility
One thing buyers should be prepared for is continued movement in mortgage rates.
Rates may keep rising or falling in the weeks and months ahead as new economic reports are released and world events continue to unfold. That kind of uncertainty can feel frustrating, but it’s also part of today’s market.
The truth is, you can’t control what happens with inflation, global events, or mortgage rates next week. What you can control is how prepared you are when the right opportunity comes along.
That preparation can make all the difference.
If You Need To Move, You Still Have Options
For many buyers, the decision to move is not just about market timing. Life keeps moving, even when the market feels unpredictable.
Maybe your family is growing. Maybe you’re relocating for work. Maybe your current home no longer fits your lifestyle or needs. Those reasons still matter, and they may be more important than waiting for rates to change.
Buyers who are moving forward right now are often doing so because their personal situation makes it the right time.
And the good news is there are still strategies that can help make a purchase more manageable.
For example, some buyers are exploring adjustable-rate mortgages (ARMs) to secure a lower initial rate. That approach is not right for everyone, but it’s one example of how flexibility and planning can create opportunities in today’s market.
A Smart Plan Starts With the Right Experts
In a market like this, having a plan matters more than ever.
Working with a trusted real estate agent and lender can help you:
- Understand what you can realistically afford at today’s rates
- Review financing options, including ARMs and buyer assistance programs
- Stay informed as market conditions shift
- Make confident decisions based on your goals, not just the headlines
The right professionals can help you look beyond the noise and focus on what makes sense for your specific situation.
Conclusion
Uncertainty in the market does not mean you’re out of options.
If you need or want to move, buying a home may still be the right decision. The key is to go in with a solid plan, the right support, and a clear understanding of your financing options.
Homeownership is still possible. You just need the right strategy for today’s market.
Mortgage Rate Volatility: What You Can Control as a Buyer
Mortgage rates have been moving up and down lately, and that can make buying a home feel harder to plan for. When rates are unpredictable, many buyers wonder whether they should wait, move forward, or try to time the market.
Here’s the good news: while you can’t control where mortgage rates go next, you can control several factors that may help you secure a better rate. The first step is understanding what’s driving today’s market and knowing where to focus your time and effort.
Mortgage Rate Volatility Is Normal
Recent data from Freddie Mac show that mortgage rates have been fluctuating. After trending downward for well over a year, rates ticked up again this month.
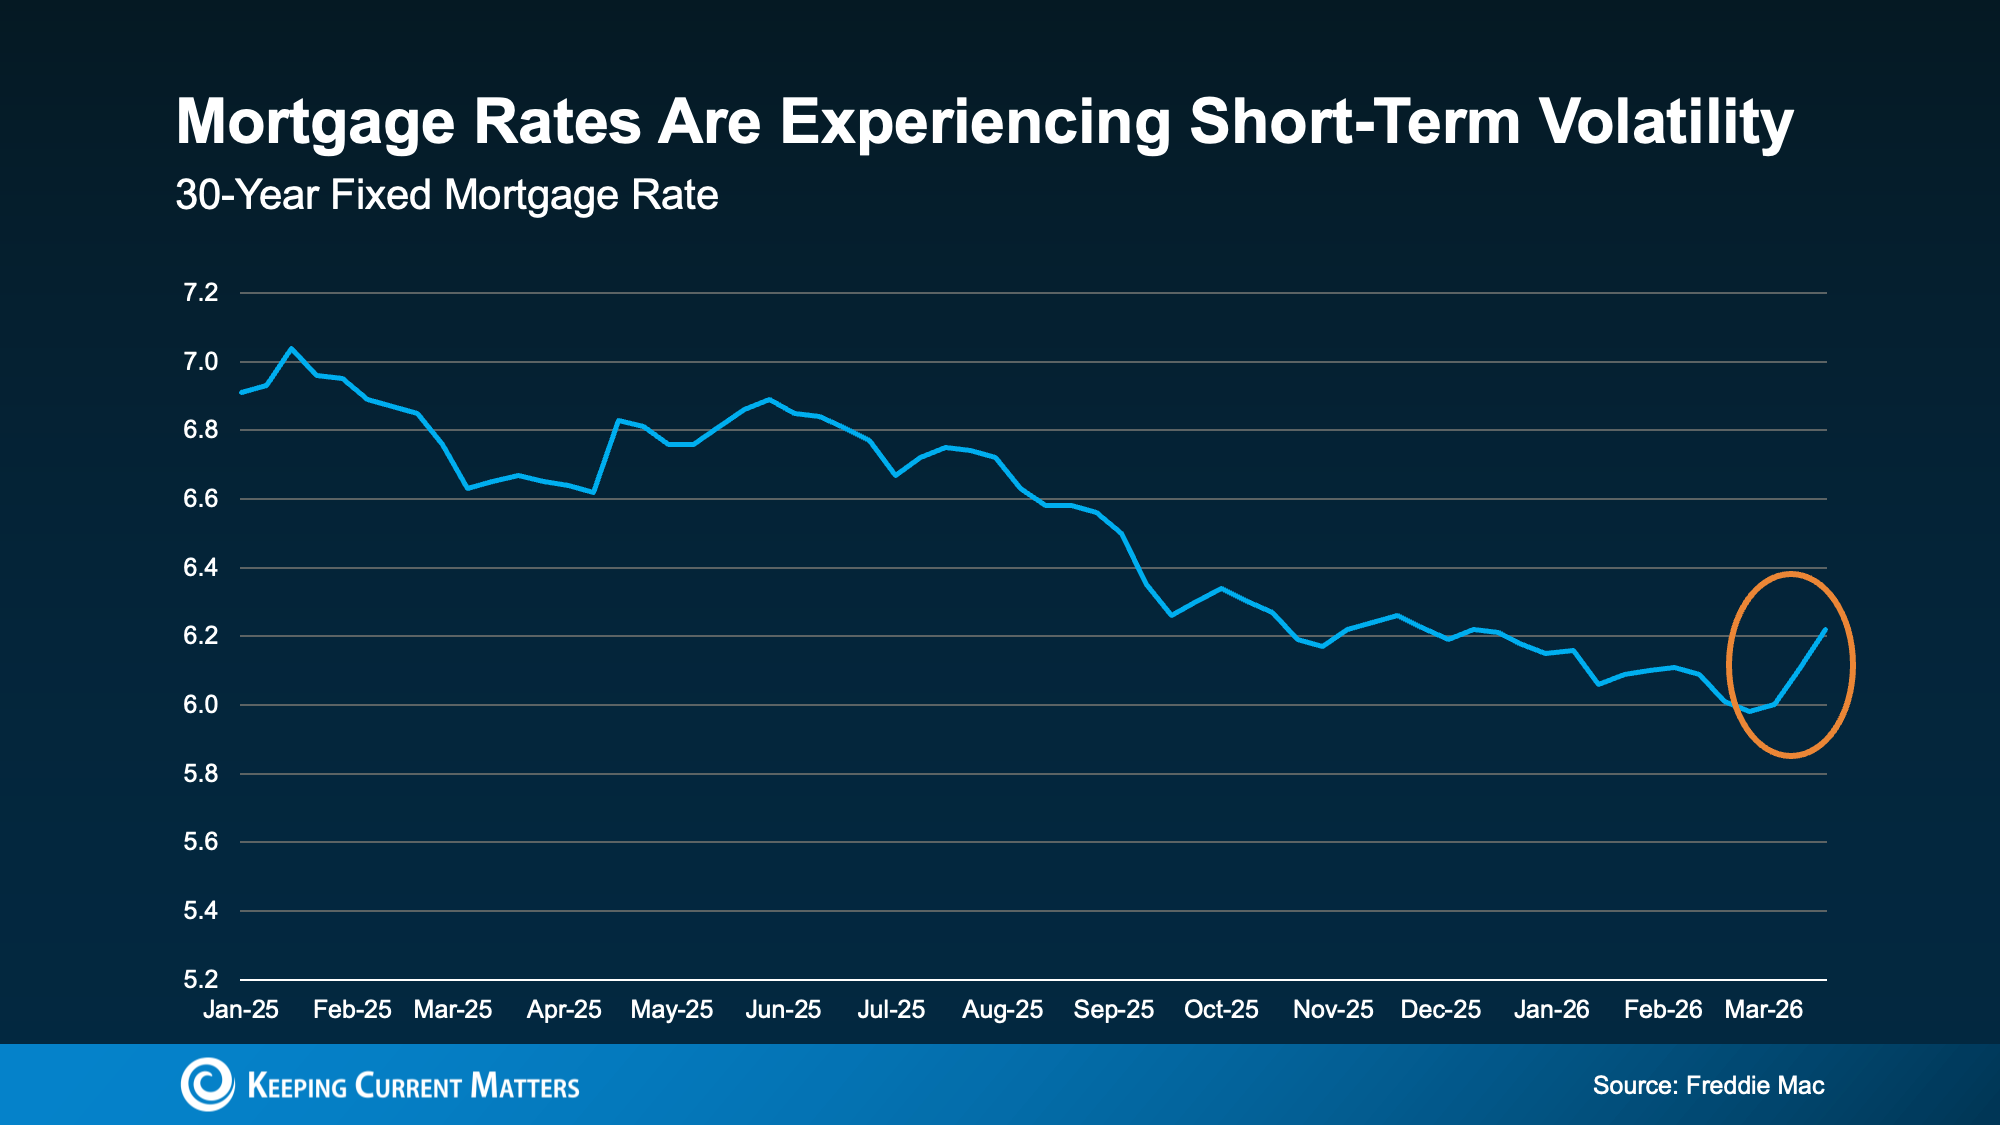
That kind of movement can feel frustrating, especially when you’re doing your best to budget for a home purchase. But occasional increases and decreases are a normal part of the mortgage market. Even over the past year, there have been periods when rates jumped before settling back down.
This is another one of those moments, and it helps to keep that in mind.
When there’s economic uncertainty or major global events unfolding, mortgage rates often respond quickly. As Investopedia explains:
“Mortgage rates don’t move in isolation. When global events inject uncertainty into financial markets . . . that can ripple through to borrowing . . . mortgage costs can respond quickly to geopolitical developments. As long as uncertainty remains elevated, rate swings may continue.”
That’s exactly why trying to predict the perfect time to buy usually doesn’t pay off. Rates can change fast, and waiting for the market to cooperate may not give you the outcome you want.
Focus on What You Can Control
You may not be able to influence the market, but you can take steps put yourself in a better position as a buyer. If your goal is to get the best mortgage rate possible, these are the areas that matter most.
Your Credit Score
Your credit score is one of the biggest factors that affects the rate you qualify for. In many cases, even a modest improvement in your score can lead to better loan terms and a lower monthly payment.
As Bankrate explains:
“Your credit score is one of the most important factors lenders consider when you apply for a mortgage. Not just to qualify for the loan itself, but for the conditions: Typically, the higher your score, the lower the interest rates and better terms you’ll qualify for.”
That’s why it’s worth taking steps to strengthen your credit before applying for a mortgage. Paying bills on time, reducing outstanding debt, and avoiding new credit inquiries can all help. If you’re not sure where your score stands or what improvements would make the biggest difference, a trusted loan officer can help you create a plan.
Your Loan Type
The type of mortgage you choose also affects your rate. There are many different types of loans, and each comes with different eligibility requirements, benefits, and pricing.
The Consumer Financial Protection Bureau (CFPB) explains:
“There are several broad categories of mortgage loans, such as conventional, FHA, USDA, and VA loans. Lenders decide which products to offer, and loan types have different eligibility requirements. Rates can be significantly different depending on what loan type you choose.”
This is why exploring your mortgage options is so important. A conventional loan may be the right fit for one buyer, while an FHA, USDA, or VA loan may offer better advantages for another. Comparing programs and speaking with more than one lender can help you understand which path makes the most sense for your financial situation.
Your Loan Term
The length of your loan term matters, too. Most lenders offer 15-year, 20-year, and 30-year mortgage options, and the term you choose can affect both your interest rate and your monthly payment.
Freddie Mac explains it this way:
“When choosing the right home loan for you, it’s important to consider the loan term, which is the length of time it will take you to repay your loan before you fully own your home. Your loan term will affect your interest rate, monthly payment, and the total amount of interest you will pay over the life of the loan.”
A shorter loan term may come with a lower interest rate, but the monthly payment is often higher. A longer term may give you more flexibility in your monthly budget, even if you pay more interest over time. The right choice depends on your goals, your budget, and how long you plan to stay in the home.
Conclusion
If you’re in the market for a home right now, the best strategy is not to focus on trying to predict where mortgage rates will go next.
Instead, focus on what you can control. Improve your credit score, explore different loan types, and choose a loan term that fits your needs. Most importantly, work with a trusted lender who can guide you through your options. If you need help connecting with trustworthy lender, reach out to us today.
Mortgage rates may be out of your hands, but the steps you take to prepare are not. And when you focus on what you can change, you give yourself a much better chance to move forward with confidence.
Home Affordability Improved in All 50 States: What Buyers Need To Know
For the past few years, affordability has been one of the biggest reasons buyers have put their home search on hold. Maybe you did the same.
At some point, you may have looked at the numbers, saw what a monthly mortgage payment would be, and decided to wait for the market to become more manageable. But there’s encouraging news you may have missed.
Over the past year, housing affordability has improved in all 50 states. Yes, every single one.
That’s according to new research from First American. And while buying a home is still more expensive than what’s historically normal, the affordability pressure many buyers have felt over the last several years is finally starting to ease.
Some Markets Are Seeing Bigger Improvements
One of the most important things to understand is this isn’t limited to one part of the country or just a few select markets. Affordability is improving almost all over the country.
Of course, real estate is always local. Conditions can vary a lot from one state, city, or neighborhood to the next. But overall, the market is becoming more favorable for buyers. In fact, affordability has improved in 48 of the top 50 metros over the past year.
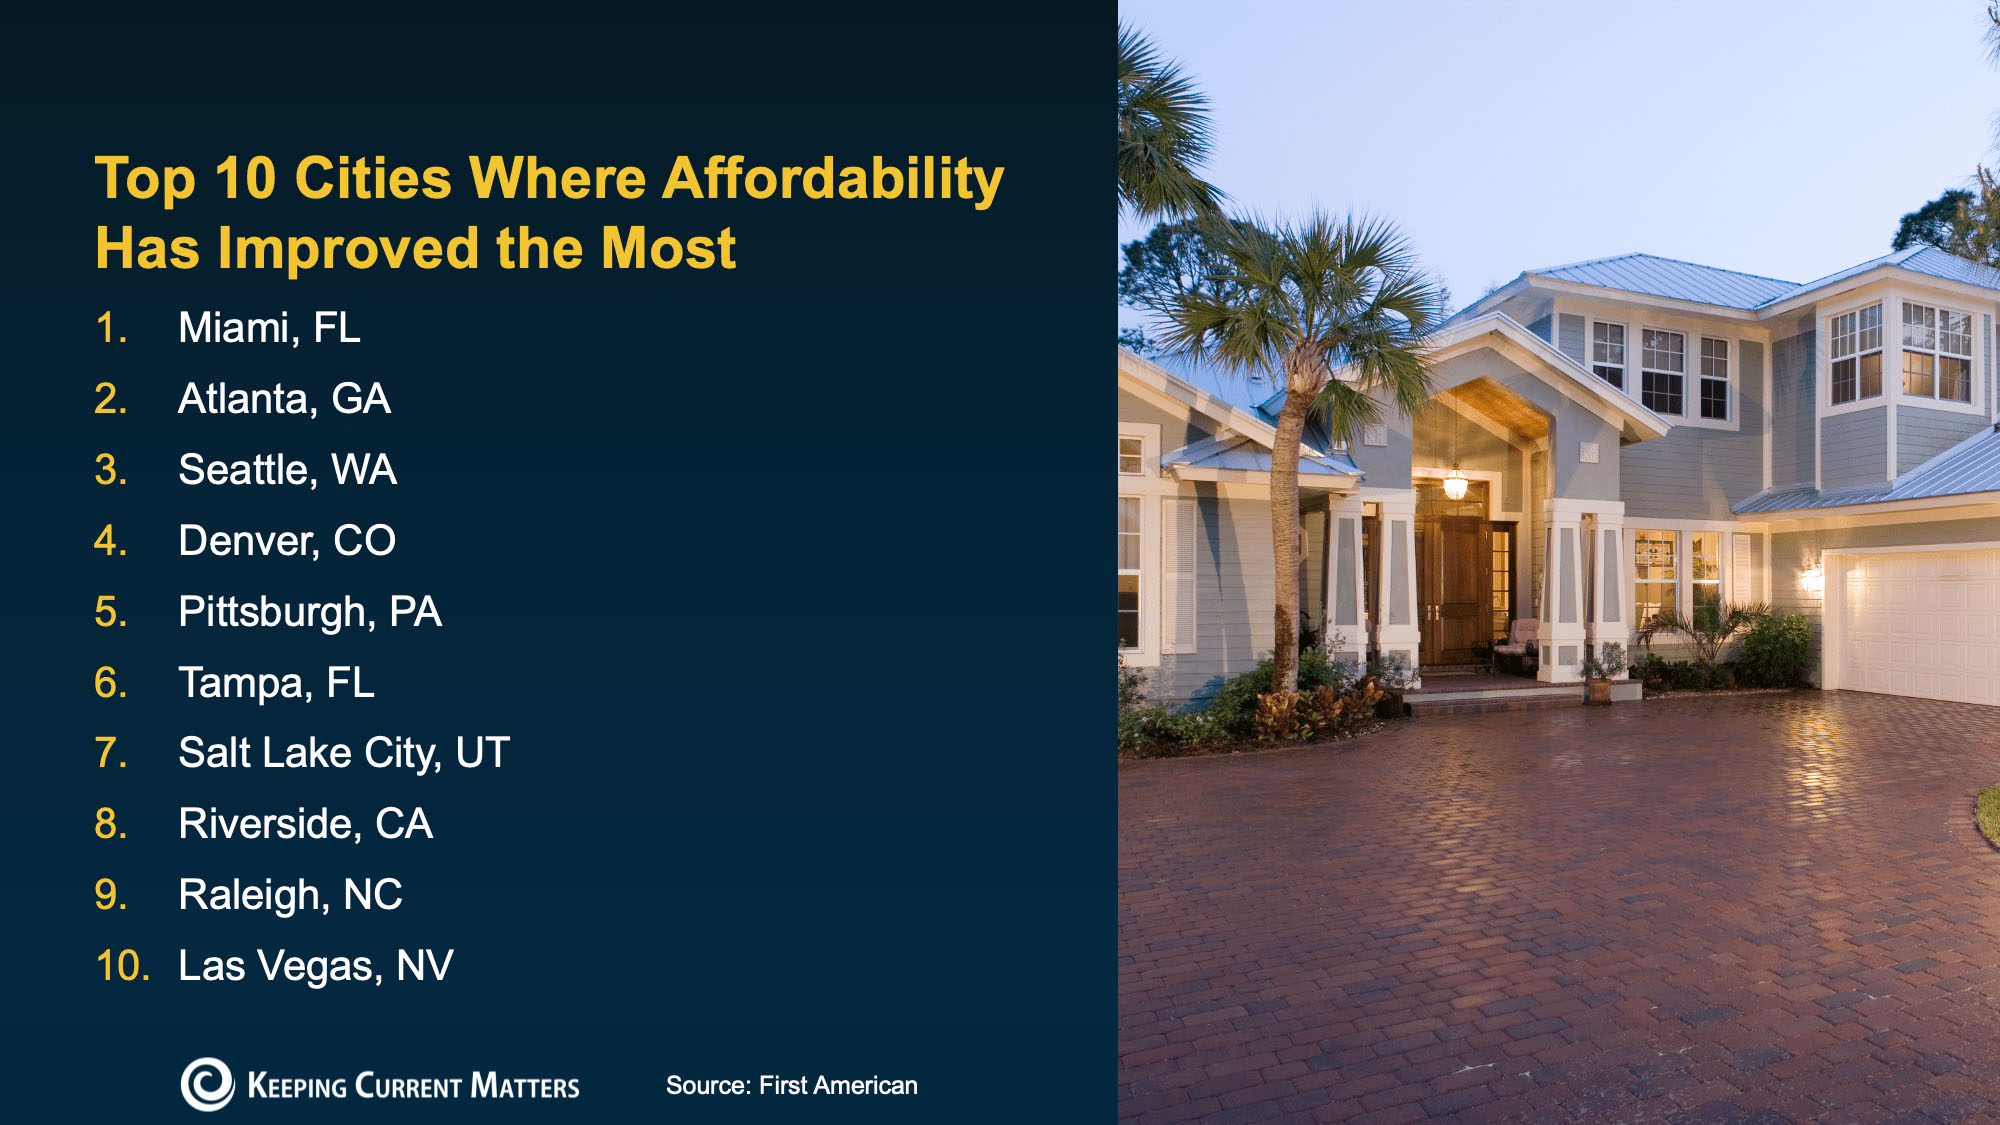
That same research also highlights the top 10 cities seeing the biggest gains in affordability:
Top 10 Cities Where Home Affordability Has Improved the Most
- Miami, FL
- Atlanta, GA
- Seattle, WA
- Denver, CO
- Pittsburgh, PA
- Tampa, FL
- Salt Lake City, UT
- Riverside, CA
- Raleigh, NC
- Las Vegas, NV
If you’re wondering why some markets are improving faster than others, a lot of it comes down to home inventory.
When there are more homes for sale, the market becomes more balanced. This can help improve affordability by giving buyers more negotiating power. With more options available, buyers may have a better chance of finding a home that fits their budget, and they may also be in a stronger position to ask for seller concessions, price reductions, or closing cost assistance.
That can make a bigger difference than many people expect.
What Does This Mean for Buyers?
Home affordability challenges haven’t disappeared altogether, obviously. Buying a home is still a major financial decision, and housing prices remain high in many markets. But the overall nationwide trend is moving in a direction that gives buyers more opportunity than they’ve had in recent years.
As Chen Zhao, Head of Economic Research at Redfin, explains:
“The housing affordability crisis is showing signs of easing. . . opening the door for more Americans to make the jump to homeownership.”
Conclusion
If you’ve been waiting on the sidelines for affordability to improve, this may be the sign you’ve been hoping for. To find out what’s happening in your local market and how much buying power you may have today, connect with a trusted local real estate agent.
Renting vs. Buying: What The Numbers Say
Renting often feels like the simpler move these days. There’s no down payment to save up for, no surprise repair bills, and no long-term commitment if life changes.
But then your lease renews and the rent jumps. Then it happens again. Eventually, what felt flexible suddenly starts to feel expensive, especially when you realize every monthly payment is going to your landlord, not building wealth for you.
A big reason this stings is because there’s been so much talk about how homeownership is “out of reach.” And in some markets, it absolutely can be. But here’s the part that doesn’t get said enough: when you compare the numbers side by side, buying can cost less per month than renting in more places than most people expect.
Buying Can Be More Affordable Than Renting in Many Areas
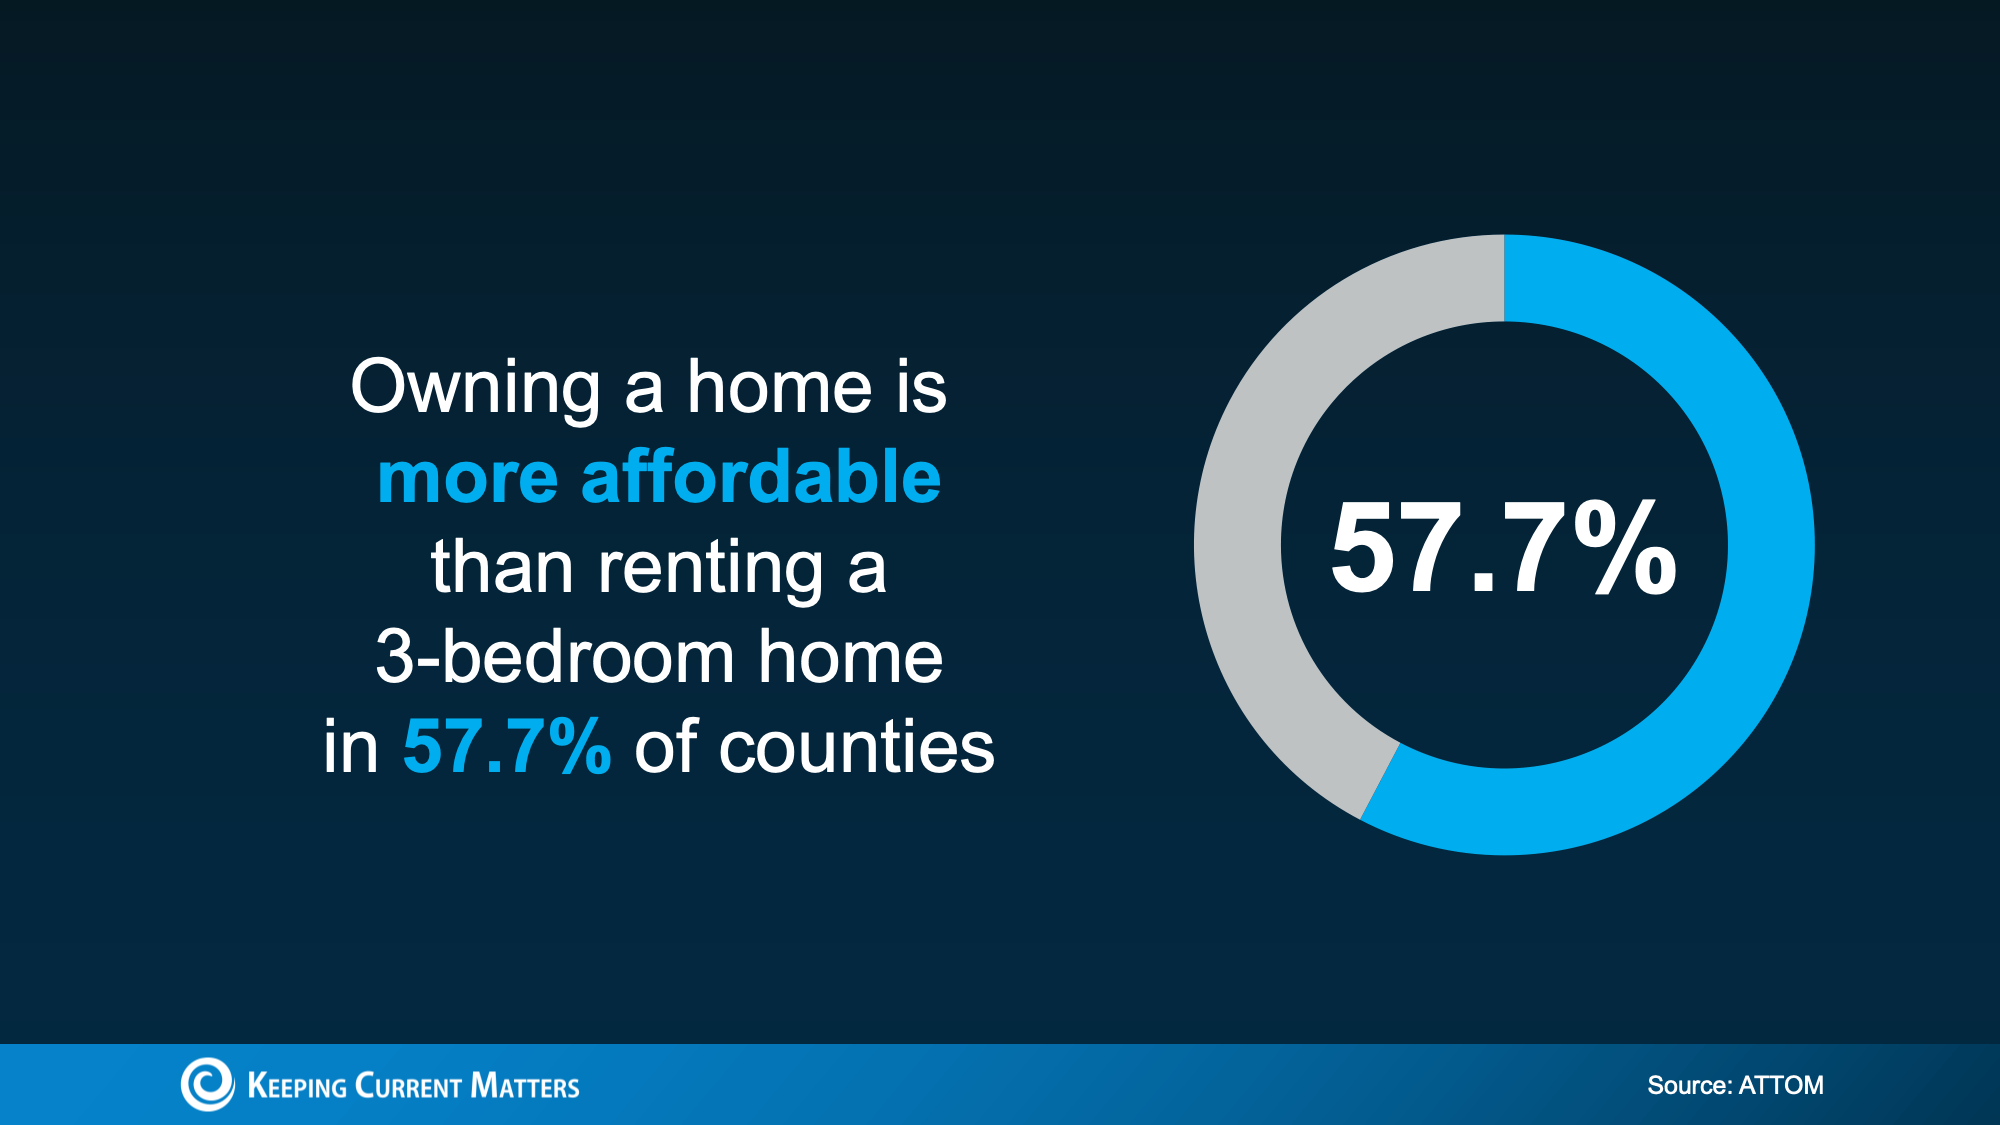
In a lot of markets today, owning a home may actually have a lower monthly cost than renting a 3-bedroom home. New data from ATTOM suggest this is true in nearly 58% of counties across the United States.
And this comparison isn’t just a mortgage payment versus rent. It also takes into account common ownership costs like insurance and regular maintenance.
So if you’ve assumed buying automatically means a higher monthly bill, it may be worth a second look. Recent changes in home price growth, housing inventory, and mortgage rates have been shaking certain markets. Depending on where you live, buying might be finally in your favor.
Affordability Depends on Where You Live
Even though the national picture has shifted, it doesn’t mean buying is cheaper everywhere, or that every renter will have the same experience.
That “nearly 58%” figure looks very different depending on the region. The biggest improvement is happening in the Midwest and South, while the West can still feel tight for many households.
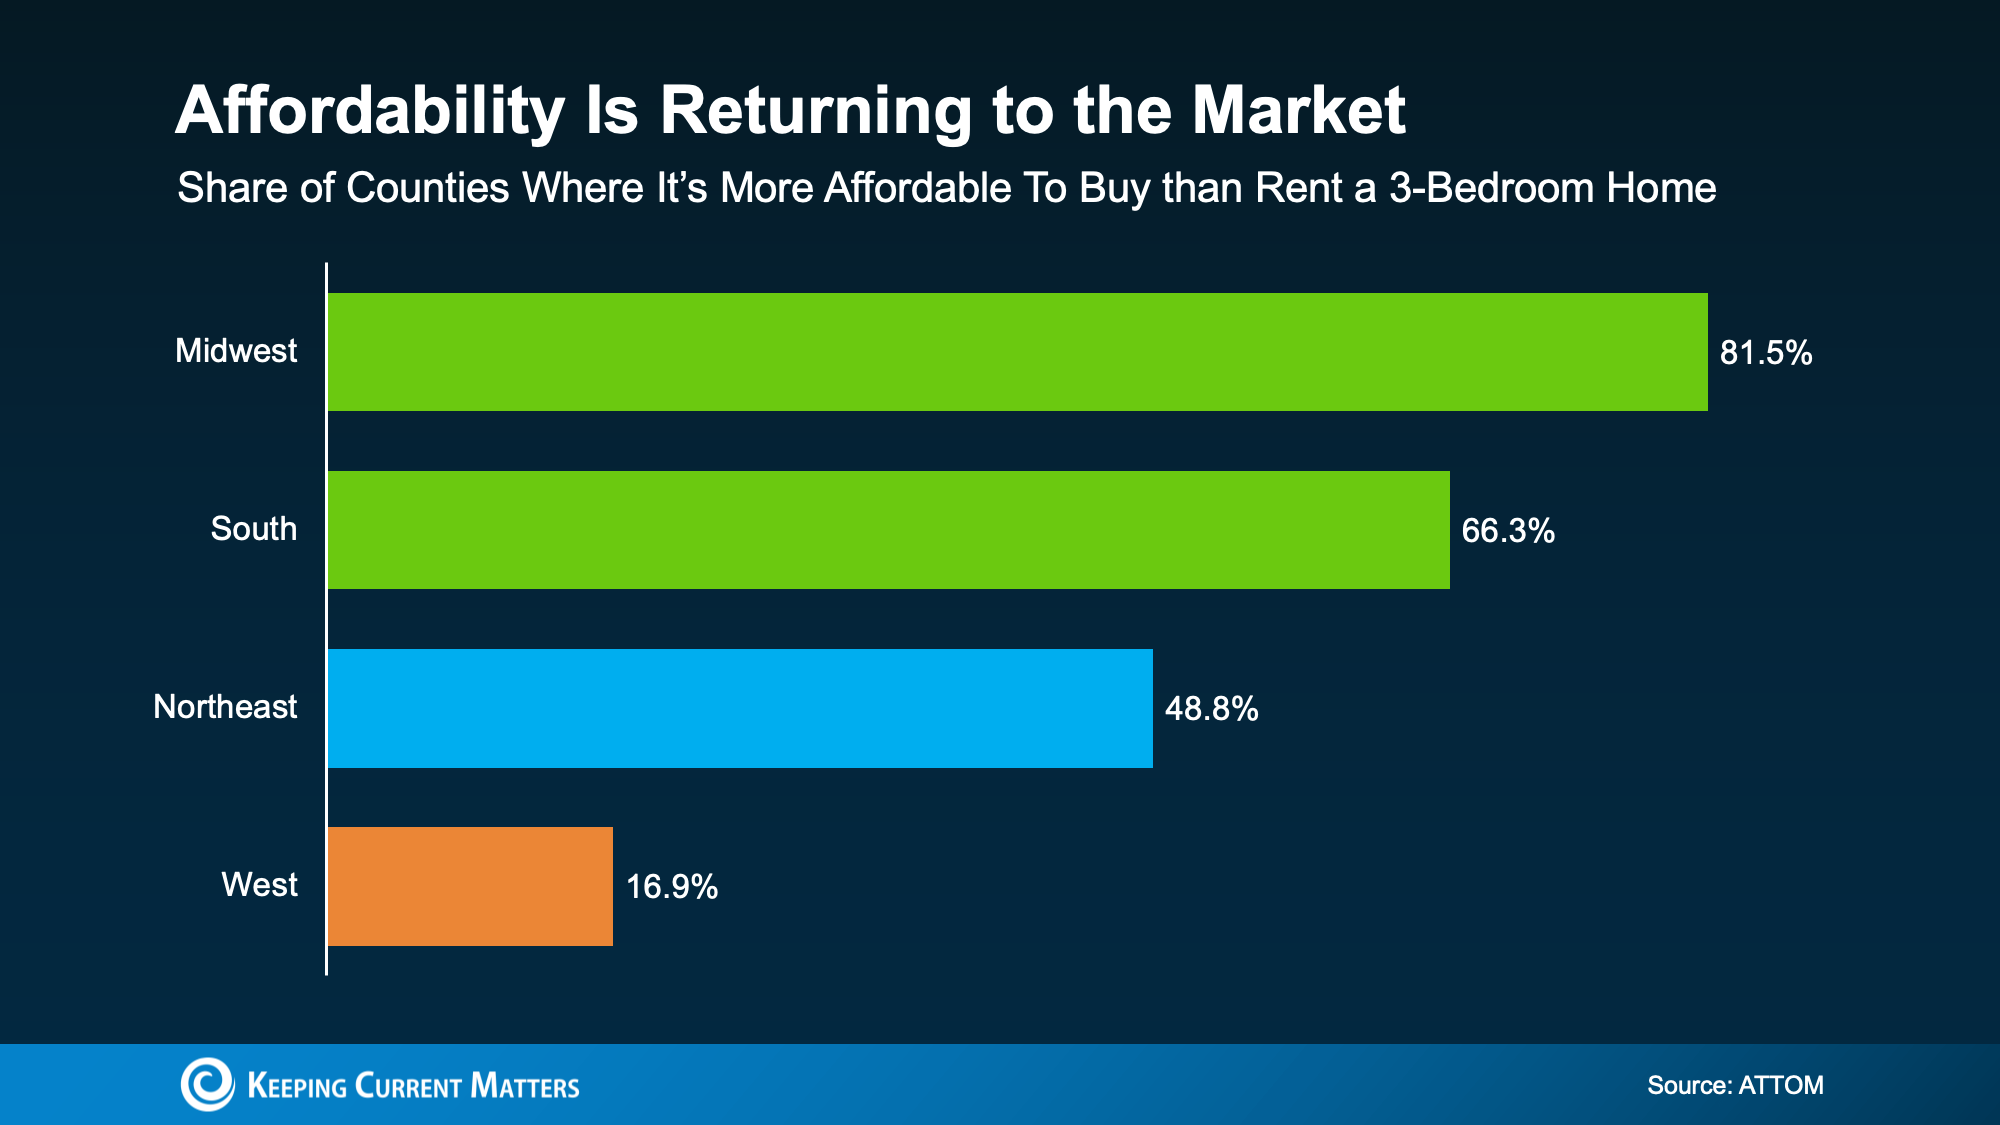
The key takeaway is simple: real estate is local. A national headline can’t tell you what the rent-versus-buy equation looks like in your zip code. The only way to know is to run the numbers based on your local prices, rents, taxes, and insurance.
What’s Still Holding Buyers Back?
If you’re thinking, “Even if the monthly payment works, I can’t afford the upfront costs,” you’re not alone.
For many renters, the biggest hurdle isn’t the monthly payment. It’s the down payment (and often closing costs) that feels like a wall.
Here’s the good news: there are thousands of down payment assistance programs across the country, and many buyers qualify without realizing it. The average benefit is around $18,000, which can help cover part of your down payment or closing costs.
Support like this can make buying feel a lot more realistic, because it reduces how much cash you need to get in the door.
How to Figure Out What’s Right for You
If you want clarity instead of guesswork, focus on a simple comparison:
- Your current rent (and how often it’s rising).
- An estimated monthly ownership cost (mortgage, taxes, insurance, HOA if applicable).
- A realistic maintenance cushion.
- Upfront costs (and any down payment assistance you may qualify for).
When you combine potential assistance with monthly costs that may be closer than expected, the gap between renting and buying can shrink quickly, or even flip in favor of buying.
Conclusion
The bottom line isn’t that everyone should buy a home as soon as possible.
The idea is that renting isn’t always the cheaper option people assume it is, and buying may be more realistic than it feels once you look at the full picture.
If you’re renting and feel stuck saying “someday”, consider a quick conversation with a local real estate agent or lender. Not a commitment, just a way to see what’s possible and whether it makes sense for you.
Good News for Buyers: Home Affordability Improving in 2026
If you’ve felt priced out of the market or stuck waiting on the sidelines, there’s finally some encouraging news:
Buying a home is finally becoming more affordable.
Monthly payments have started to come down thanks lower interest rates, and buyers are starting to feel pricing pressures ease. That doesn’t mean homeownership is suddenly easy for everyone, but after a tough stretch, small improvements are meaningful.
Home Affordability Is Finally Improving
One of the clearest ways to track this change is to look at how much of a household’s income goes toward owning a home.
According to Zillow, housing is typically considered affordable when total housing costs take 30% or less of your monthly income. That includes your mortgage payment, property taxes, insurance, and basic maintenance.
For the past few years, many buyers were well above that mark, which pushed homeownership out of reach for a lot of households. But that’s starting to shift. Zillow research shows it’s taking less of a typical household’s income to buy a home than it did just a few years ago (see graph below):
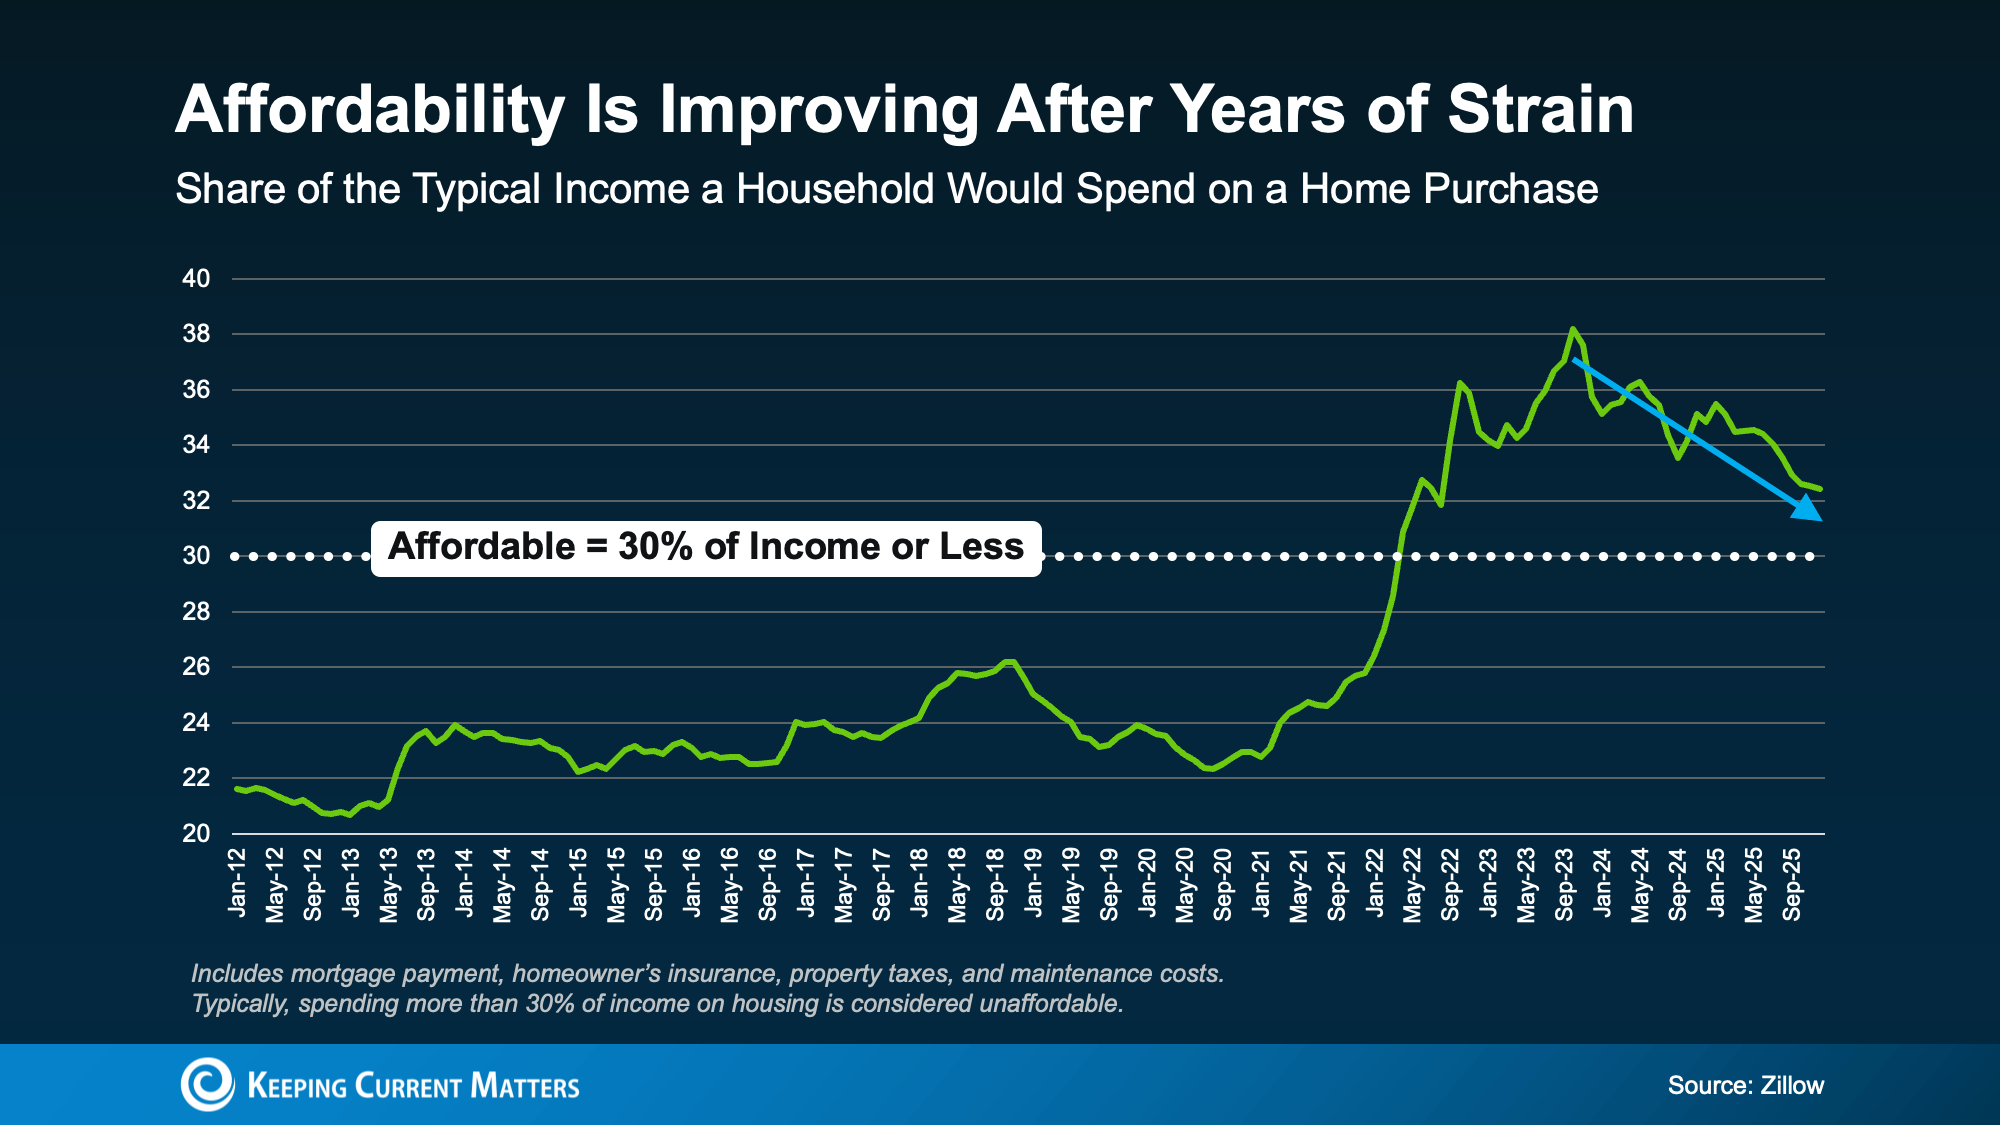
We’re not all the way back to Zillow’s 30% threshold yet, so affordability is still tight in many markets. But the trend is improving, and that’s a big change from what buyers have been up against.
Why Homebuying Is Becoming More Affordable
Mortgage rates get most of the attention, and yes, rate movement plays a major role in monthly payment size. But it’s not the only reason affordability is improving. Three key trends are working in buyers’ favor right now:
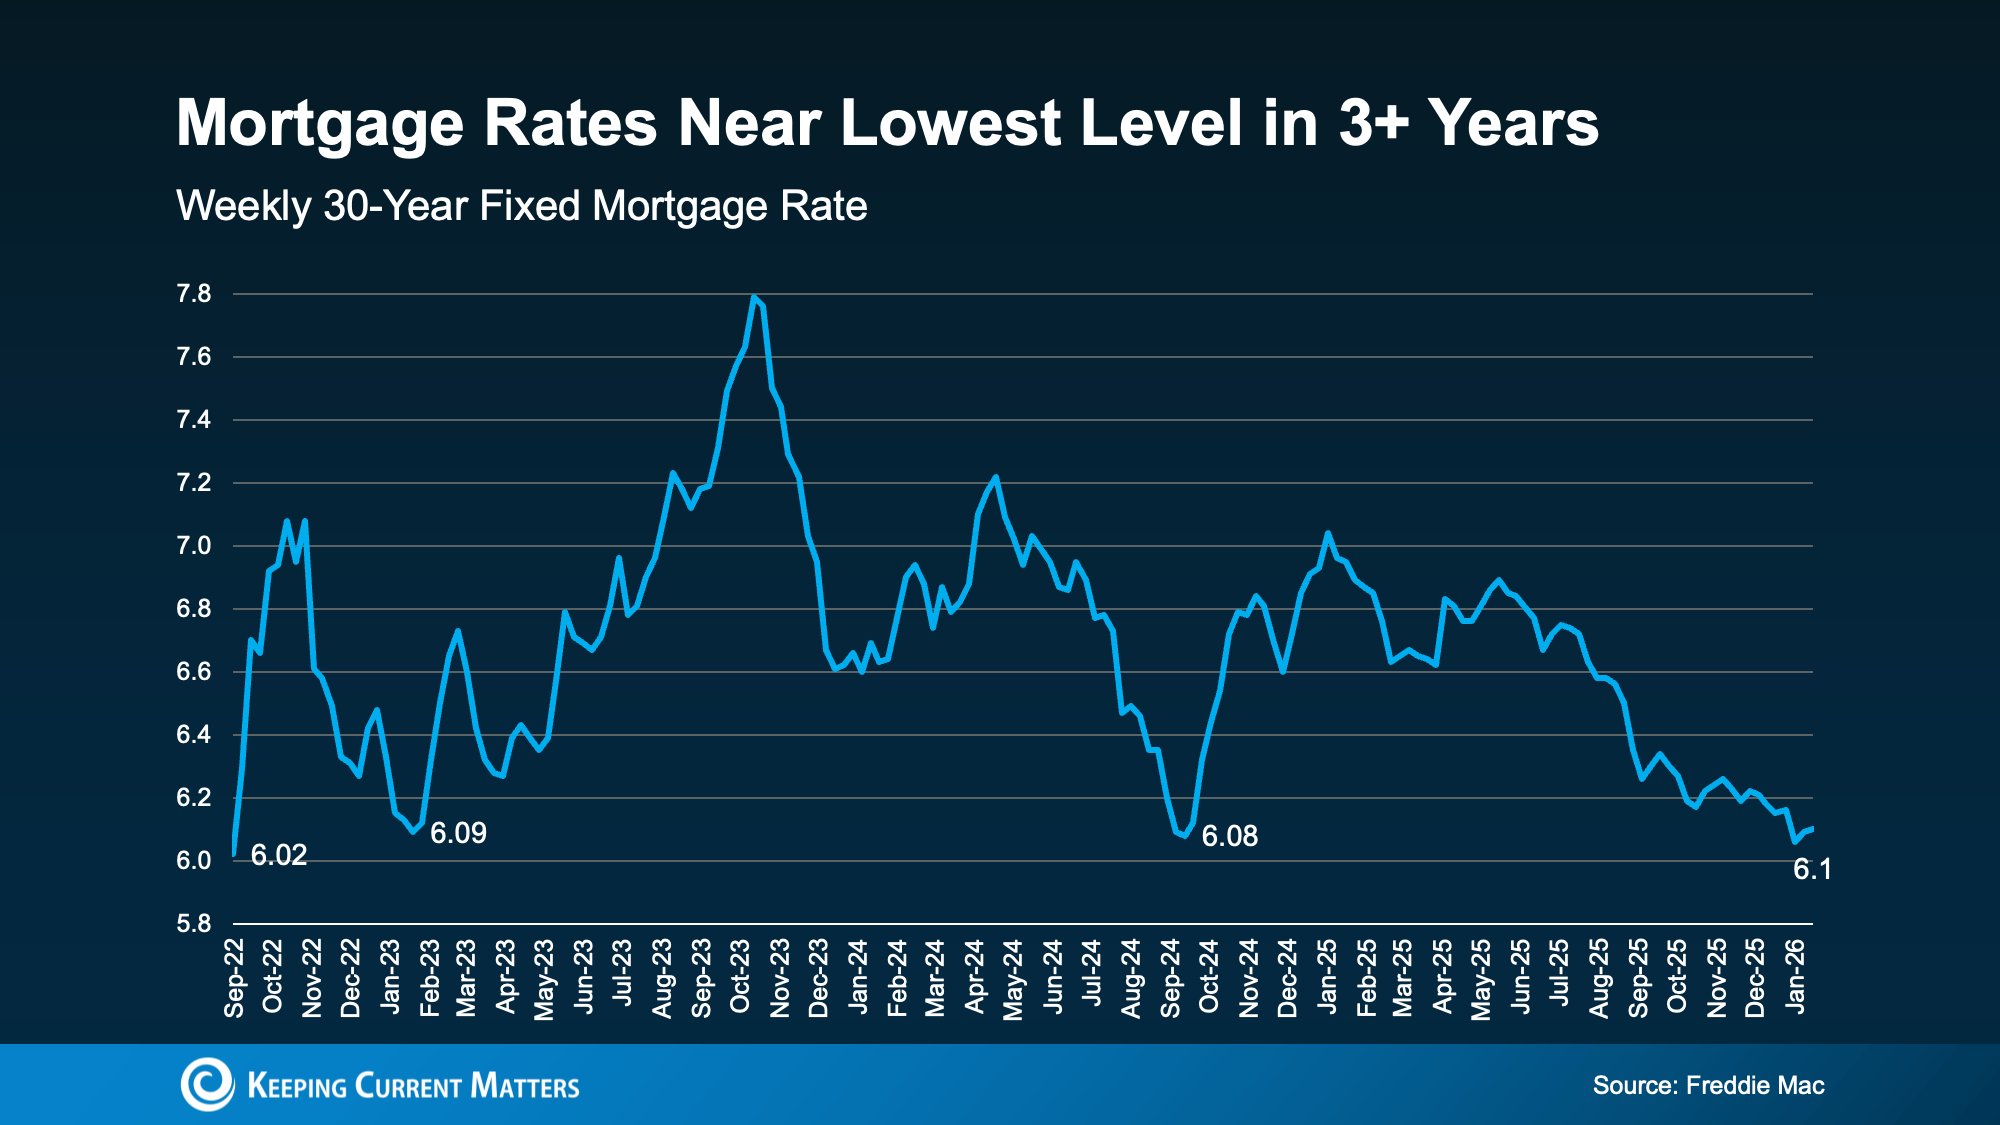
1) Mortgage rates have eased
Rates are near their lowest level in more than three years, which can reduce monthly payments and expand buying power (see graph below):
2) Home price growth has cooled
Home prices aren’t falling nationally, but they’re rising more slowly than they were a few years ago. That matters because slower price growth helps keep purchase prices from jumping as sharply, which can make payments feel more manageable and the overall buying process more predictable.
3) Wages are growing faster than home prices
This is a major factor that often gets overlooked. When incomes rise faster than home prices, buyers can start catching up. Mark Fleming, Chief Economist at First American, explains:
“When income growth exceeds house price growth, house-buying power improves—even if mortgage rates don’t decline meaningfully.”
None of this makes homes “cheap,” but it does help explain why the math is starting to work a bit better than it did even a year ago. In short, some of the forces that curbed affordability are finally easing. As Fleming again explains:
“Affordability remains challenging, but for the first time in several years, the underlying forces are finally aligned toward gradual improvement. Mortgage rates may drift down only slowly, but income growth exceeding house price appreciation will provide a boost to house-buying power — even in a higher-rate world. Affordability won’t snap back overnight, but like a ship finally catching a steady tailwind, it’s now sailing in the right direction.”
Because of these combined shifts, many economists expect affordability to continue improving in 2026.
Where Are Homes Becoming Affordable First?
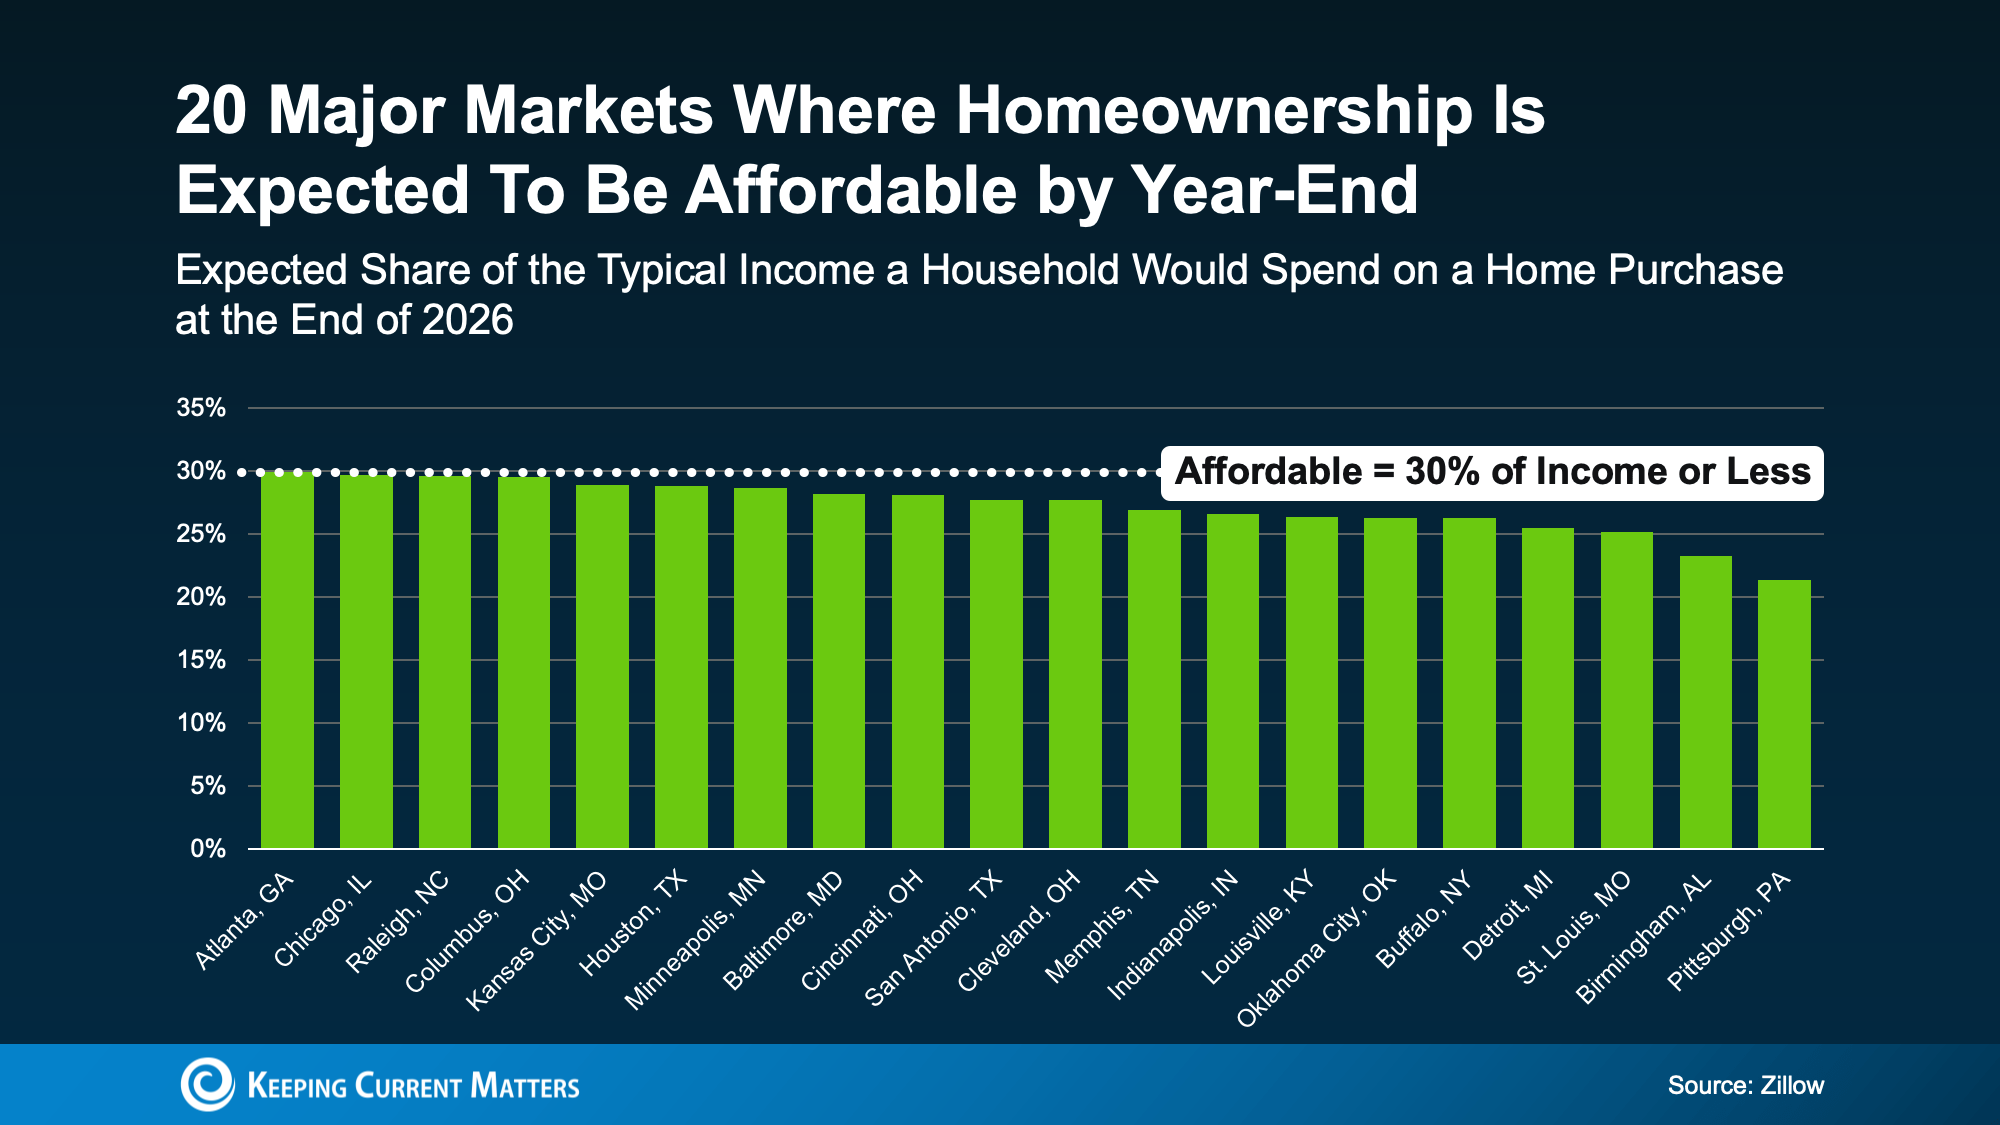
So how much will affordability improve, and where will it show up first? In some places, the difference could be noticeable. Zillow says some markets are expected to fall back under their affordability threshold (30% of income or less) by the end of the year (see graph below):
But you don’t have to live in one of those specific markets, and you may not have to wait until year-end to see improvement. Many areas are already trending in a better direction.
That’s why your next best step is local: talk to a real estate agent who understands what’s happening in your market. The national headlines don’t always reflect what’s going on neighborhood by neighborhood, and you might be closer to buying than you think.
Conclusion
For the first time in a while, home affordability is easing, and that’s an important shift for buyers.
And because the pace of improvement varies by location, understanding what’s changing locally can make all the difference. If you want to see how these trends are playing out where you live, connect with a local real estate agent to talk through your options.
Mortgage Rates Just Hit a 3-Year Low. Does It Matter in 2026?
If you’ve been watching mortgage rates and waiting for a “better time” to buy, here’s your chance. Rates just dipped below 6% for the first time in more than three years. Even modest rate movement can change what you can afford, how competitive you can be, and whether buying feels realistic again, especially if last year’s higher rates pushed you to the sidelines.
With rates finally easing up into 2026, here’s a fresh take on why lower mortgage rates are still a big deal, plus what to do next if you’re thinking about making a move.
Why Mortgage Rates Impact More Than Just Interest
A mortgage rate isn’t just a number on a lender’s website. It shapes the entire homebuying experience because it affects:
- Your monthly payment
- How much home you can qualify for
- Your comfort level with your budget
- How competitive your offer can be
When rates jump, affordability tightens fast. That’s why many buyers (especially first-time homebuyers) feel the pinch first. When rates ease, the reverse happens: budgets get a little more breathing room, and choices open up.
The “One-Point” Difference That Changes the Math
One of the easiest ways to understand why rate declines matter is to look at a simple example.
When rates are closer to 7%, monthly payments rise sharply. When rates move closer to 6% (or below), payments can drop meaningfully. On a typical loan amount, that can translate into hundreds of dollars per month in savings compared to the higher-rate environment.
That difference can help you:
-
Stretch your budget without stretching your lifestyle
-
Consider more homes in a neighborhood you actually want
-
Keep cash available for repairs, furnishing, or future goals
In practical terms, the change isn’t just “cheaper interest.” It can be the difference between compromising on your wish list and finding a home that fits.
What Lower Rates Can Unlock for Buyers
When borrowing costs come down, three things usually happen for homebuyers:
1) Lower monthly payments
A lower rate can reduce the monthly principal-and-interest payment, which helps many buyers feel more confident about moving forward.
2) More buying power
When the payment drops, you may qualify for more home at the same monthly budget. That can mean a better location, an extra bedroom, or a property that needs fewer updates.
3) Stronger offers without overextending
More budget flexibility can help you compete without taking on a payment that makes you uncomfortable. That matters in markets where inventory is still tight and desirable homes move quickly.
Why This Can Bring More Buyers Off the Sidelines
Rate changes don’t only affect you. They affect everyone who has been waiting, too.
Industry research suggests that when rates sit around certain thresholds, millions more households can afford a median-priced home. In fact, research from the National Association of Realtors (NAR) points to 5.5 million additional households being able to afford the median-priced home when rates are at 6% or below, and it estimates roughly 550,000 of those households could buy within the next 12 to 18 months.
That matters because it signals something important: pent-up demand can return quickly when affordability improves.
If you’re home-searching now (or preparing to), you may be able to act before competition fully ramps back up.
A Quick Reality Check: Rates Aren’t the Only Factor
Lower rates help, but they don’t magically make every home affordable. Your true monthly cost depends on several moving pieces, including:
-
Home price
-
Local inventory and competition
-
Property taxes
-
Homeowners insurance (which can vary widely by state and ZIP code)
-
HOA dues
-
Your down payment and credit profile
That’s why the smartest next step isn’t guessing. It’s running real numbers to figure out what “affordable” looks like for you.
What To Do Next If You’re Considering Buying
If you’ve been waiting for rates to improve, here’s a simple, practical plan:
-
Get pre-approved (not just pre-qualified).
Pre-approval gives you a clearer budget and shows sellers you’re serious. -
Calculate your comfortable payment range.
Decide what fits your life, not just what a lender says you can qualify for. -
Compare scenarios with your lender.
Ask for payment examples at different price points, down payments, and rate options. -
Watch inventory in your target neighborhoods.
The best “deal” is the home that works for your needs and your budget.
Conclusion
Mortgage rates easing from last year’s highs isn’t just an attractive headline. For many buyers, it can be the shift that turns “maybe someday” into “this could actually work.”
If you paused your search when rates were higher, it’s worth revisiting your numbers now. A quick conversation with a trusted lender can show what today’s rate environment means for your payment, your buying power, and your options.
If you’re thinking of buying, or need help finding a lender, reach out to us today. We can connect you with local agents and lenders to make your journey as simple as possible.
Expert Forecasts Point to Home Affordability Improving in 2026
If the last few years have felt like a constant tug-of-war between home prices, mortgage rates, and “Can we actually afford this?”, you’re not alone. Affordability has been the biggest obstacle for buyers (and a major source of hesitation for sellers), but the outlook for 2026 is more encouraging than what we’ve seen in a while.
In fact, affordability improved meaningfully in 2025, and many industry forecasts expect that progress to continue through 2026. The reason comes down to three forces shaping the market: mortgage rates, housing inventory, and home price growth.
1) Mortgage Rates: Lower Than the Peak, Likely Steadier in 2026
Mortgage rates have already eased from recent highs by nearly a full percentage point over the past year in some measures, and that matters more than most people realize. Even small rate shifts can change monthly payments, buying power, and which homes feel like realistic options.
What experts expect
Forecasts suggest rates may hover in the low 6% range through 2026, though the exact path depends on the broader economy, the job market, and Federal Reserve policy decisions. The key takeaway: rates are already lower than they were a year ago, which helps restore some breathing room for people planning a move in 2026.
What this means for buyers
- Lower rates can reduce monthly payments
- Improved buying power can make more listings qualify as “within reach”
- You may have more flexibility to negotiate when combined with rising inventory
What this means for sellers
- The market is adjusting to the idea that “rates in the 6s” may be the new normal
- If you need to move, it may be more feasible than it looks, especially if you’re sitting on substantial equity
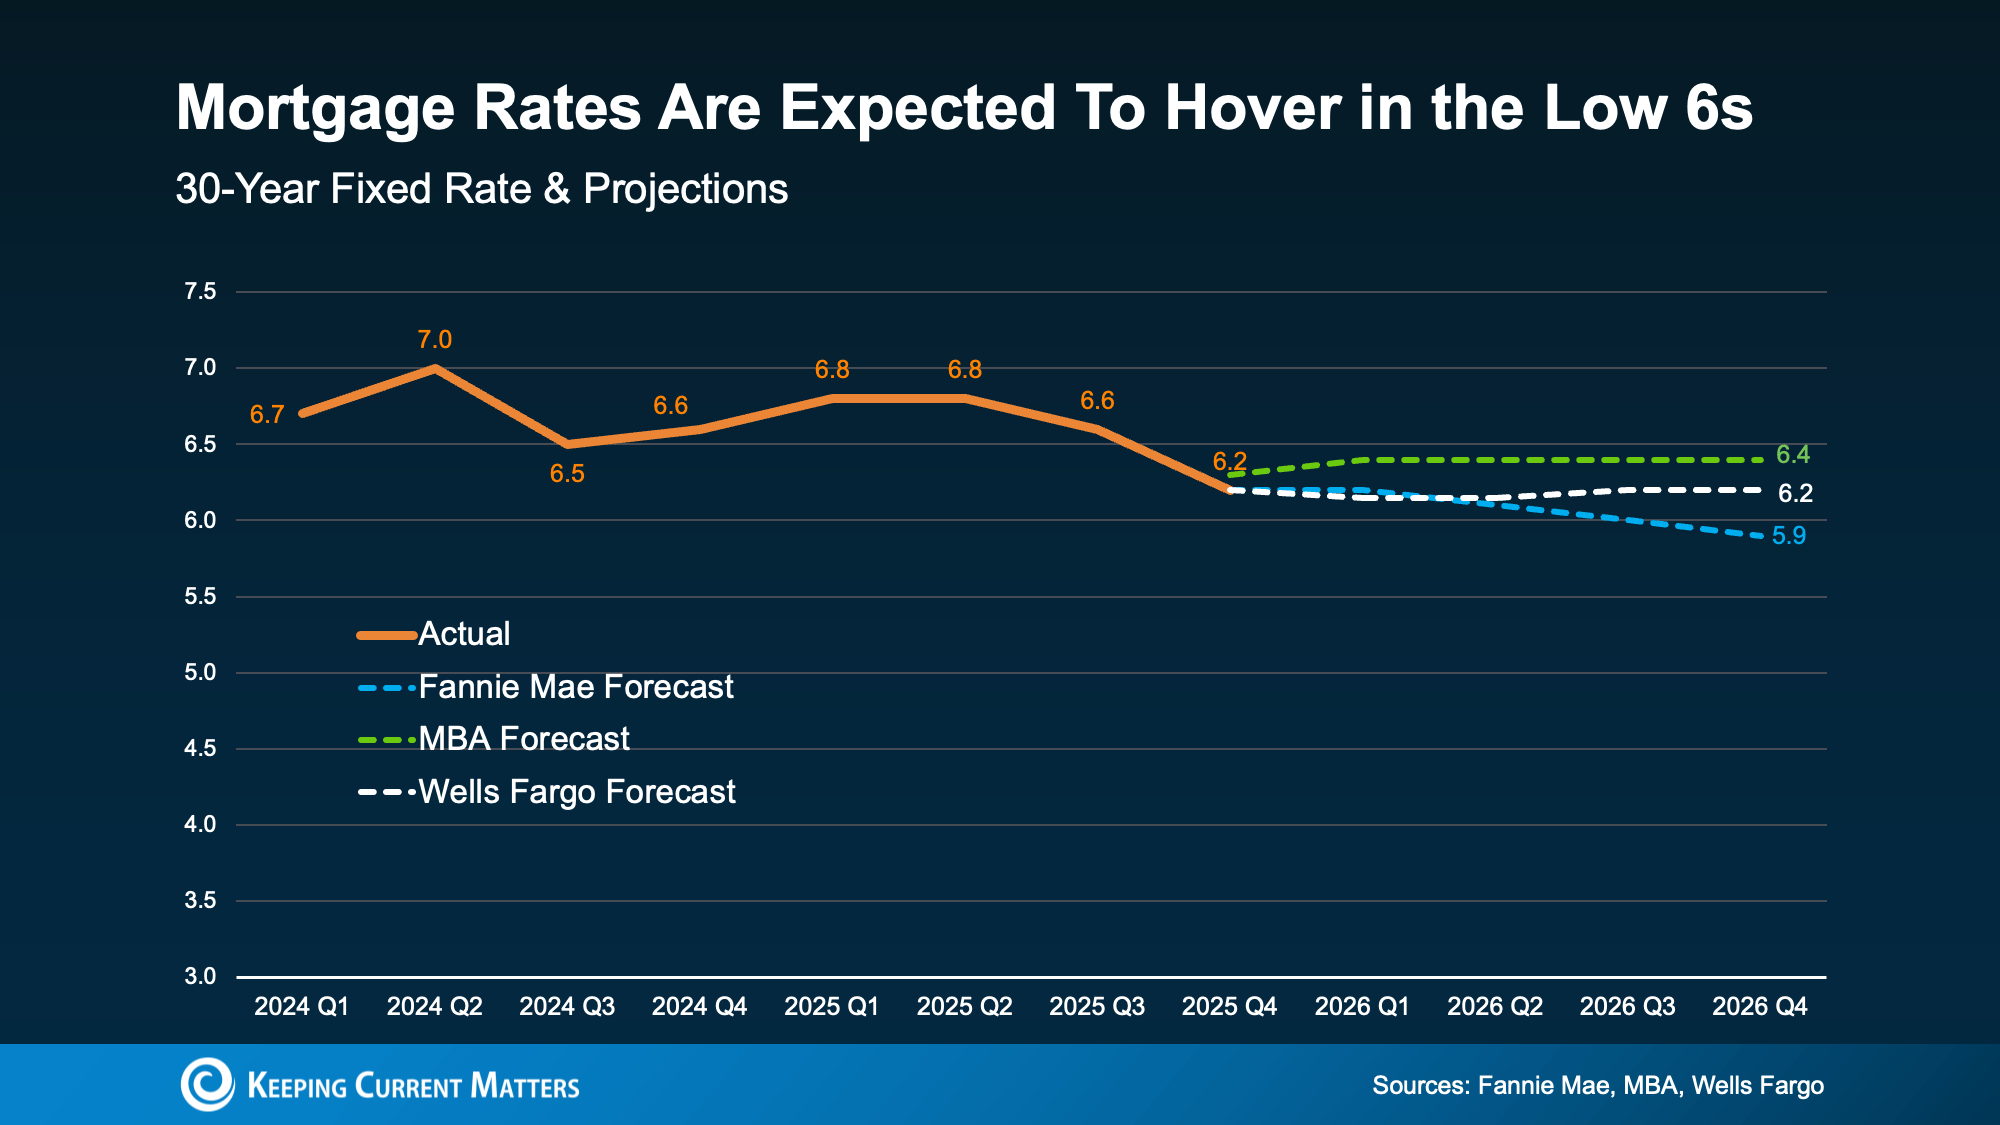
Experts expect mortgage rates to hover in the low 6s or drop even lower as the economy changes in 2026.
2) Housing Inventory: More Homes for Sale, More Leverage for Buyers
One of the biggest changes in 2025 was inventory finally moving in the right direction. With more homes available, buyers got something they haven’t had in years: options—plus more time to compare those options and negotiate.
Inventory is still expected to grow
After a meaningful rise of about 15% in 2025, forecasts call for continued growth in the supply of homes for sale in 2026 (though likely at a slower pace than the last big jump). Realtor.com economists, for example, project additional gains of about 8.9% in active listings this year.
What this means for buyers
- More choices (and fewer “take it or leave it” situations)
- Greater negotiating power—especially on homes that are priced too aggressively or need updates
What this means for sellers
- Pricing strategy becomes critical. In a market with more options, buyers compare everything.
- Strong presentation (clean, staged, repaired) matters more when competition increases
3) Home Prices: Still Rising Nationally, But at a More Sustainable Pace
Here’s what many headlines miss: increasing inventory tends to reduce upward pressure on prices, but it doesn’t automatically mean prices crash. Most national forecasts expect home prices to keep rising in 2026, just more slowly than the rapid spikes of the recent past. On average, experts predict home price growth of about 1.6% in 2026.
Why slower growth can be good news
More moderate appreciation helps buyers plan and budget with fewer surprises, while still supporting overall market stability.
But location is everything. Some areas may outperform the national average, while others could see flat or slightly declining prices depending on local supply, demand, and employment conditions. If you’re serious about a move, a local real estate agent can help you interpret what’s happening in your neighborhood, not just what’s happening nationally.
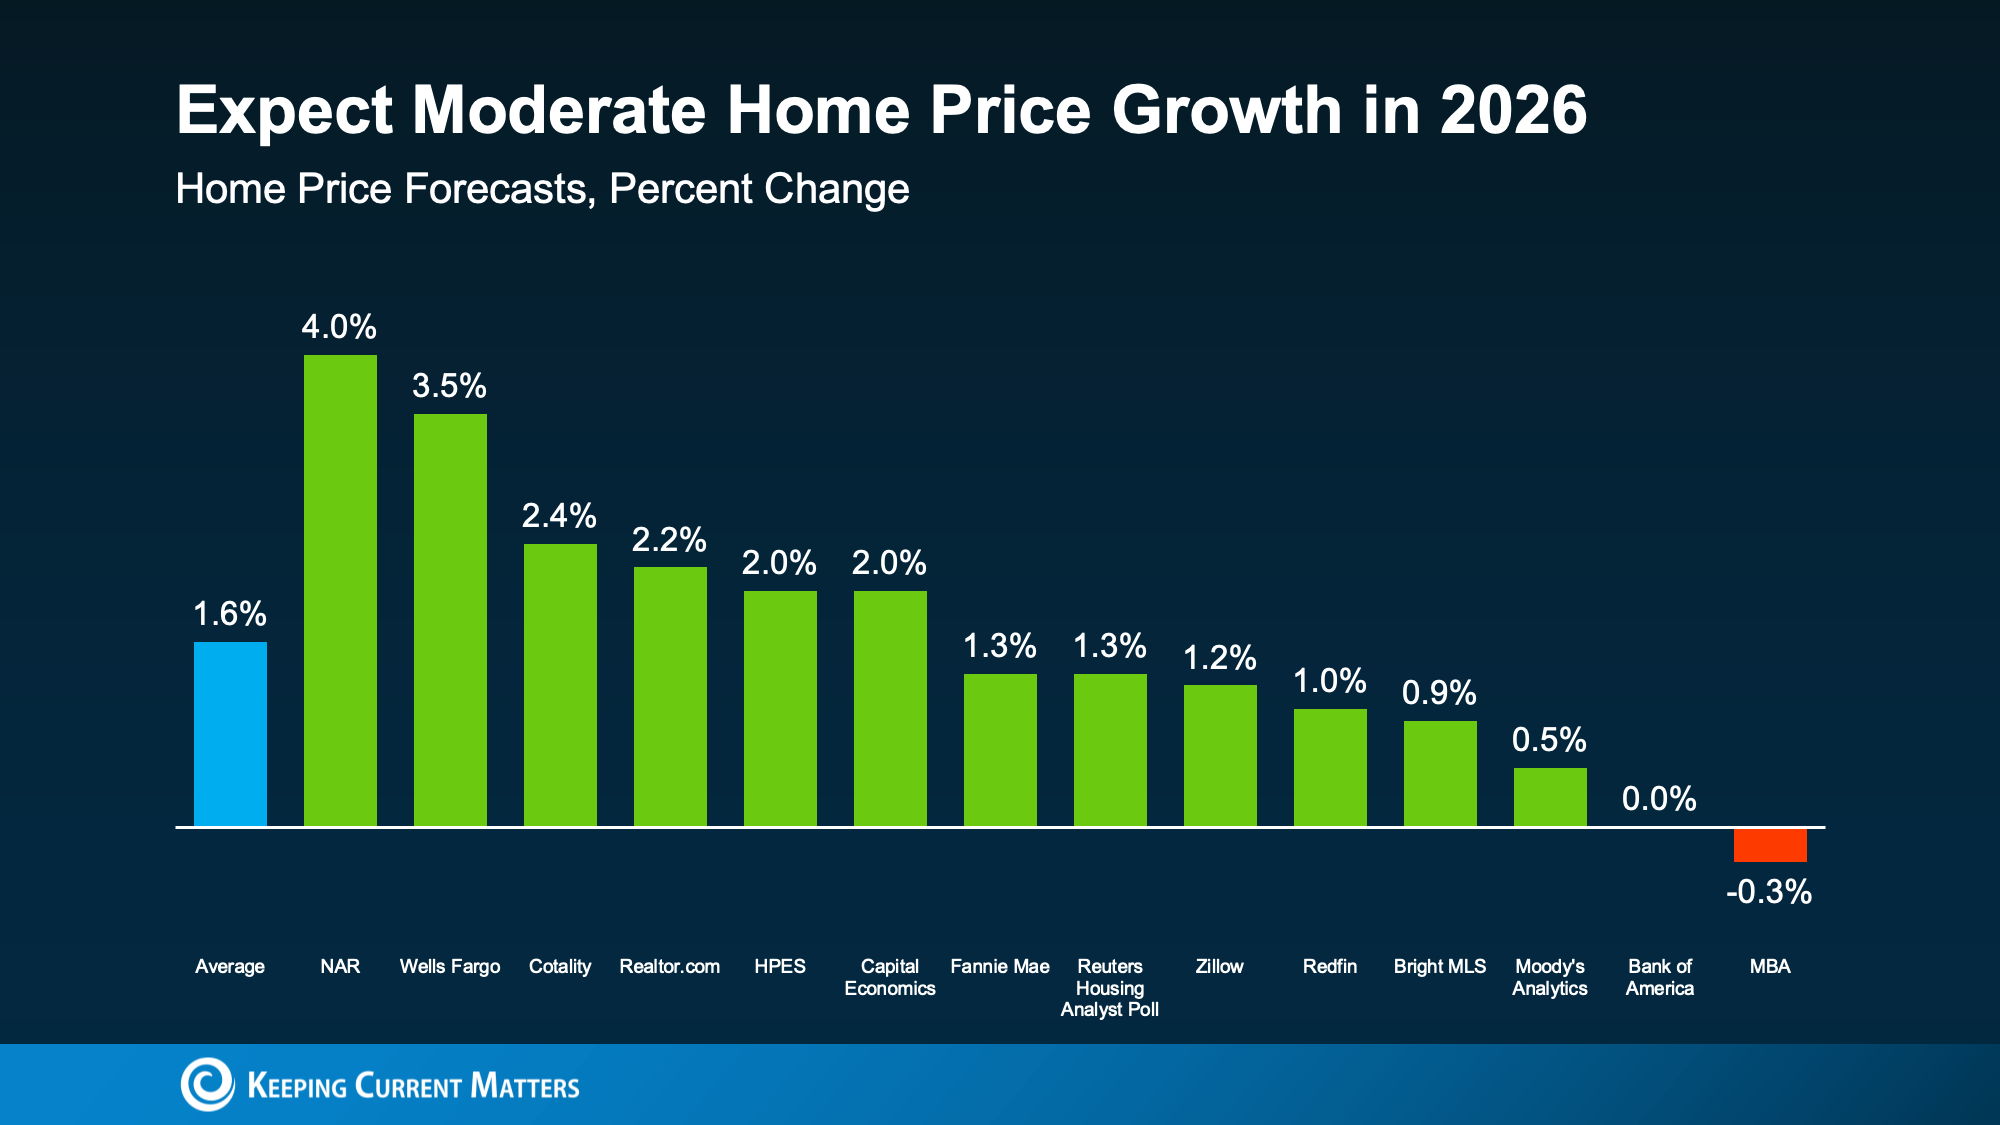
Home prices are expected to continue rising in 2026, though at a more moderate rate.
Will More Homes Sell in 2026?
When rates are lower than recent peaks, inventory is improving, and price growth is calmer, you get a healthier affordability equation. That’s why many experts expect more home sales in 2026, as both buyers and sellers find conditions easier to navigate.
As Zillow’s Chief Economist Mischa Fisher notes:
“Buyers are benefiting from more inventory and improved affordability, while sellers are seeing price stability and more consistent demand. Each group should have a bit more breathing room in 2026.”
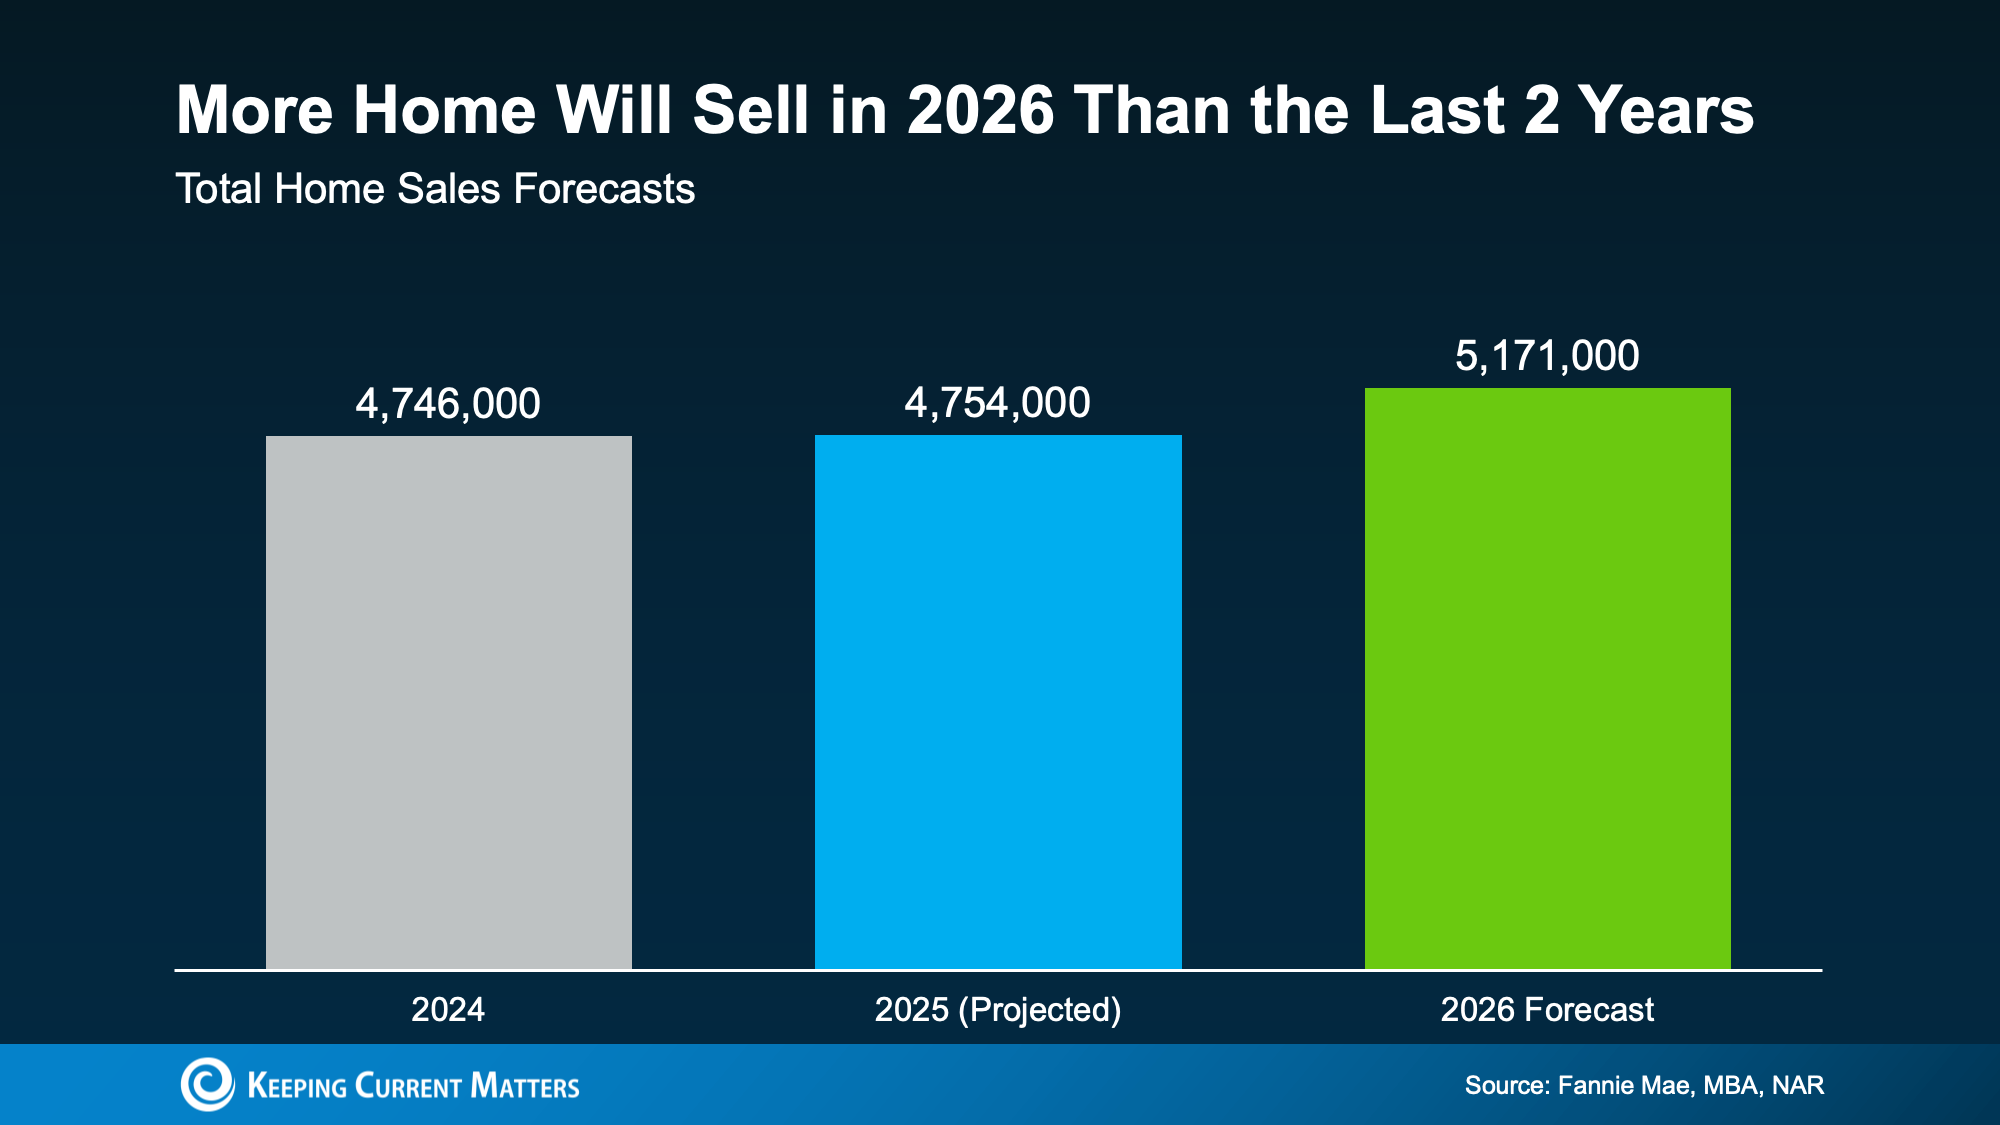
Increased affordability in 2026 has experts predicting higher home sales over the past two years.
2026 Could Feel More Balanced Than You’ve Seen in Years
Affordability won’t change overnight. But if current forecasts hold, 2026 is shaping up to be a year with:
- More balance between buyers and sellers
- More predictability in pricing
- More flexibility in negotiations
- More opportunity for people who’ve been waiting on the sidelines
If you’re thinking about buying or selling in 2026, the smartest next step is to get hyper-local: understand neighborhood pricing trends, inventory levels, and what buyers are actually paying (and negotiating) right now.
Ready to start but aren’t sure how? Reach out to us today to connect with an expert agent for all the latest info on your local market.
Renting vs. Buying: Which Home Option Is Right for You?
Between stubborn mortgage rates and rising home prices, you’ve probably mulled over renting vs. buying a home. In market conditions like these, renting and waiting to buy can feel like your only realistic option. This can be the truth in many cases, and buying before you’re ready can be a costly mistake.
But the short-term savings of renting can sometimes trap you in a cycle, preventing you from making wealth-building investments. Over time, this can actually end up costing you more than buying a home early and slowly building equity. Unsurprisingly, a recent survey from Bank of America found that 70% of prospective homebuyers feel renting could hinder their financial future.
Ultimately, the pros and cons of renting and buying come down to your own short-term and long-term financial goals. If you’re feeling torn over whether you should nest or invest, take these major differences into account to decide.
Homeownership Builds Your Wealth Over Time
Apart from giving you your own place to live, homeownership grants the important bonus of building your wealth over time. This is because home prices usually rise as time goes on, meaning waiting longer to buy costs you more. This isn’t always true of every housing market, but the general national trend tends to speak for itself.

The average home sale price has more than tripled in the past 30 years.
Even better, your home equity also grows over time when you’re a homeowner. Equity is the difference between what your home is worth and what you still owe on your mortgage. Your equity grows with each mortgage payment you make, and this builds your net worth over time.
According to the Federal Reserve, the average homeowner’s net worth is nearly 40 times greater than that of a renter. That’s a life-changing difference, and seeing it represented visually really drives the point home.
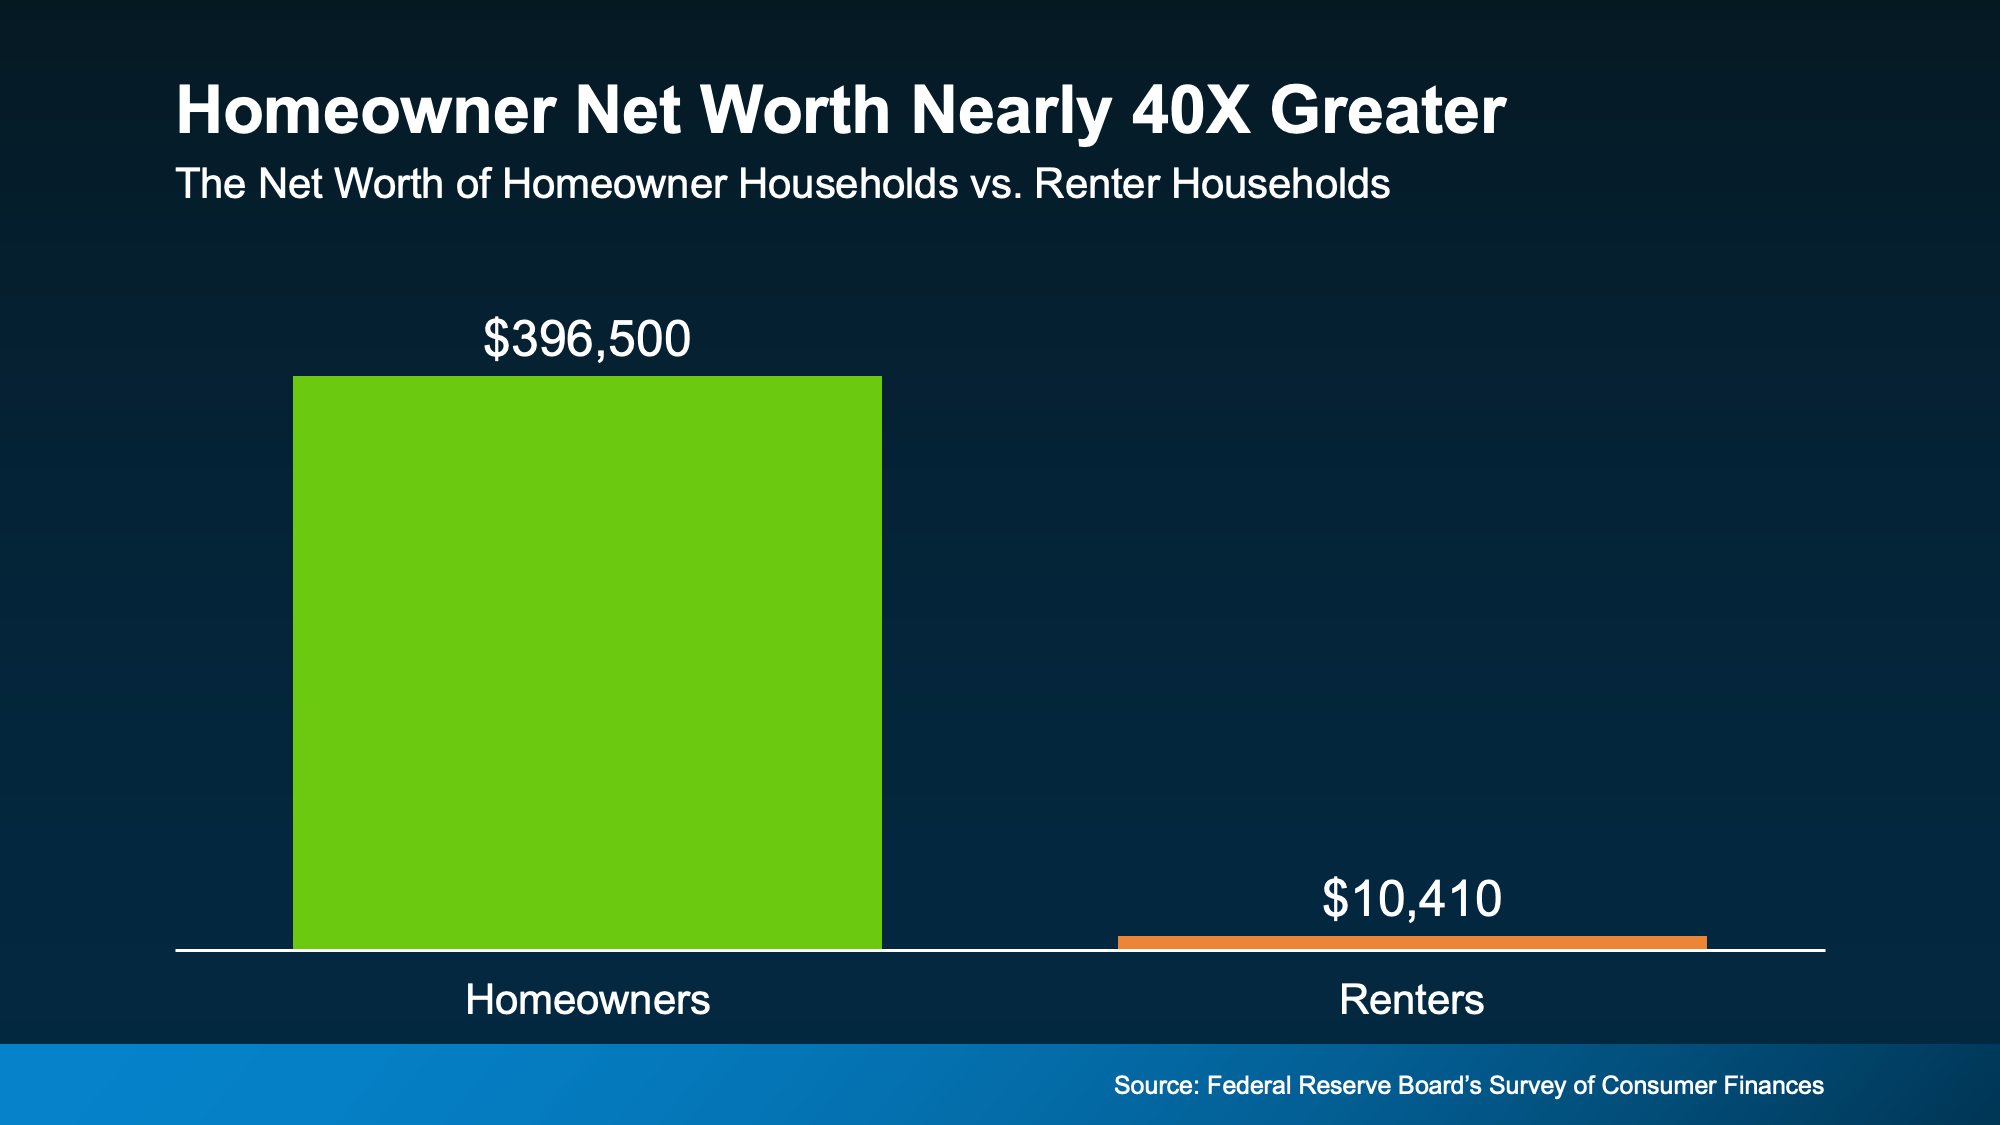
The average net worth of a homeowner household is almost 40X greater than that of a renter household.
This massive difference in personal wealth is just one of the reasons that Forbes says:
“While renting might seem like [the] less stressful option . . . owning a home is still a cornerstone of the American dream and a proven strategy for building long-term wealth.”
Renting Helps You Save in the Short Term
Compared to homeownership, renting offers lower monthly payments and the freedoms of relatively negligible commitment and responsibility. This often makes renting feel like the safer option, and it usually is, at least in the short term. But in the long term, renting can land you in a trap that prevents you from building real wealth.
Rent tends to rise along with home prices, and this has been true for decades. Rental costs have been somewhat stable recently, but they almost never trend downward. This trap of paying increasing rent without building wealth can make buying a home feel impossible.
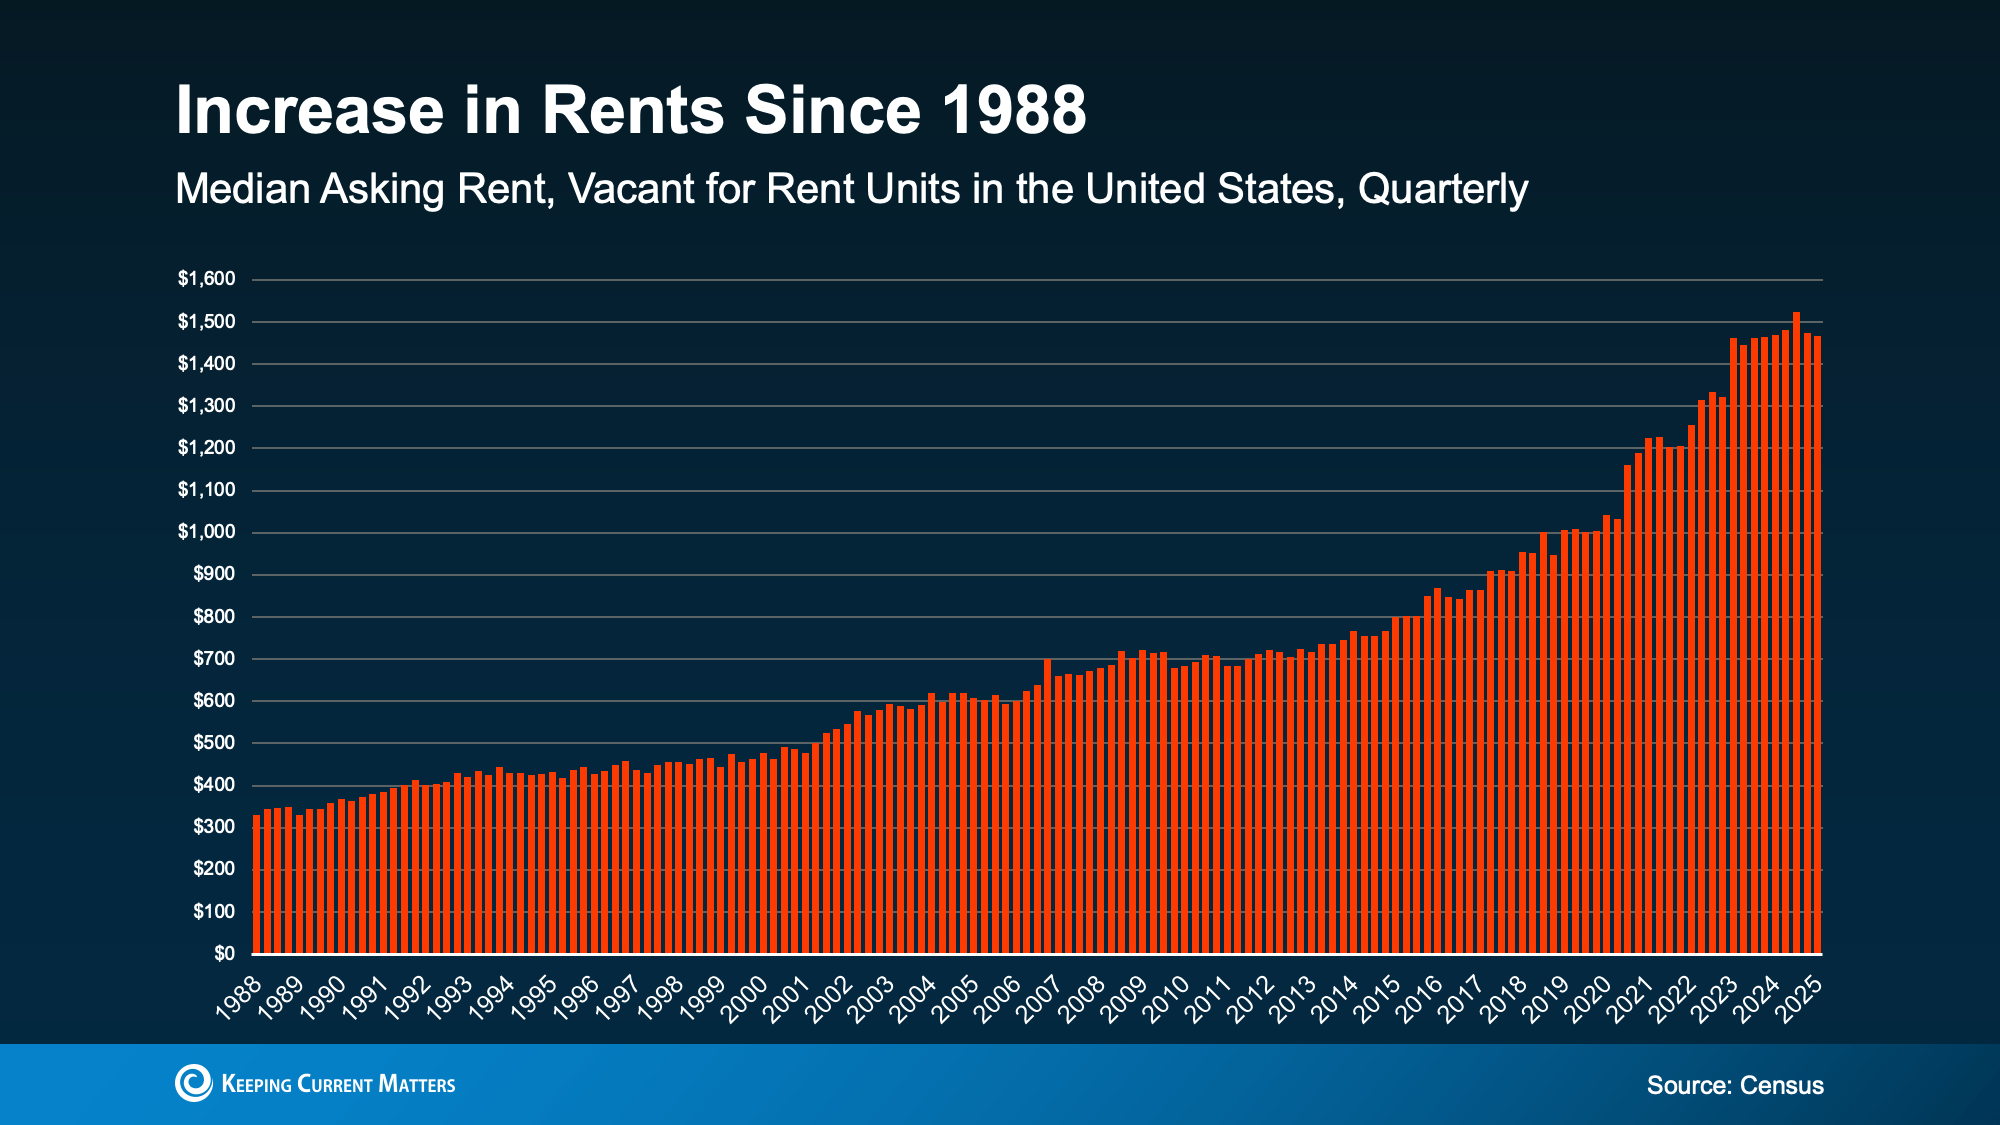
Like home prices, rental costs have risen dramatically in the past several years.
Financial uncertainty like this can have a real, lasting impact on any of your financial decisions. In the same Bank of America survey, 72% of potential buyers said they worry rising rent could affect their current and long-term finances.
Rent money doesn’t come back to you, and that means it doesn’t grow your wealth. The only mortgage it’s paying is your landlord’s.
So, whether you’re renting or owning, you’re paying off a mortgage. The question is: whose mortgage do you want to pay?
Renting vs. Buying: What Really Matters
Here’s another way to look at renting vs. buying. Rent money is gone once you pay it. Payments toward your own house build equity, like a savings account you can live in. Obviously, buying comes with higher upfront costs and more long-term responsibility. But the reward is a stable investment that grows over time. And while buying a home often feels out of reach, a solid plan can get you there.
As Realtor.com Senior Economist Joel Berner explains:
“Households working on their budget will find it much easier to continue to rent than to go through the expenses of homeownership. However, they need to consider the equity and generational wealth they can build up by owning a home that they can’t by renting it. In the long run, buying a home may be a better investment even if the short-run costs seem prohibitive.”
Conclusion
Renting may be cheaper in the short term, but it can cost you more over time without building your wealth. If you’re weighing the pros and cons of renting vs. buying, consider your long-term financial goals. Short-term saving can trap you in an endless cycle of renting, but buying without planning can be financially overwhelming.
If you’re ready to make the leap from renting into buying a home, contact us today. We’d be happy to connect you with a local agent who can make your dreams a reality.