Facebook
 X
 Pinterest
 Copy Link
Buying a Home With Student Loans: What You Need to Know
Student loans are back in the news and might be weighing on your mind if you’ve been following the headlines recently. If you’re wondering what your student debt means for your homeownership plans, there’s one important thing to remember:
Having student loans does not automatically mean you can’t buy home.
The Biggest Myth About Student Loans and Mortgages
Many first-time buyers believe they have to completely pay off their student loans before they can qualify for a mortgage.
In most cases, this isn’t true.
According to a Redfin article, student loans are usually evaluated by lenders in the same way as other standard debts, such as car payments or credit cards:
“Yes, you can get a mortgage with student loan debt. Lenders primarily assess your debt-to-income (DTI) ratio, which compares your monthly debt payments, including student loans, to your gross monthly income. Having student debt doesn’t automatically disqualify you if your DTI is within acceptable limits.”
A student loan on your credit report is not an automatic disqualifier. Instead, lenders look at your broader financial profile, including your:
- Income
- Monthly debt payments
- Credit history
- Overall financial situation
Your student loans matter, but they don’t tell a lender the whole story.
Many Homebuyers Have Student Loan Debt
To really put things into perspective, data from the National Association of Realtors (NAR) proves that you can have student debt and still buy a home.
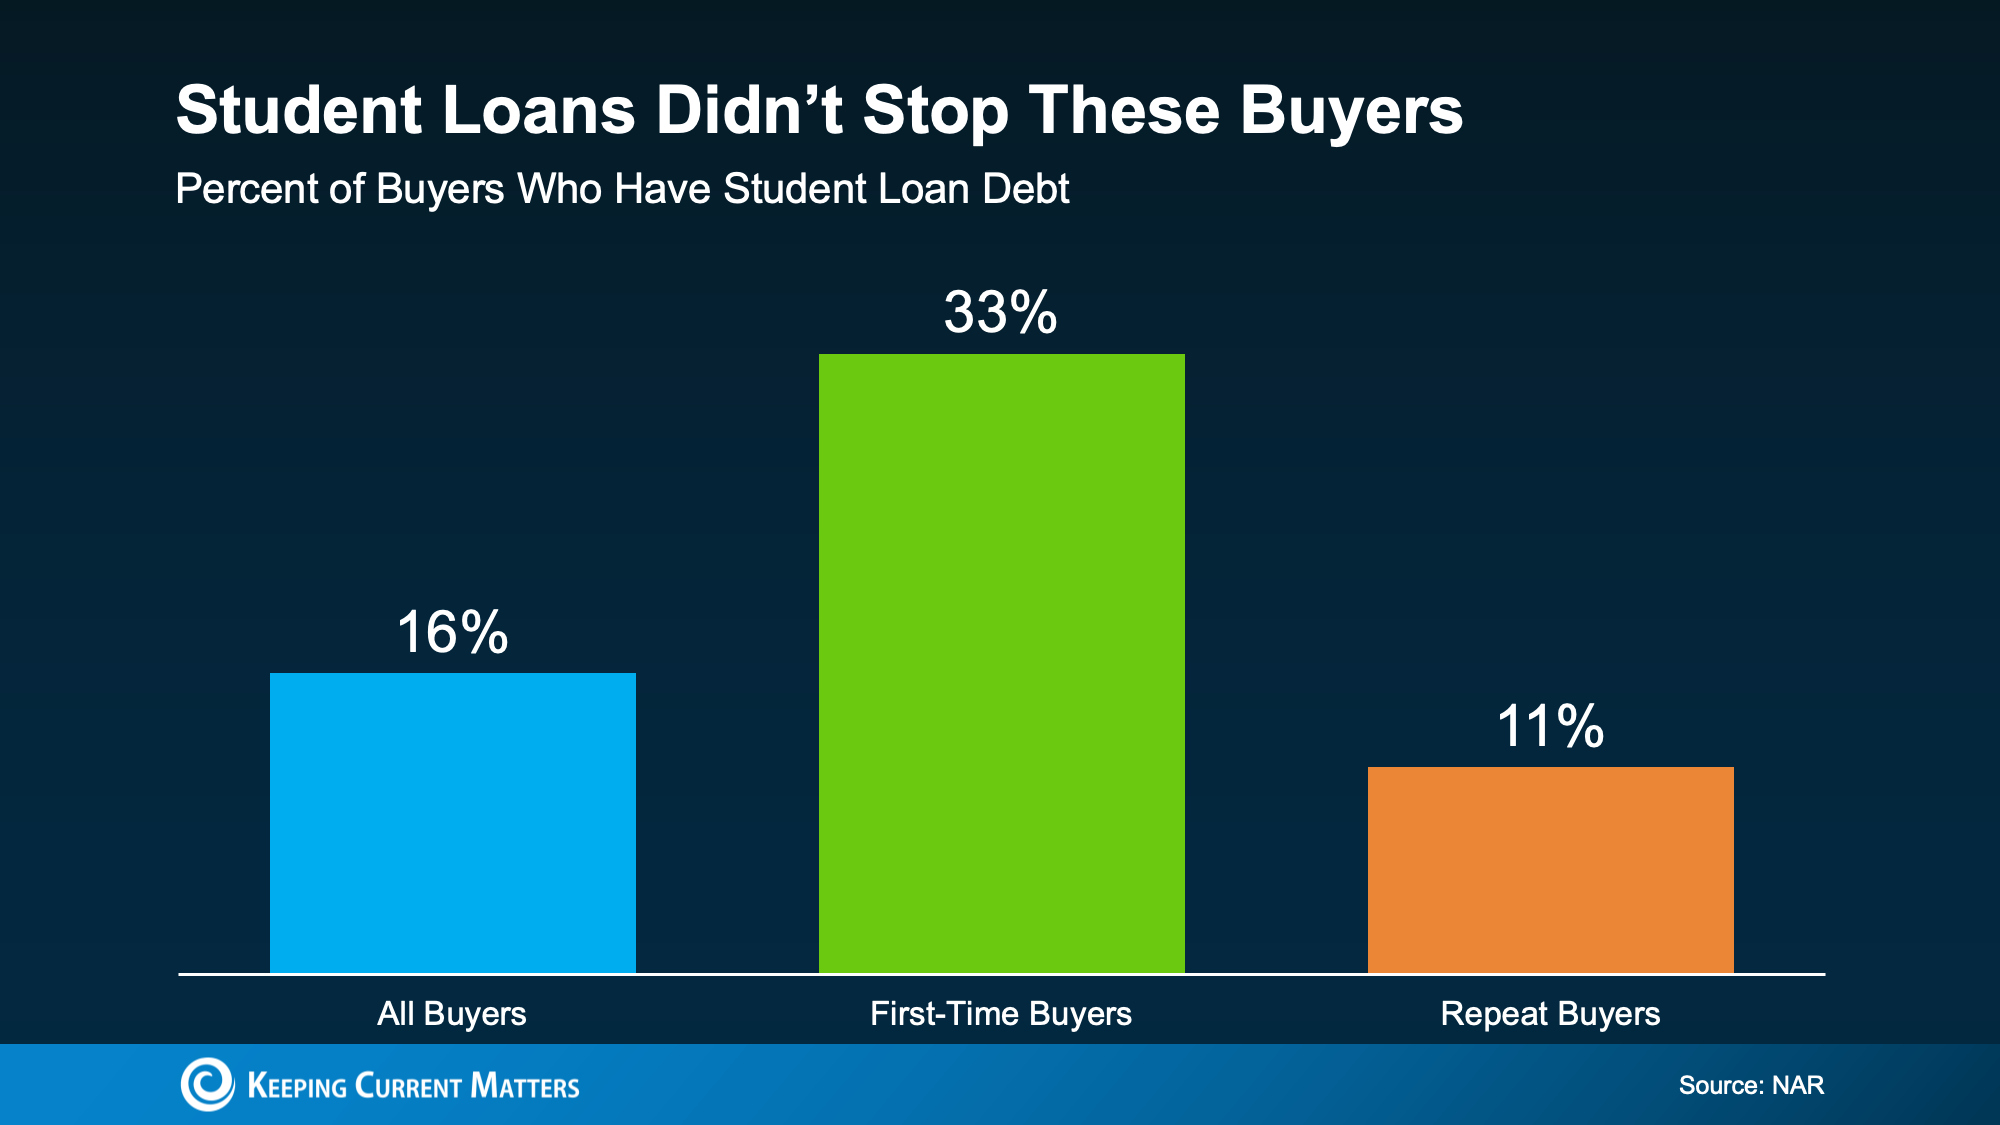
According to NAR’s research:
-
33% of first-time homebuyers still had student loan debt when they purchased their home.
-
That translates to 1 out of every 3 first-time buyers.
-
The median amount of student loan debt they owed was $30,400.
Let this reassure you that people are successfully buying homes with student debt every single day. Carrying student loans may affect how much you can borrow, but it doesn’t mean homeownership is beyond your reach.
Explore Your Mortgage Options First
A lot of potential buyers trip themselves up right at the starting line. They assume the worst regarding their loan eligibility and never check what they could actually qualify for. But your financial situation is unique and deserves some exploration.
If your income is steady and your overall finances are in decent shape, buying a home could be far more realistic than you think. The only way to know is to review the numbers with a qualified mortgage professional. You might discover you’re much closer to buying a house than you thought.
Bottom Line
Student loans don’t have to stop you from owning a home. If you’ve been putting off your homebuying plans because of debt, talk to a lender about your options. It may not be the roadblock you think it is.
Contact our team today to connect with trusted local lenders and start exploring your real estate options.
Down Payments Are at Their Lowest Since 2021
Saving for a down payment is often the biggest obstacle to buying a home. With the challenges of affordability today, it’s easy to wonder how anyone manages to save enough cash right now.
But here’s some good news: some buyers are getting into homes with smaller down payments than they may have expected.
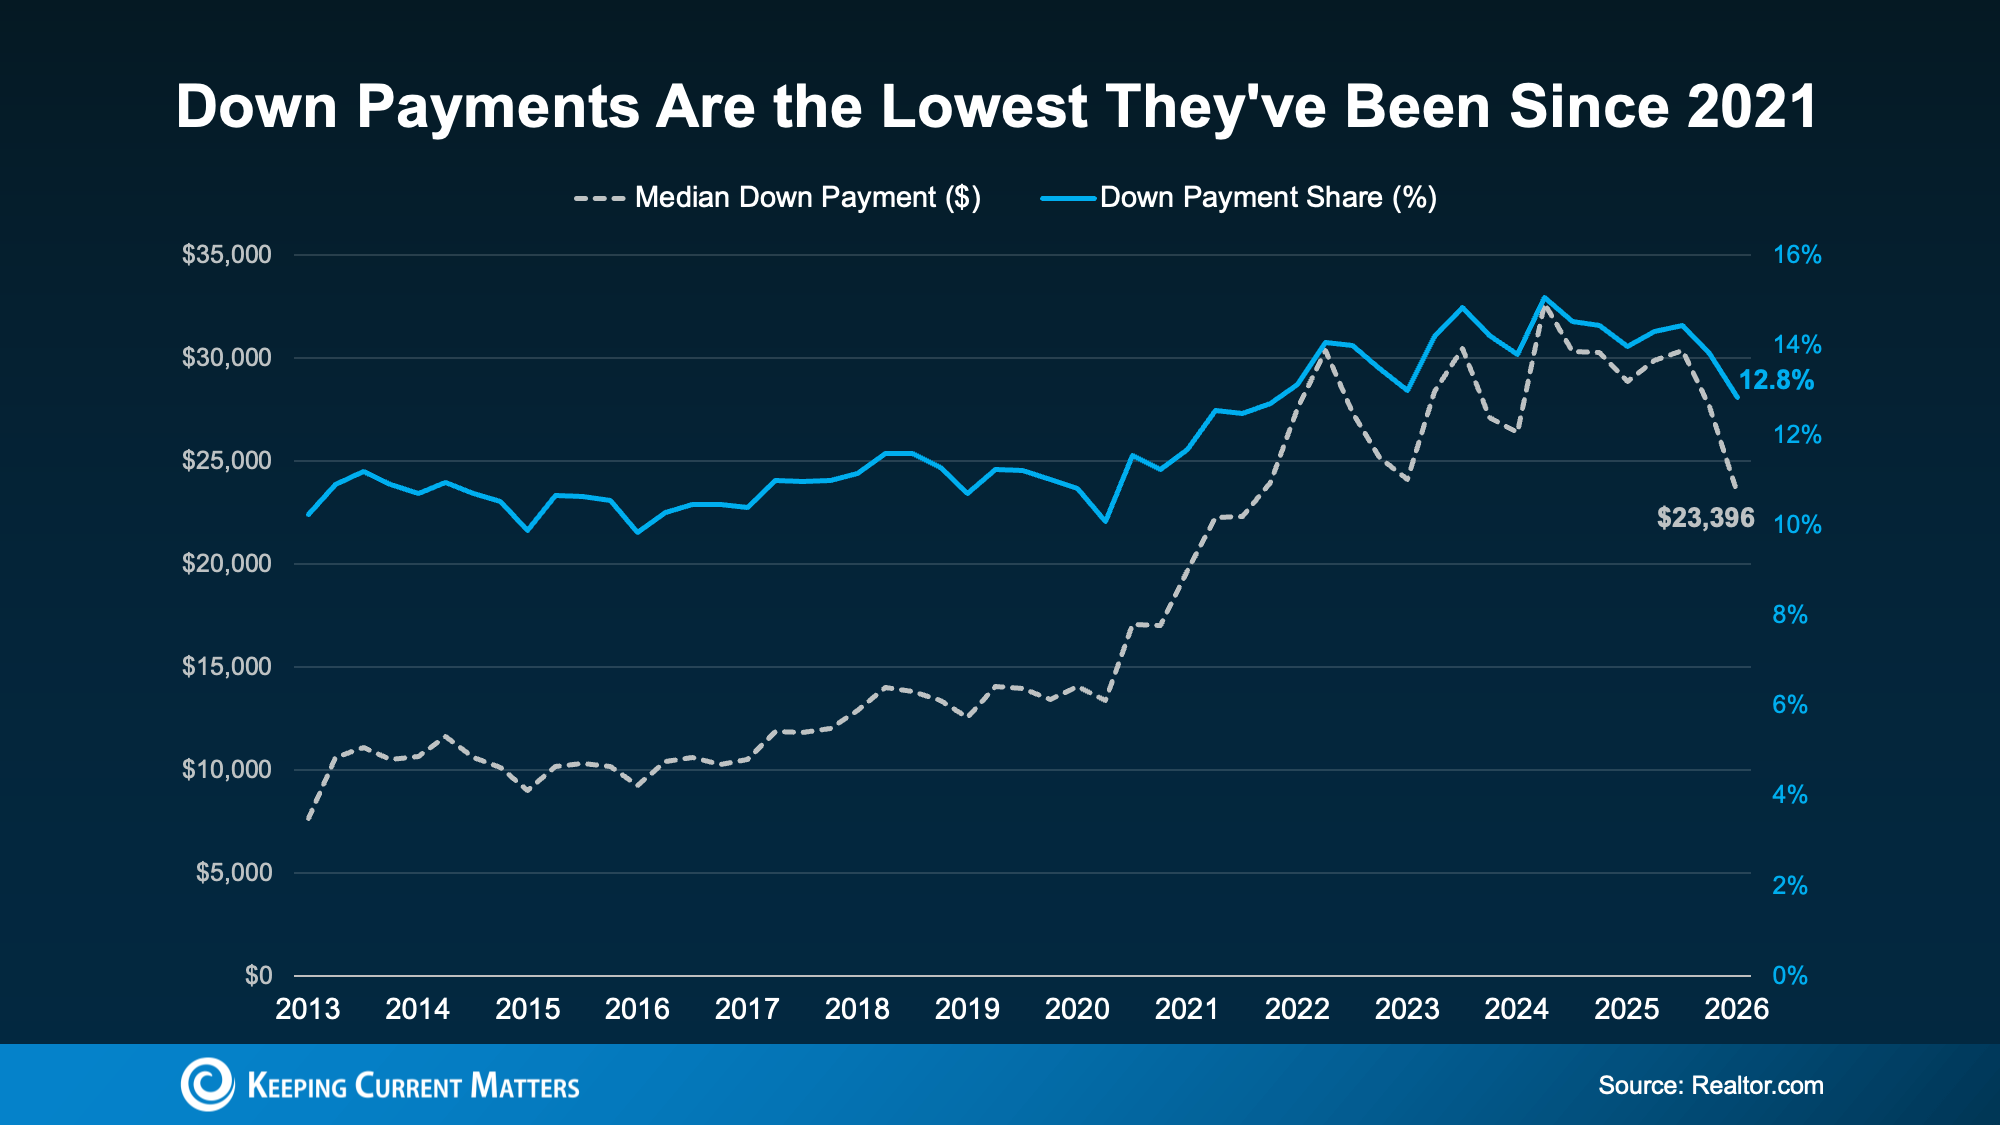
According to Realtor.com, the typical buyer put down about $23,400 in early 2026. That’s about $5,000 less than the year before, a 19% year-over-year drop. It’s also the lowest typical down payment level since 2021.
3 Reasons Why Down Payments Are Shrinking
Why are buyers putting less money down today? Three major shifts in the housing market are driving this trend:
-
Less Competition Between Buyers
In the most competitive markets of the past few years, some buyers felt pressure to put more money down to make their offers stand out.
Today, conditions are more balanced in many areas. With less intense competition, buyers are less pressured to offer a huge down payment to make an offer stand out.
-
Home Price Growth Has Moderated
Your down payment is typically based on a percentage of the purchase price. When home price growth slows or levels off, the dollar amount needed for a down payment can shift too.
In many markets, prices have cooled from the rapid pace seen in recent years. Some areas have even seen slight price dips. That can help reduce the upfront amount some buyers need to save.
-
More Buyers Are Using Lower Down Payment Loan Options
More buyers are also turning to loan programs that often require less money upfront. Government-backed loan options, like FHA loans and VA loans, often allow eligible buyers to purchase with a lower down payment or, in some cases, no down payment. According to Mortgage Professional America, FHA loans have made up more than 24% of purchase mortgages for five straight quarters, while VA loans recently reached their highest share in more than a decade.
Of course, not every buyer will qualify for every program, and any down payment is a huge amount of money to save. To make up the difference, buyers are relying on two things: payment assistance programs and family support.
Financial Help You May Not Know You Qualify For
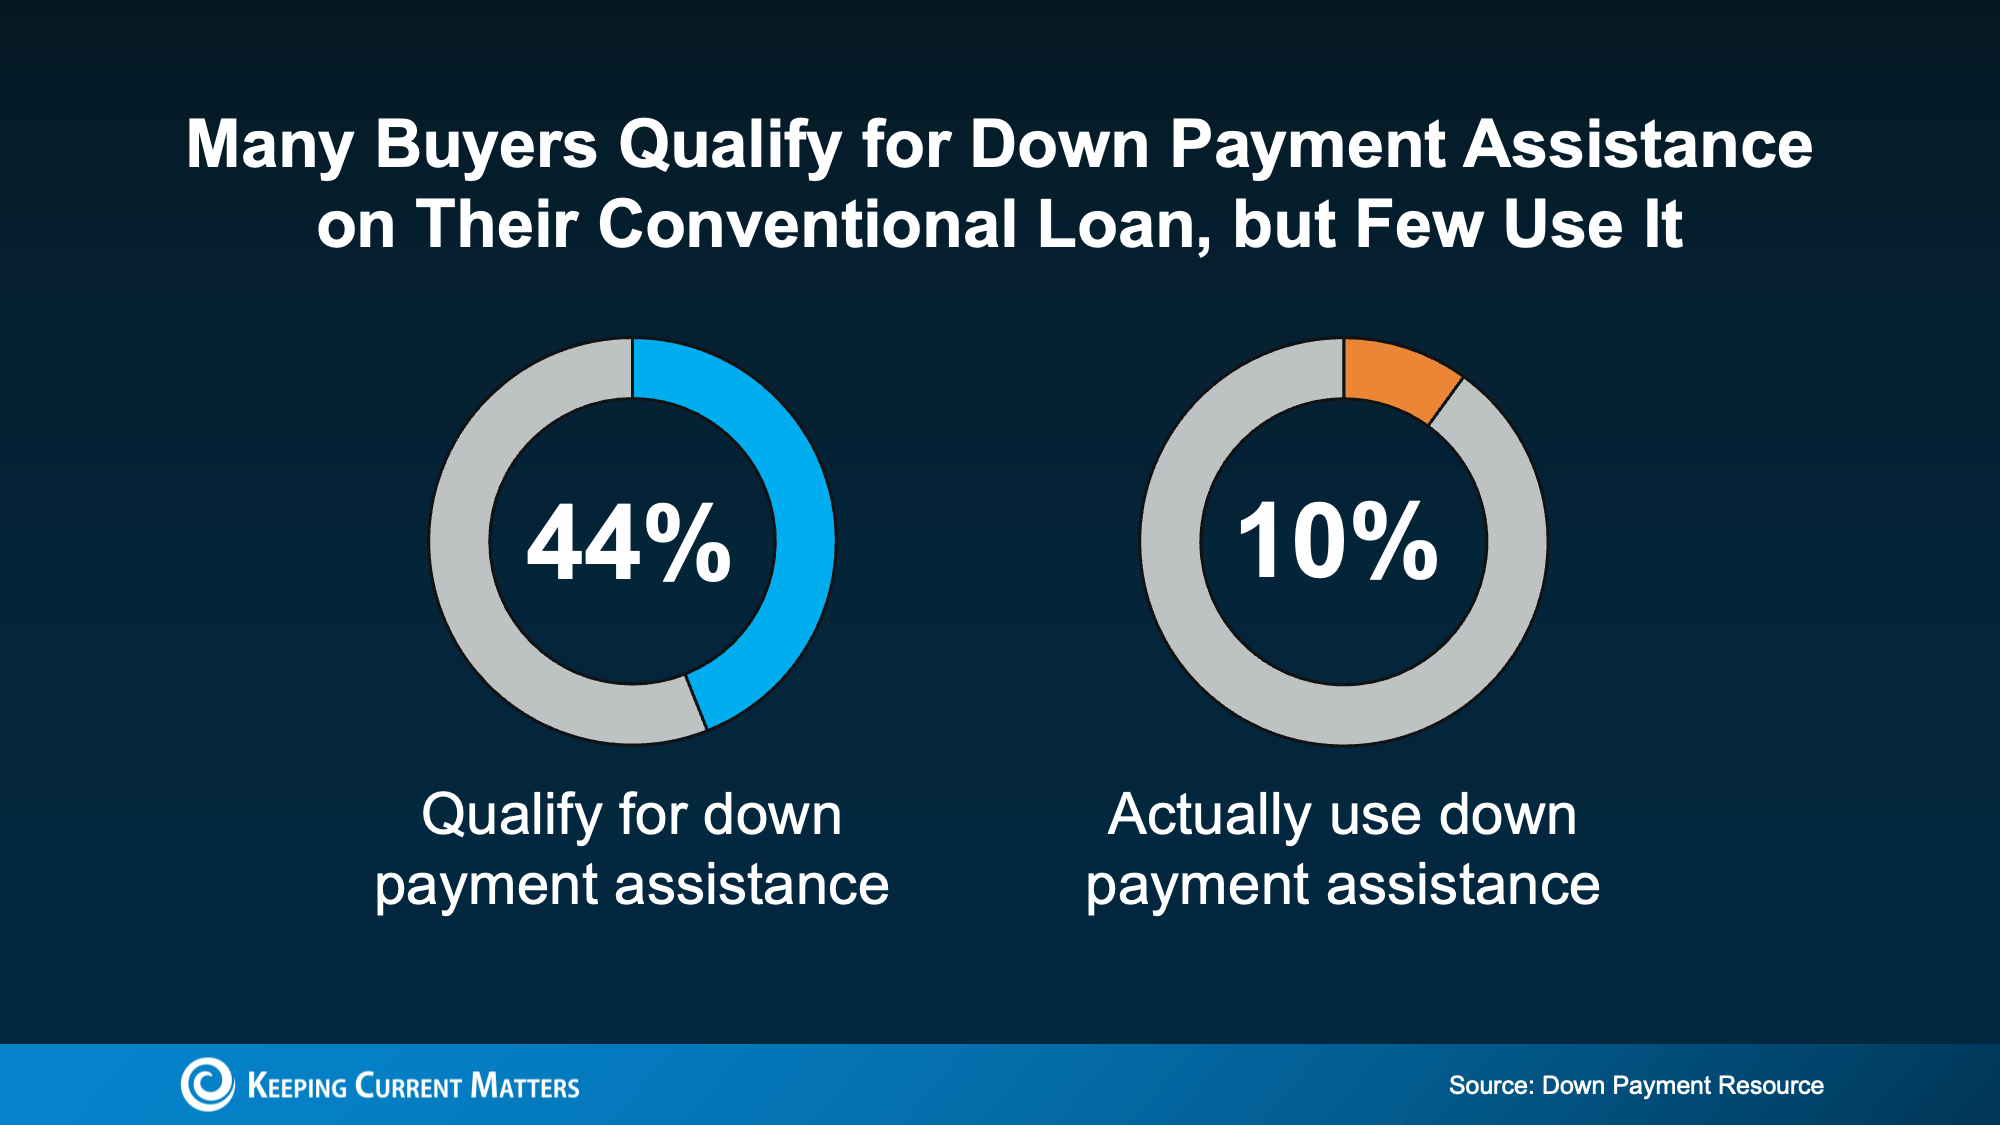
Down payment assistance is one of the most overlooked resources in real estate. A study by the Urban Institute and Down Payment Resource looked at the 10 largest U.S. metros and found that nearly 44% of recent buyers already qualified for a down payment program. Surprisingly, only 10% of those buyers actually used the help when closing on their loan.
There are more options available than many buyers realize. According to Down Payment Resource:
-
There are more than 2,600 down payment assistance programs available.
-
More than half (62%) are designed specifically to help first-time buyers.
-
38% have no first-time buyer requirement, meaning you may qualify even if you’ve owned a home before.
-
62% are open to buyers earning $100,000 or more.
So, don’t assume you’re priced out of a home or ineligible for help. A lender or knowledgeable real estate professional can help you ask the right questions and explore programs that may fit your situation.
A Helping Hand from Loved Ones
A growing number of buyers are also getting help closer to home. Research from Veterans United shows about 59% of parents have provided or plan to provide financial support to help their child buy a home.
That support usually goes toward the down payment, followed by helping the buyer qualify for a mortgage and covering closing costs.
Chris Birk, VP of Mortgage Insight at Veterans United, explains it this way:
“For many families, helping a child buy a home has become less of an optional gesture and more of a practical response to today’s affordability challenges.”
Not everyone has family or loved ones who are able to help. But for buyers who do, it can speed up how quickly they’re able to buy a home.
Bottom Line
Down payments are smaller than they’ve been in years, opening the door for more buyers to enter the market. Between down payment assistance programs and support from family, you may have more paths to homeownership than you realize.
Always consult with a trusted mortgage professional to review your financial situation. If you’re ready to start exploring neighborhoods and discussing your goals, contact our brokerage today to connect with an experienced local real estate agent.
Smaller Homes, Bigger Value for Today’s Buyers
You might have started your home search with a simple picture in mind: a certain number of bedrooms, a spacious layout, maybe even a home office or dedicated workout room.
Then reality sets in. The homes that fit your budget may be smaller than what you originally imagined.
That’s a common experience for many buyers right now. Affordability is tight, and buyers are taking a closer look at what they truly need in a home. But going smaller doesn’t need to feel like a compromise.
In fact, smaller homes for buyers can offer real advantages in today’s market, especially when considering newer construction, condos, and communities designed with shared amenities.
Why Smaller Homes Are Getting More Attention
Smaller homes are not just a backup plan. They have become a more practical path for many buyers who want to balance comfort, location, and budget.
In fact, newly built homes have been getting smaller for years, and the median square footage of new single-family homes has generally declined since 2014, based on US Census data.
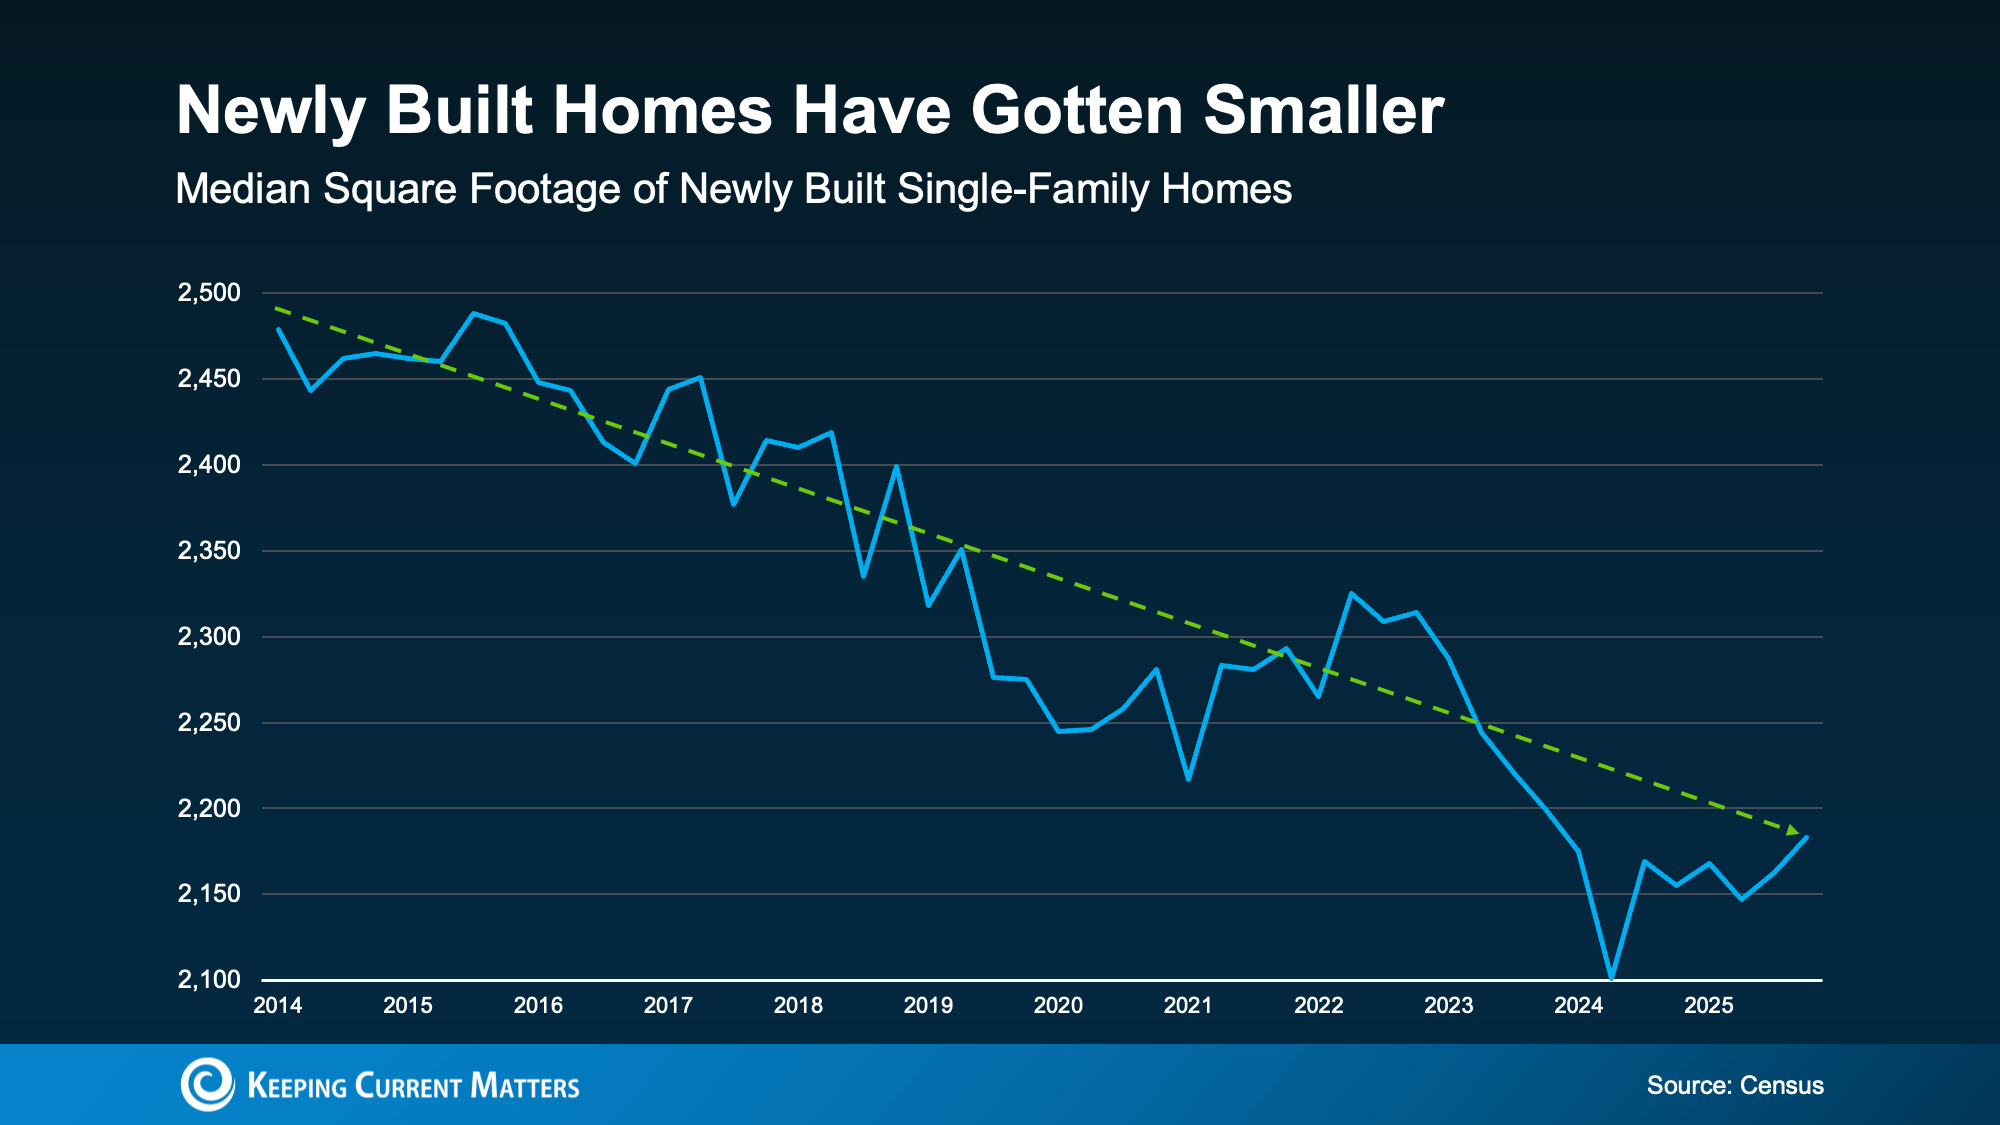
This shift makes sense. Builders pay close attention to what buyers are not only willing, but able to purchase. When affordability becomes a bigger concern, smaller floor plans can help bring new homes within reach for more shoppers.
Smaller New Construction Homes May Be Worth a Look
If the existing homes in your price range aren’t checking enough boxes, it may be time to explore new construction.
Many builders are focusing on smaller homes with modern layouts, updated finishes, and move-in-ready features. Smarter designs can make a smaller footprint feel more functional than an older home with a less efficient floor plan.
A smaller, newer home may offer:
- Modern appliances and finishes
- Open, practical layouts
- Less unused space
- Move-in-ready convenience
- A price point that may better fit your budget
Shifting buyer preferences are a big reason that new home prices have hit a five-year low. If you’ve ruled out new construction in the past, you want to take another look at what builders are offering in your area.
Condos Can Open Another Path to Homeownership
New construction isn’t available everywhere, and in some markets, it may still be outside your budget. That is where condos can be worth considering.
Condos are often smaller than single-family homes, which can help reduce the overall purchase price. According to data from the National Association of Realtors (NAR), the median condo price is lower than the median single-family home price in every region.
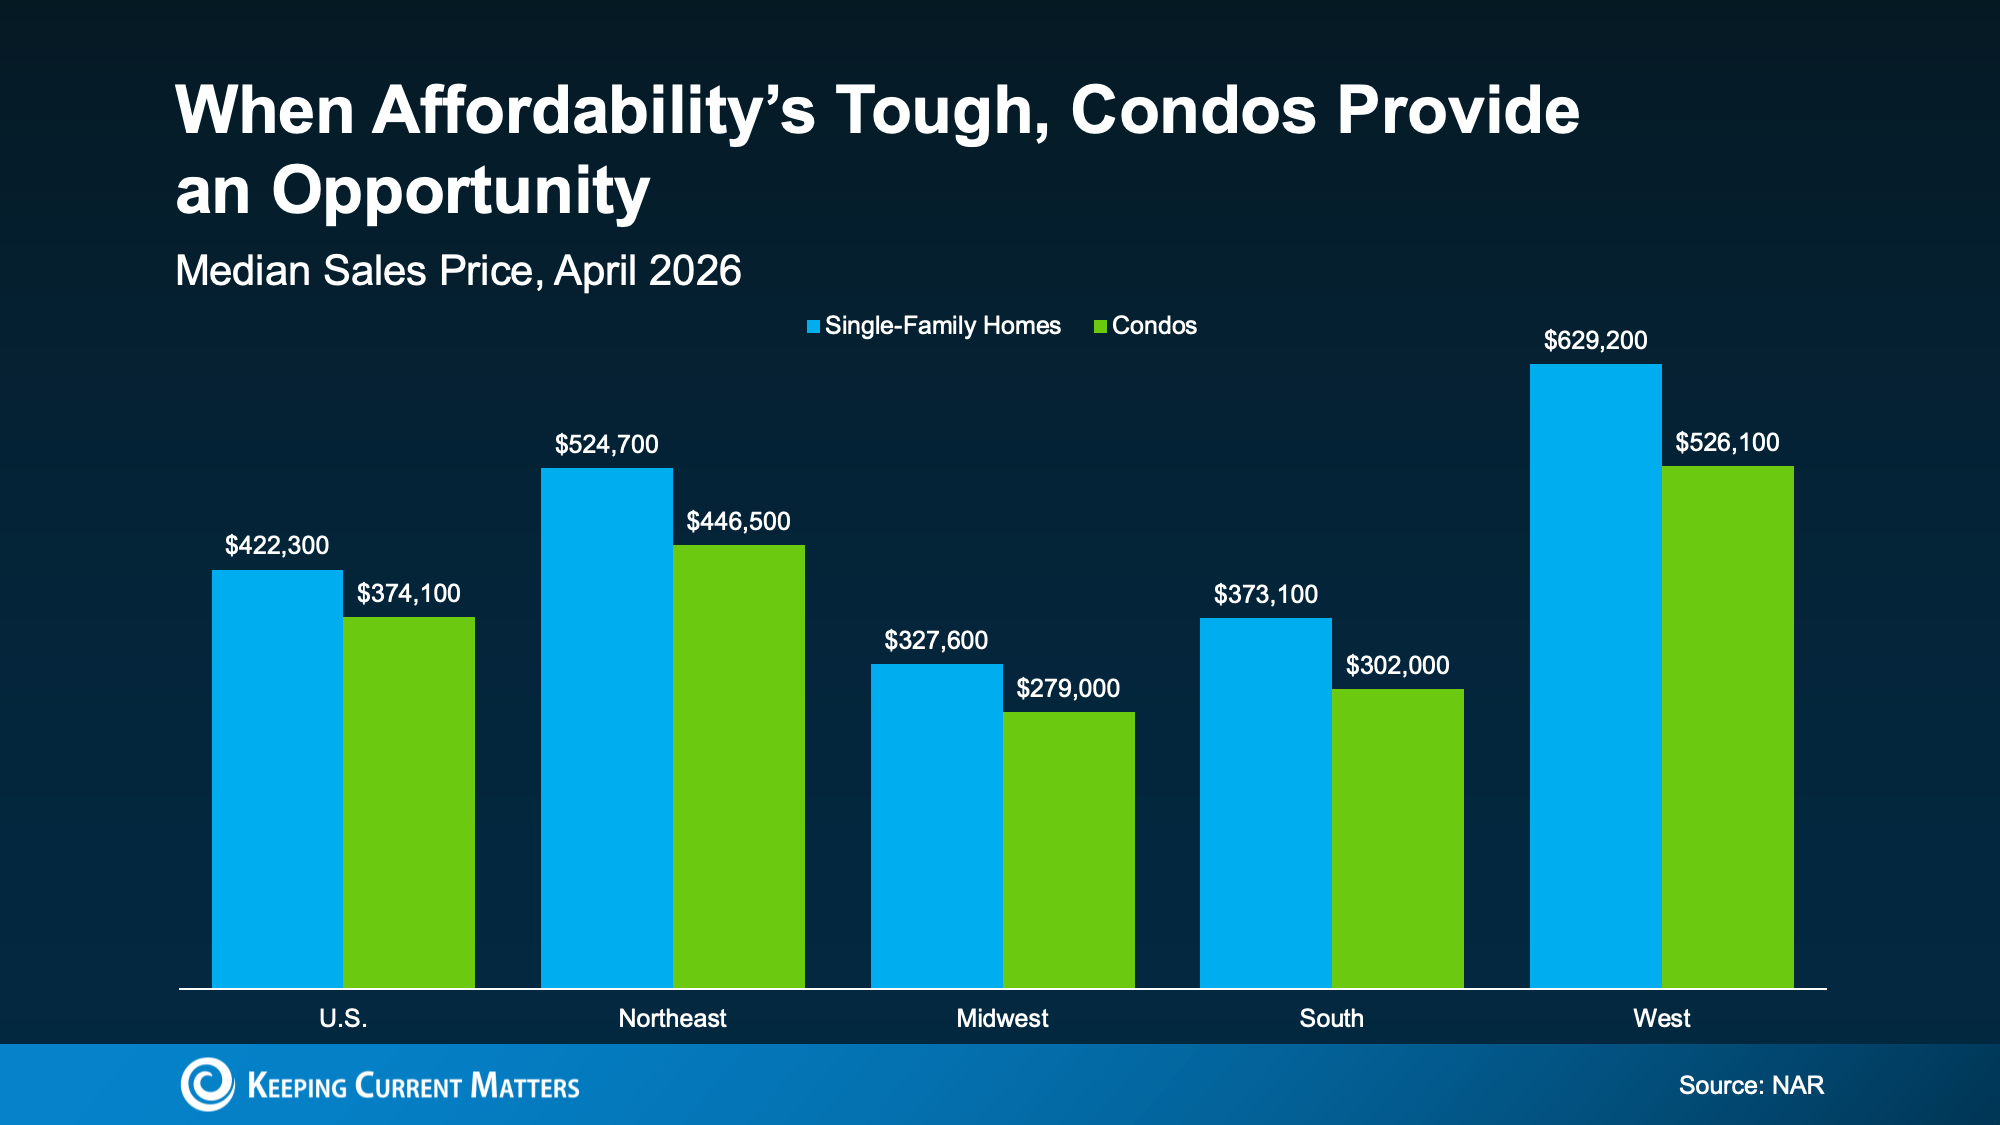
For buyers trying to make the numbers work, this is a considerable difference.
According to NAR, condo sales rose 2.7% last month, and were up year over year. And value is a driving factor. Ali Wolf, Chief Economist for New Home Source, explains:
“In addition to favoring smaller floor plans, more consumers are showing a willingness to live in an attached home. This shift is not driven by a preference for shared walls, but by a pursuit of value.”
For buyers focused on affordability, condos can offer a way to stay active in the market without stretching too far for a detached single-family home.
The Right Community Can Make a Smaller Home Feel Bigger
Square footage is important, but it’s only one part of a home’s blueprint.
A smaller home may still work well if the surrounding community gives you access to amenities that extend how you live day to day. In some condo communities, neighborhoods, and master-planned developments, shared spaces help fill in the gaps.
Depending on the community, amenities may include:
- Walking trails
- Pools
- Fitness centers
- Co-working spaces
- Outdoor gathering areas
Features like these can make a smaller home feel more livable, and functional. For example, if there’s no room for a home office, a nearby co-working space can help. If you don’t have space for a dedicated workout room, a shared fitness center can fill the gap.
Buying a Smaller Home Does Not Mean Giving Up Comfort
A smaller home can still support the way you want to live. Focusing less on total square footage and more on how the space works can offer a different perspective.
As you compare options, consider:
- Layout: Does the floor plan make daily routines easier?
- Storage: Are closets, cabinets, and garage space used efficiently?
- Natural light: Does the home feel open and comfortable?
- Shared amenities: Does the community offer spaces you would actually use?
- Location: Does the home keep you close to the places that matter to you?
A smaller home with the right layout, features, and setting may be a better fit than a larger home that stresses your budget or needs more work.
Bottom Line: Smaller Homes Can Offer Bigger Opportunities
Today’s smaller single-family homes and condos have more to offer than their square footage might suggest. They can give buyers more budget flexibility, access to newer features, and opportunities to live in communities designed with useful amenities.
If your current search feels limited, consider widening your options. A smaller home, new build, or condo may offer opportunities you never knew existed.
Curious about smaller homes, condos, or new construction options in your area? Contact our brokerage to explore what’s available and compare homes that fit your budget and goals.
Are Home Prices Going To Fall? Here’s What Buyers Should Know
One of the biggest questions buyers are asking right now is: Will home prices fall after I buy?
It’s a common concern. Buying a home is a major financial decision, and no one wants to feel like they bought too early, or too late. With headlines pointing to changing prices in some markets, it’s easy to want to play it safe by waiting.
But the short-term noise isn’t the whole story. While some local markets may see temporary dips, the bigger, long-term picture is much different: home prices historically rise over time.
What Housing Market Data Shows
When you look at long-term housing data, one trend becomes clear. Home values have generally moved upward for decades.
Yes, there have been exceptions. The housing crash of 2008 is the most dramatic example. And in some years, certain markets have seen slight declines. But outside of major disruptions, home prices have typically either held steady or increased, and data from Case-Shiller and Biello shows this.
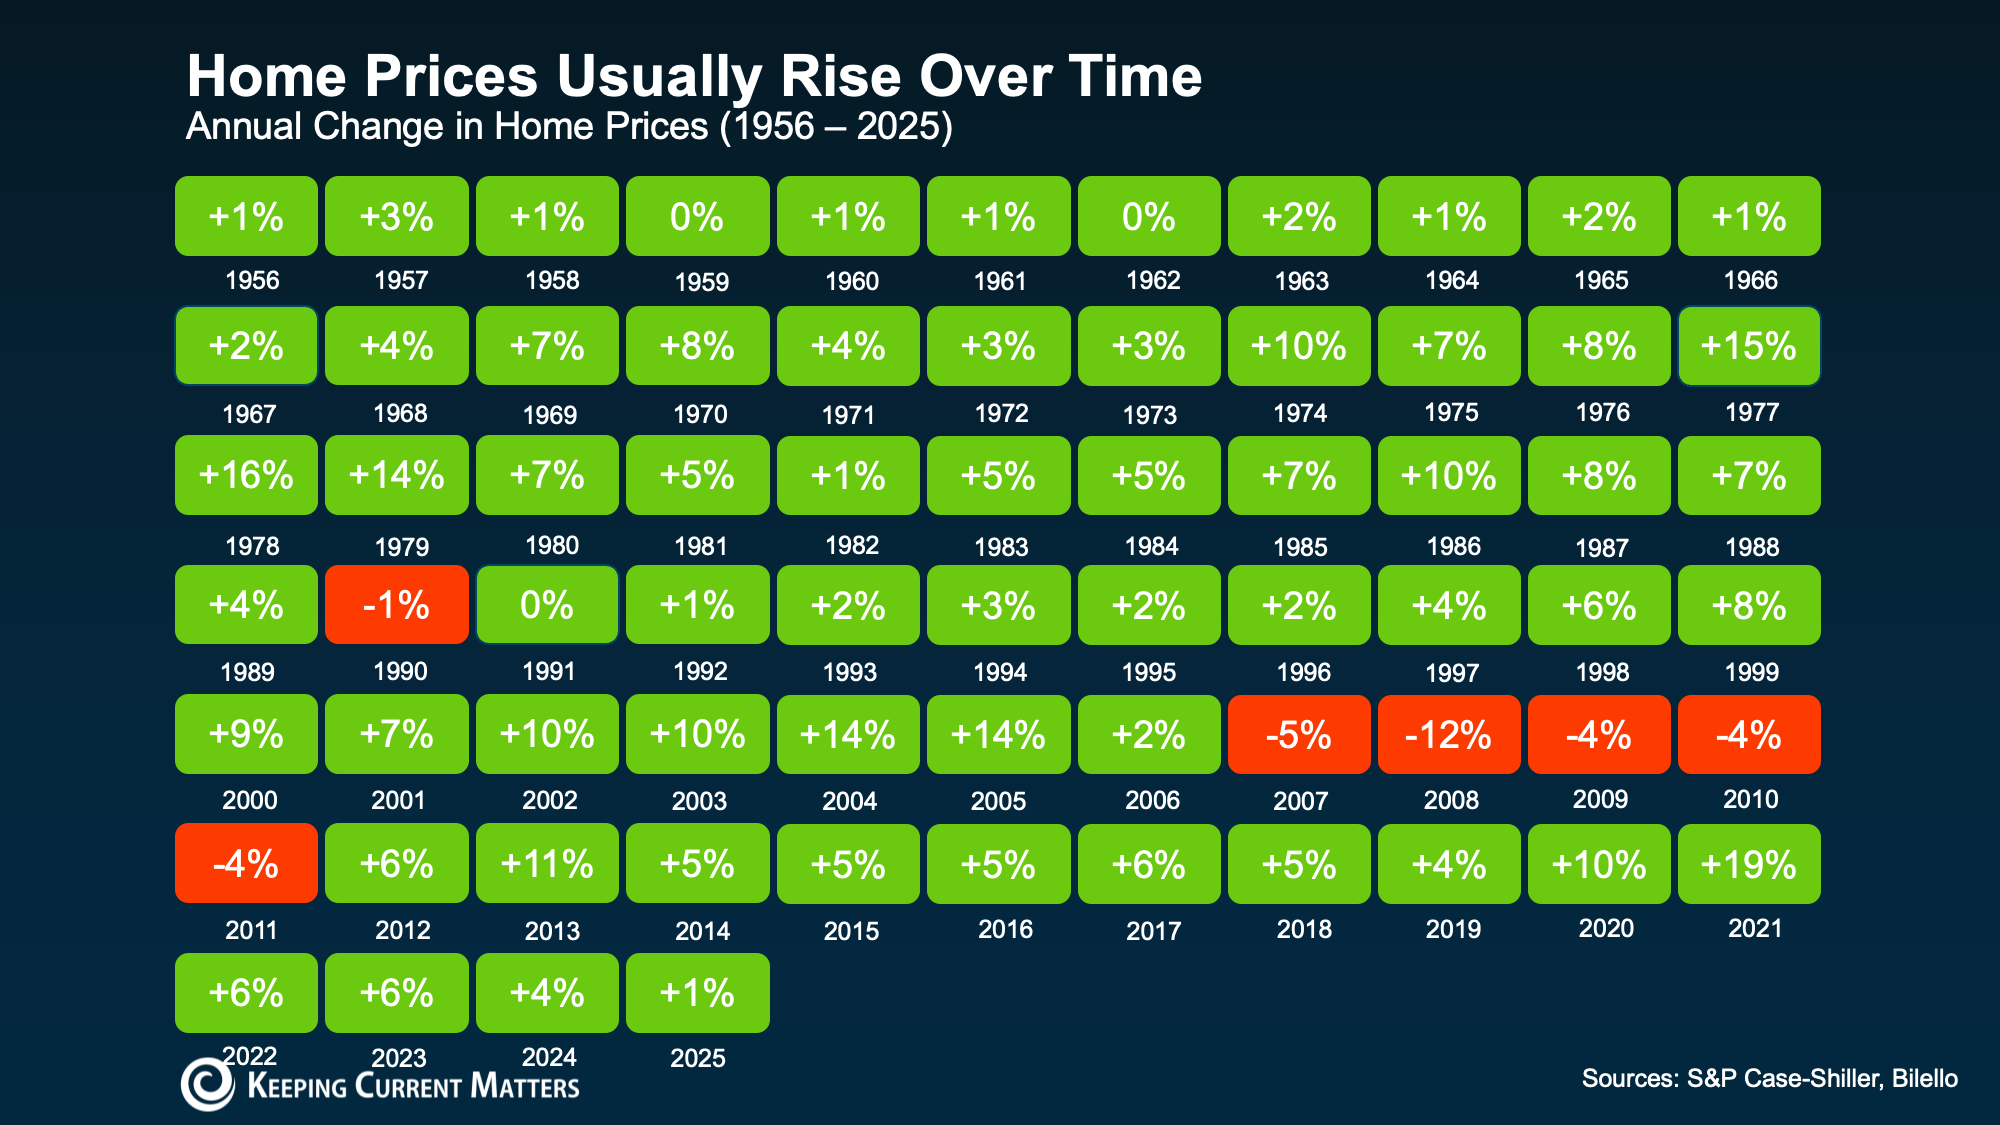
That long-term track record is important for buyers to understand. Real estate is not usually about what happens over the next few weeks or months. It’s about what happens over several years.
Short-term price drops can happen, especially in markets where inventory is rising or buyer demand has cooled. But historically, those dips have proven to be temporary.
Why Home Prices Tend To Rise Over Time
There are several consistent reasons home prices tend to increase in the long run.
People Always Need Homes
Life changes keep the housing market moving. People get married, have children, change jobs, retire, downsize, or relocate to be closer to family. No matter what the market is doing, people always need places to live.
Steady demand like this helps support home values over time.
Housing Supply Is Still Limited
Even though more homes may be available for sale than there were during the tightest years of the market, many areas are still dealing with housing shortages.
When there aren’t enough homes to meet buyer demand, prices tend to stay elevated. Even when demand slows, limited inventory helps prevent dramatic price drops in most markets.
Inflation Plays a Role
Over time, the cost of goods and services tends to rise, and housing is no exception. Land, labor, materials, and construction costs all influence home values.
As the everyday cost of living inflates, home prices naturally move higher too.
What This Means If You’re Thinking About Buying
It’s natural to worry about whether home prices will drop after you buy a home. That concern is especially common among first-time buyers trying to make a smart financial decision.
But what matters most is your own expected timeline.
If you’re planning to buy a home and stay there for several years, short-term market movements matter less. That’s because time gives your home more opportunity to appreciate in value, helping you ride out the kind of ups and downs we’re seeing in some markets.
That’s why many real estate professionals recommend buying only when you expect to stay in the home for at least five years. While there’s no guaranteed timeline, a longer-term approach often gives homeowners a better chance to benefit from rising values.
Real Estate Is Local
Another critical point to remember is that not all housing markets are the same.
Some areas may see home prices soften. Others may continue to rise because demand is strong and inventory remains low. National headlines can give you a general idea of what’s happening, but they don’t always reflect conditions in your specific city, neighborhood, or price range.
That’s why local market insight matters. A trusted real estate agent can help you understand whether prices are rising, flattening, or adjusting in your area.
Don’t Try To Time the Market Perfectly
Trying to buy at the exact bottom of the market is extremely difficult. By the time it’s clear prices have bottomed out, competition may already be increasing again.
Instead of focusing only on timing, focus on whether buying makes sense for your life, your finances, and your long-term goals.
Ask yourself:
- Can I comfortably afford the monthly mortgage payment?
- Do I plan to stay in the home for several years?
- Does buying now support my lifestyle and financial goals?
- Am I prepared for the responsibilities of homeownership?
If the answer is yes, buying may still make sense, even if prices fluctuate in the short term.
Bottom Line: Most Price Drops Are Temporary
So, are home prices going to fall? In some markets, small short-term declines are possible. Historically though, data shows home prices strongly tend to rise over time.
That’s why buying a home is often considered a long-term investment, not a short-term gamble.
You don’t have to buy before you’re ready. But if homeownership fits your goals and you plan to stay put for a while, today’s market headlines shouldn’t scare you away.
For the most reliable picture, talk with a local real estate agent who can explain what home prices are doing in your area and help you decide whether now is the right time to make a move.
Do You Need 20% Down? Most First-Time Buyers Pay Less
If you’ve been waiting to buy a home because you think you need a 20% down payment, you’re not alone. According to Google Trends, searches for house down payment information recently reached a new high, which shows just how many buyers are trying to understand what it really takes to get started.
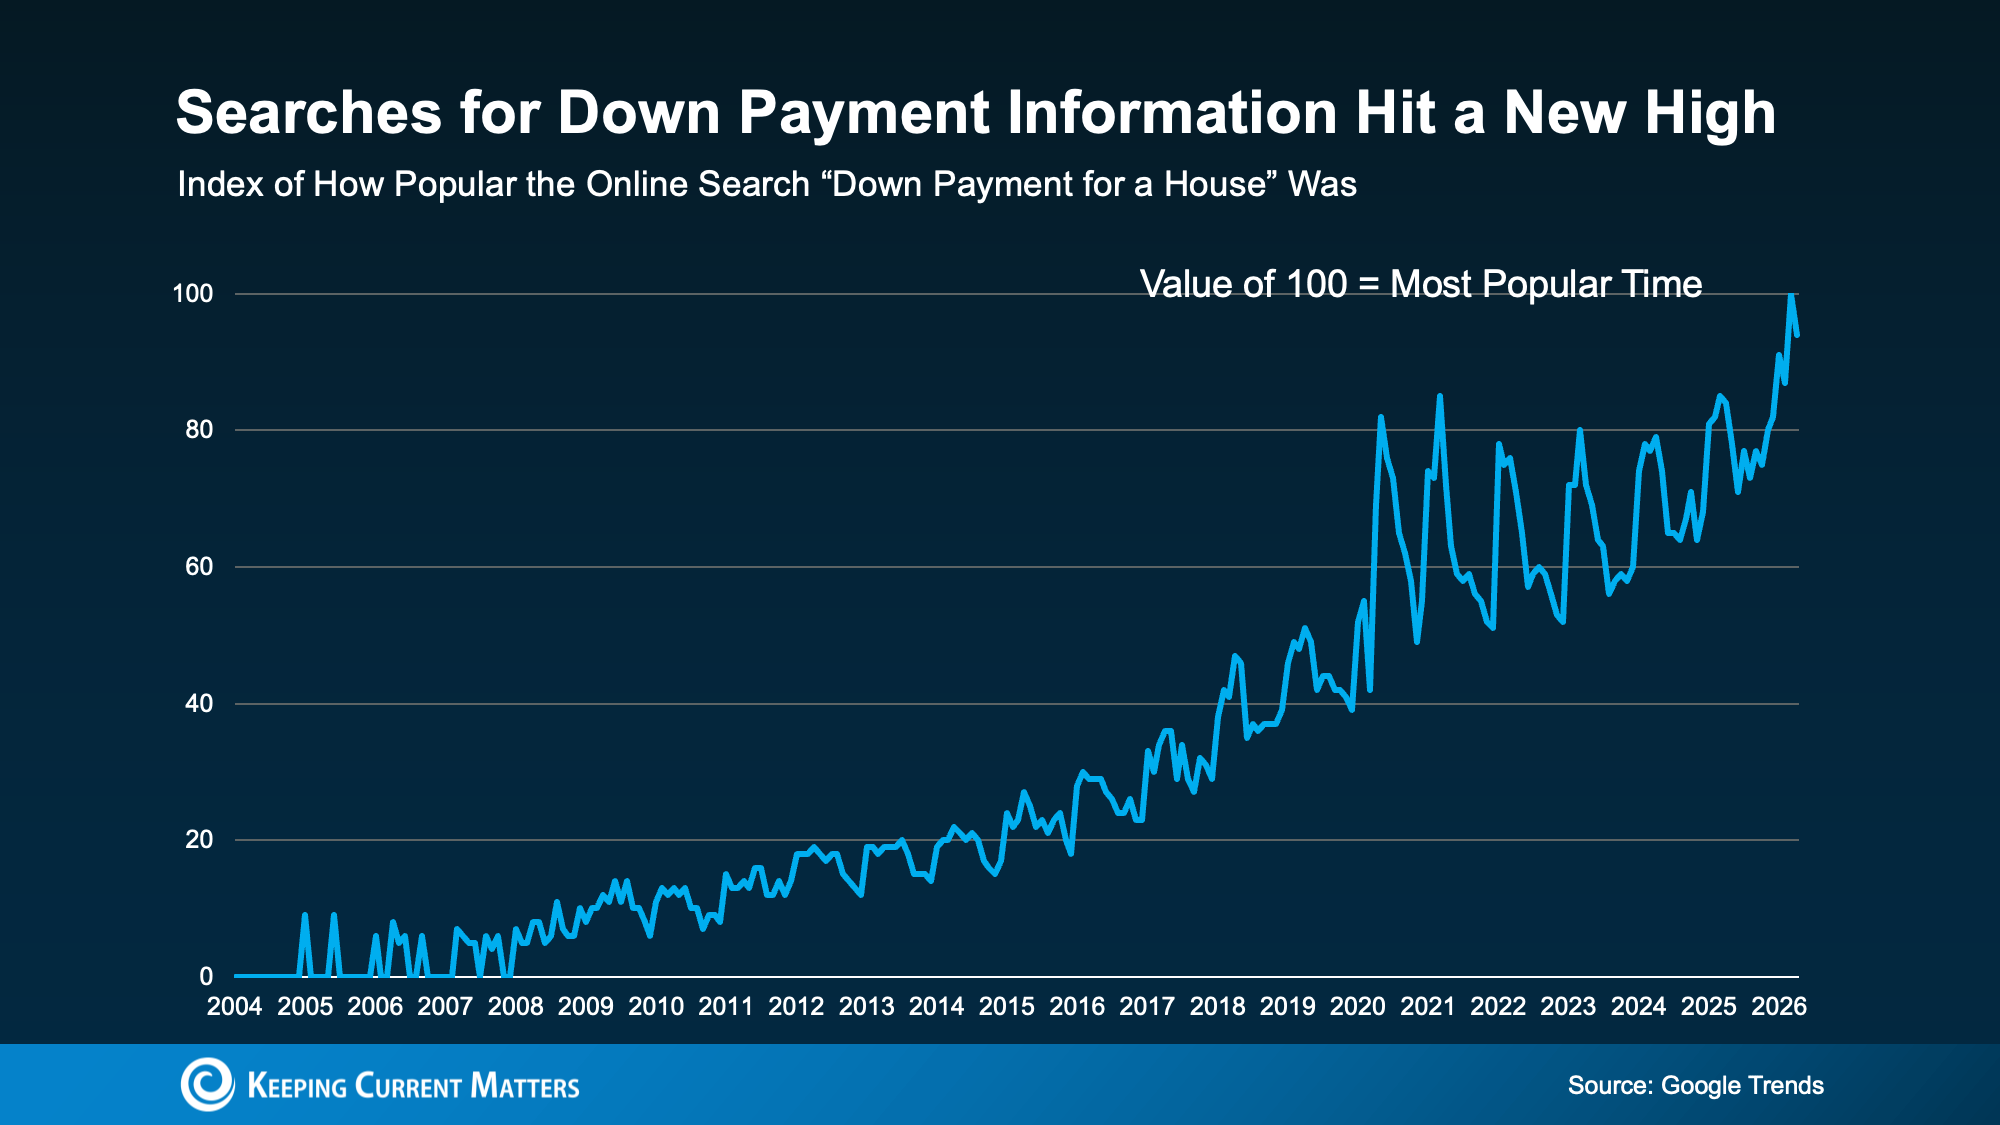
The good news is that 20% down can be helpful, but it usually isn’t required. For many first-time homebuyers, the path to homeownership starts with a smaller down payment, the right loan program, and possibly even down payment assistance.
The 20% Down Payment Homebuying Myth
The idea that you must put 20% down to buy a home is one of the most common misconceptions in real estate. It’s easy to see why the myth sticks. A larger down payment can lower your monthly mortgage payment, reduce the amount you finance, and in some cases help you avoid private mortgage insurance.
But that doesn’t mean 20% is the minimum needed to buy a home.
Unless your lender specifically requires it, you may have options that call for far less money upfront. As The Mortgage Reports explains:
“The amount you need to put down will depend on a variety of factors, including the loan type and your financial goals. If you don’t have a large down payment saved up, don’t worry—there are plenty of options available, and you don’t need to put down the traditional 20% . . . many homebuyers are able to secure a home with as little as 3% or even no down payment at all . . .”
For instance, FHA loans allow down payments as low as 3.5%. VA loans and USDA loans may offer zero down payment options for qualified buyers, including eligible Veterans and buyers purchasing in qualifying areas.
Saving for 20% can take longer than many buyers expect. If you’re delaying your plans only because you believe 20% down is a hard requirement, you may be waiting extra long to buy.
What First-Time Homebuyers Are Actually Putting Down
But if most first-time buyers aren’t putting down 20%, what are they putting down?
According to the National Association of Realtors (NAR), the median down payment for first-time homebuyers is 10%. That’s half of the 20% many people assume they need.
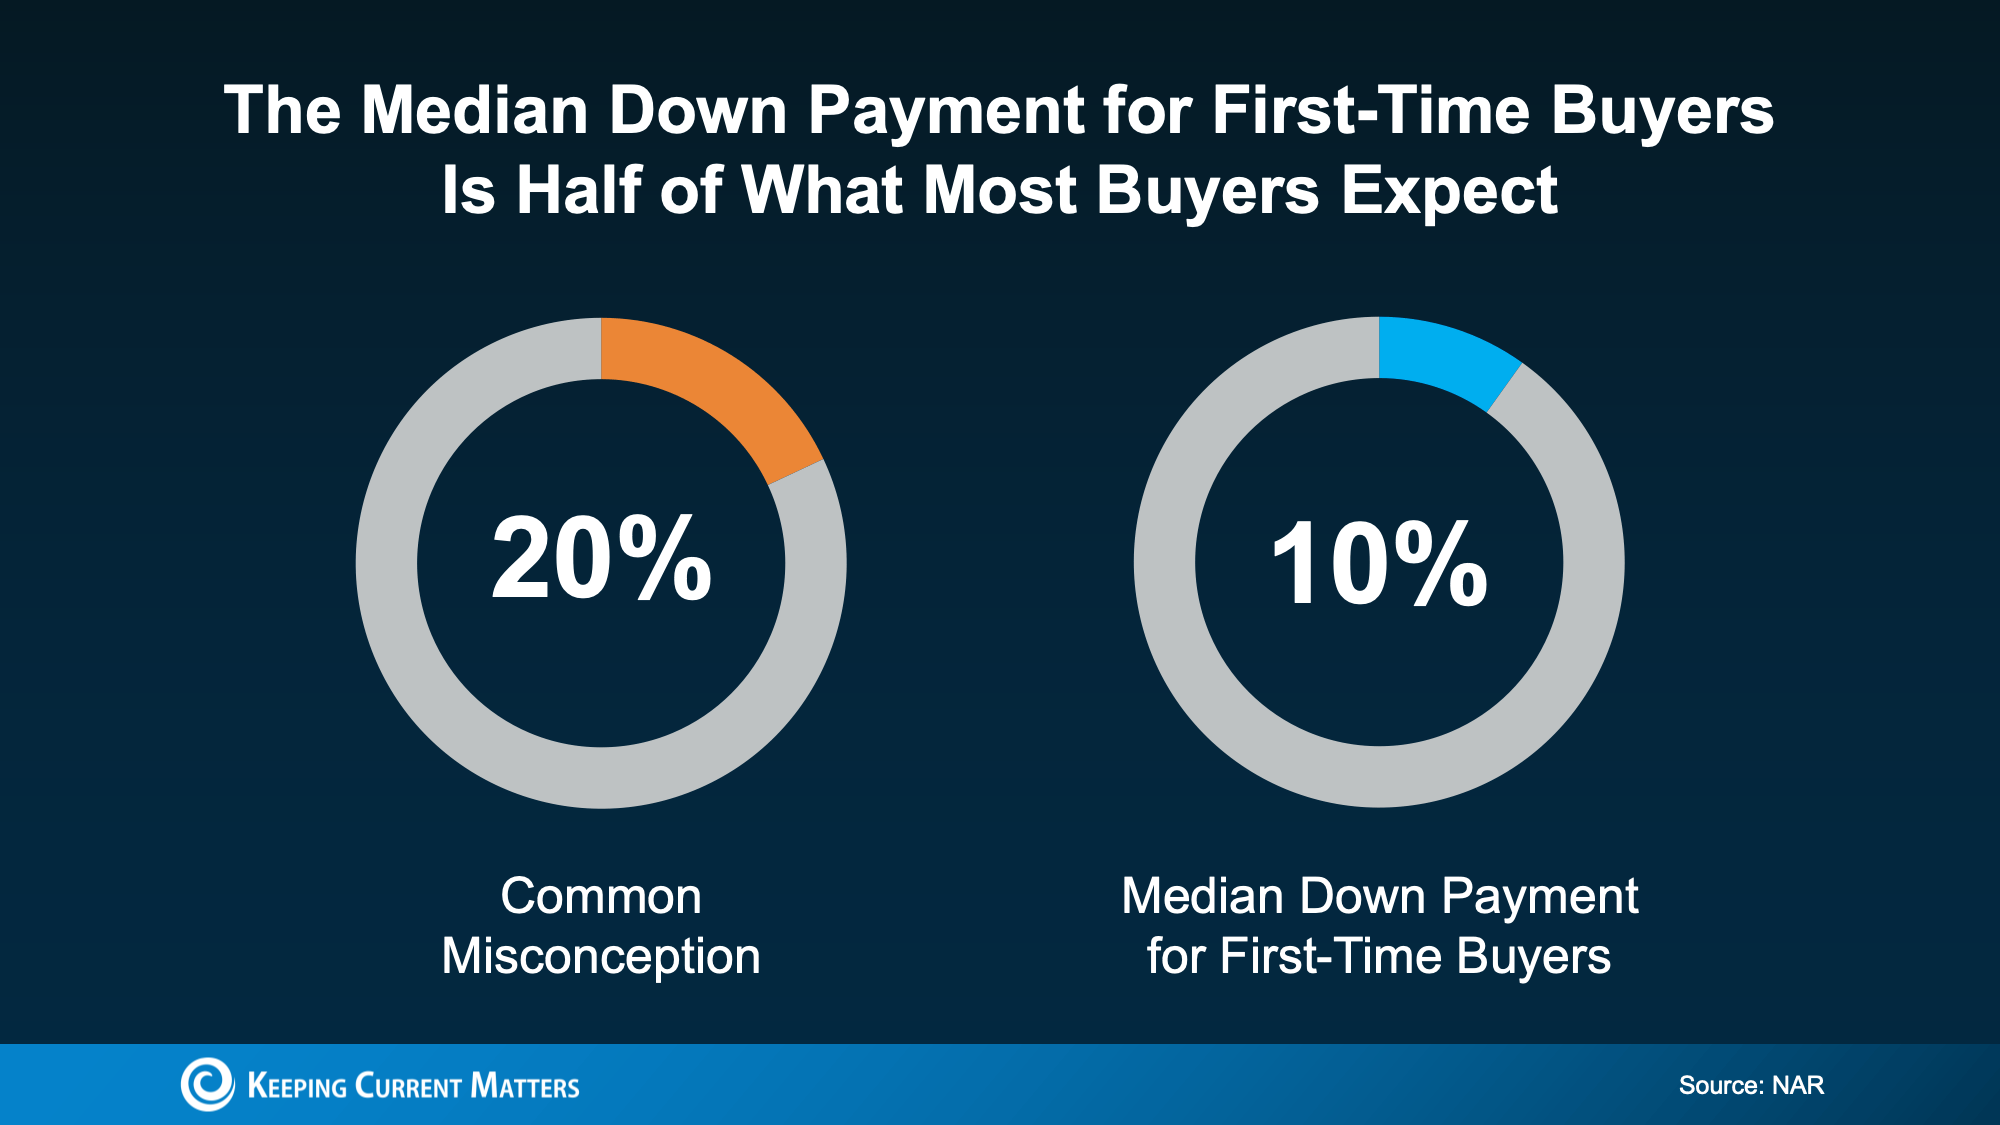
This doesn’t mean 10% is the right amount for every buyer. Your ideal down payment depends on your credit, income, loan type, home price, monthly payment goals, and how much cash you want to keep available after closing.
But it does show that first-time buyers are finding ways to purchase without waiting until they have 20% saved. And for some buyers, the number may be even lower depending on the loan program they use.
Down Payment Assistance Could Help You Buy Sooner
There’s another reason the 20% myth can hold buyers back: many people don’t realize how much help may be available.
Down payment assistance programs are designed to help qualified buyers cover part of their upfront costs. These programs may come in the form of grants, forgivable loans, low- or no-interest second loans, tax credits, or other forms of support. Eligibility can vary based on income, location, property type, profession, or whether you complete a homebuyer education course.
Research from Realtor.com found almost 80% of first-time homebuyers qualify for down payment assistance (DPA), but only 13% take advantage.
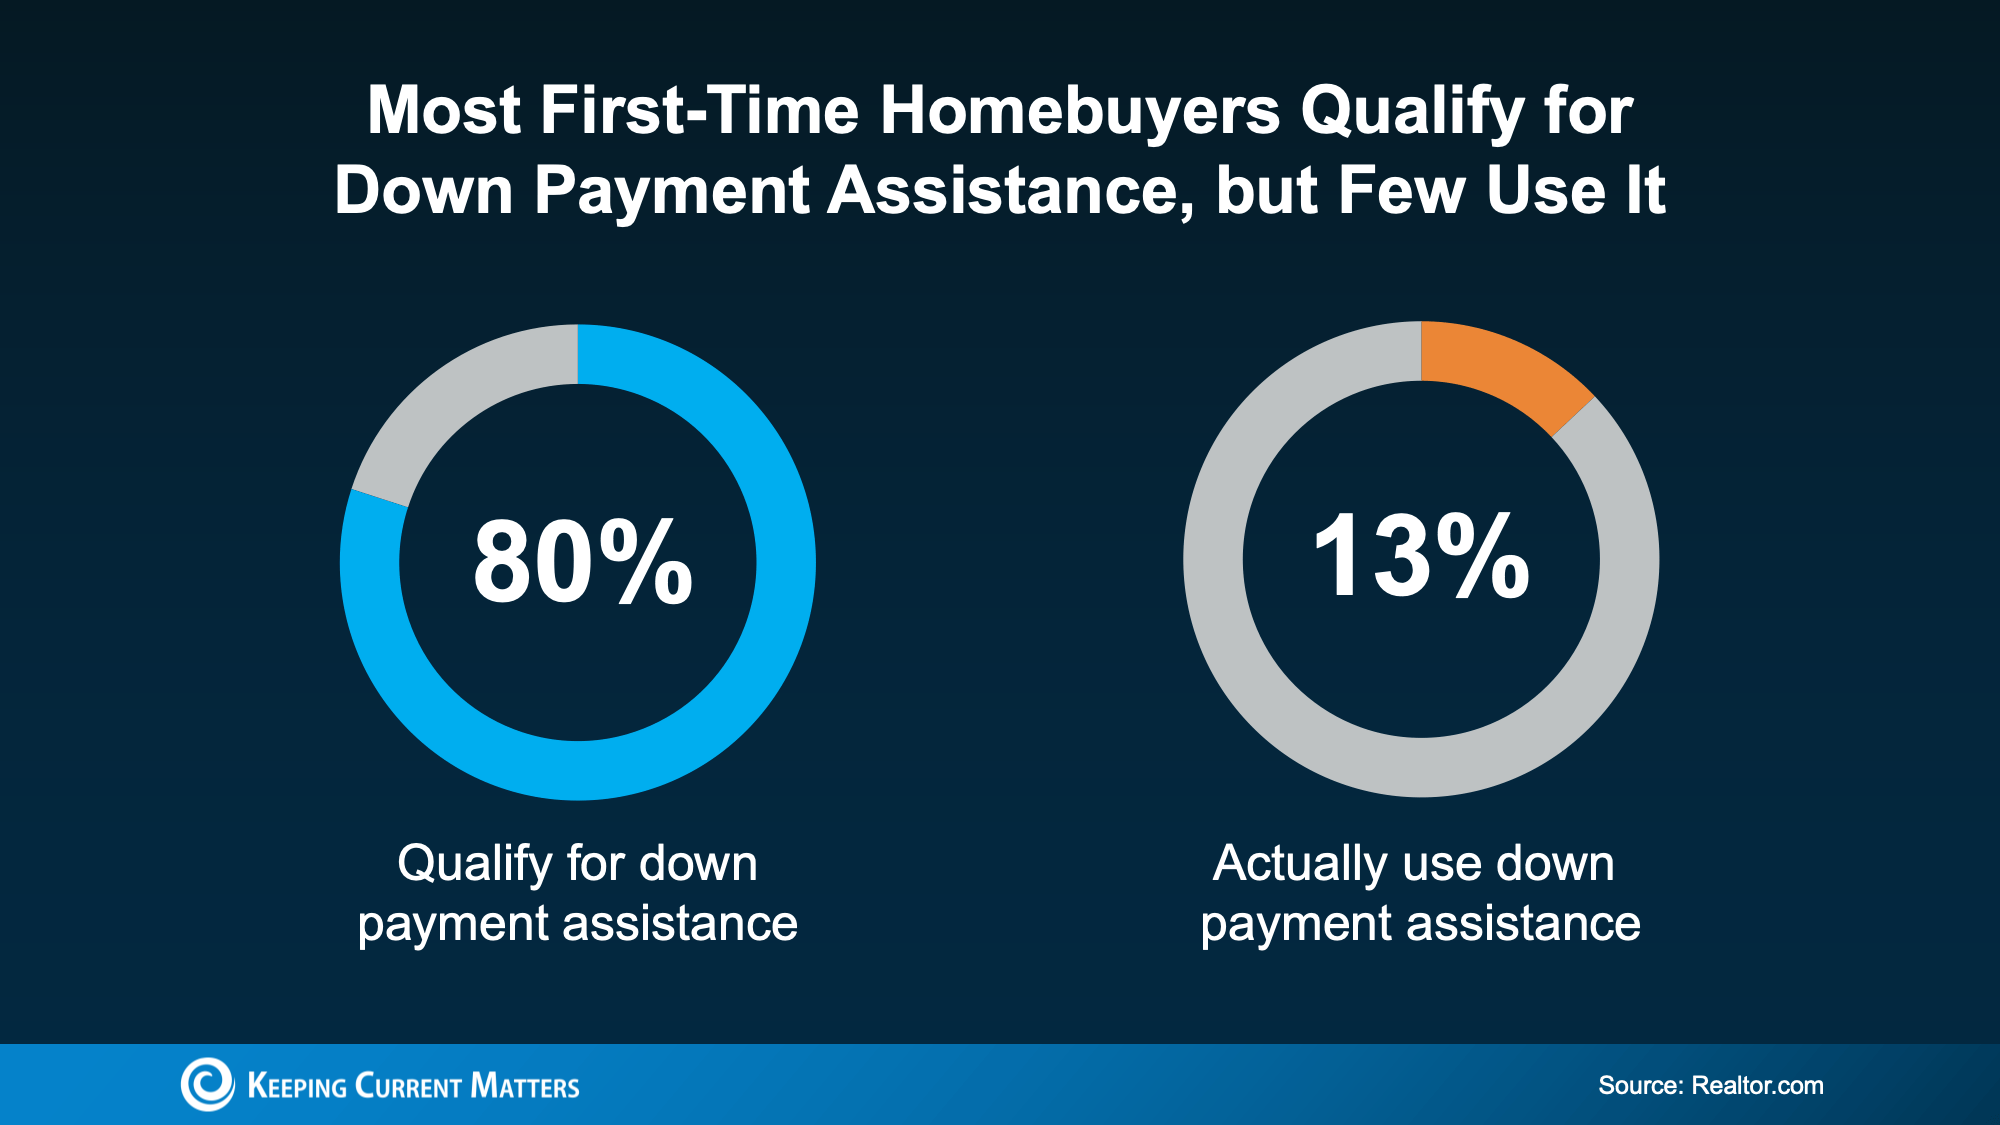
That gap is important. It means many would-be buyers may be leaving valuable assistance on the table simply because they don’t know what programs exist or how to apply.
In the U.S., there are more than 2,600 homeownership programs available, and many provide meaningful financial support. As Down Payment Resource explains:
“With an average benefit of $18,000, down payment assistance (DPA) remains one of the most essential tools for addressing the nation’s affordability challenges. Programs continue to expand in scope, serving a broader range of incomes, property types and borrower needs, including first-generation, military and repeat buyers.”
For some buyers, that kind of assistance could make a major difference. It may help cover part of the down payment, reduce closing costs, or make it easier to keep emergency savings intact after the purchase. In some cases, buyers may even be able to combine multiple programs for additional support.
The Bottom Line: Explore Your Options
Most first-time homebuyers do not put 20% down, and you may not need to either. While saving is important, the real question is whether you know which loan programs and assistance options fit your situation.
Before you rule out buying, connect with a trusted lender and a knowledgeable real estate professional. They can help you understand what you really need to save, what programs you may qualify for, and whether homeownership could be closer than you think.
3 Things That Aren’t Going To Happen in Today’s Housing Market
There’s no shortage of uncertainty in today’s housing market, and that’s naturally fueling a lot of dramatic headlines. And if you’re trying to buy a home, that kind of noise can make your decision feel a lot more complicated.
In fact, a recent CNBC study asked homebuyers what they’re most concerned about, and the same three topics kept rising to the top:
- Mortgage rates
- The number of homes for sale
- Home prices
The challenge is that much of what people are hearing about these topics is driven by misconceptions, not facts. Let’s separate the headlines from what the data is really showing.
Misconception #1: “I Should Wait Because Mortgage Rates Are Going To Fall Dramatically”
One of the most common ideas circulating on social media is that mortgage rates are about to drop sharply, so waiting to buy is the smarter move.
But is that what experts are expecting?
While mortgage rates have eased a little in recent weeks, forecasts still aren’t predicting any major declines. It’s more likely that rates will stay in the low 6% range this year.
And that’s not a remarkable shift from the rates we’re seeing today:
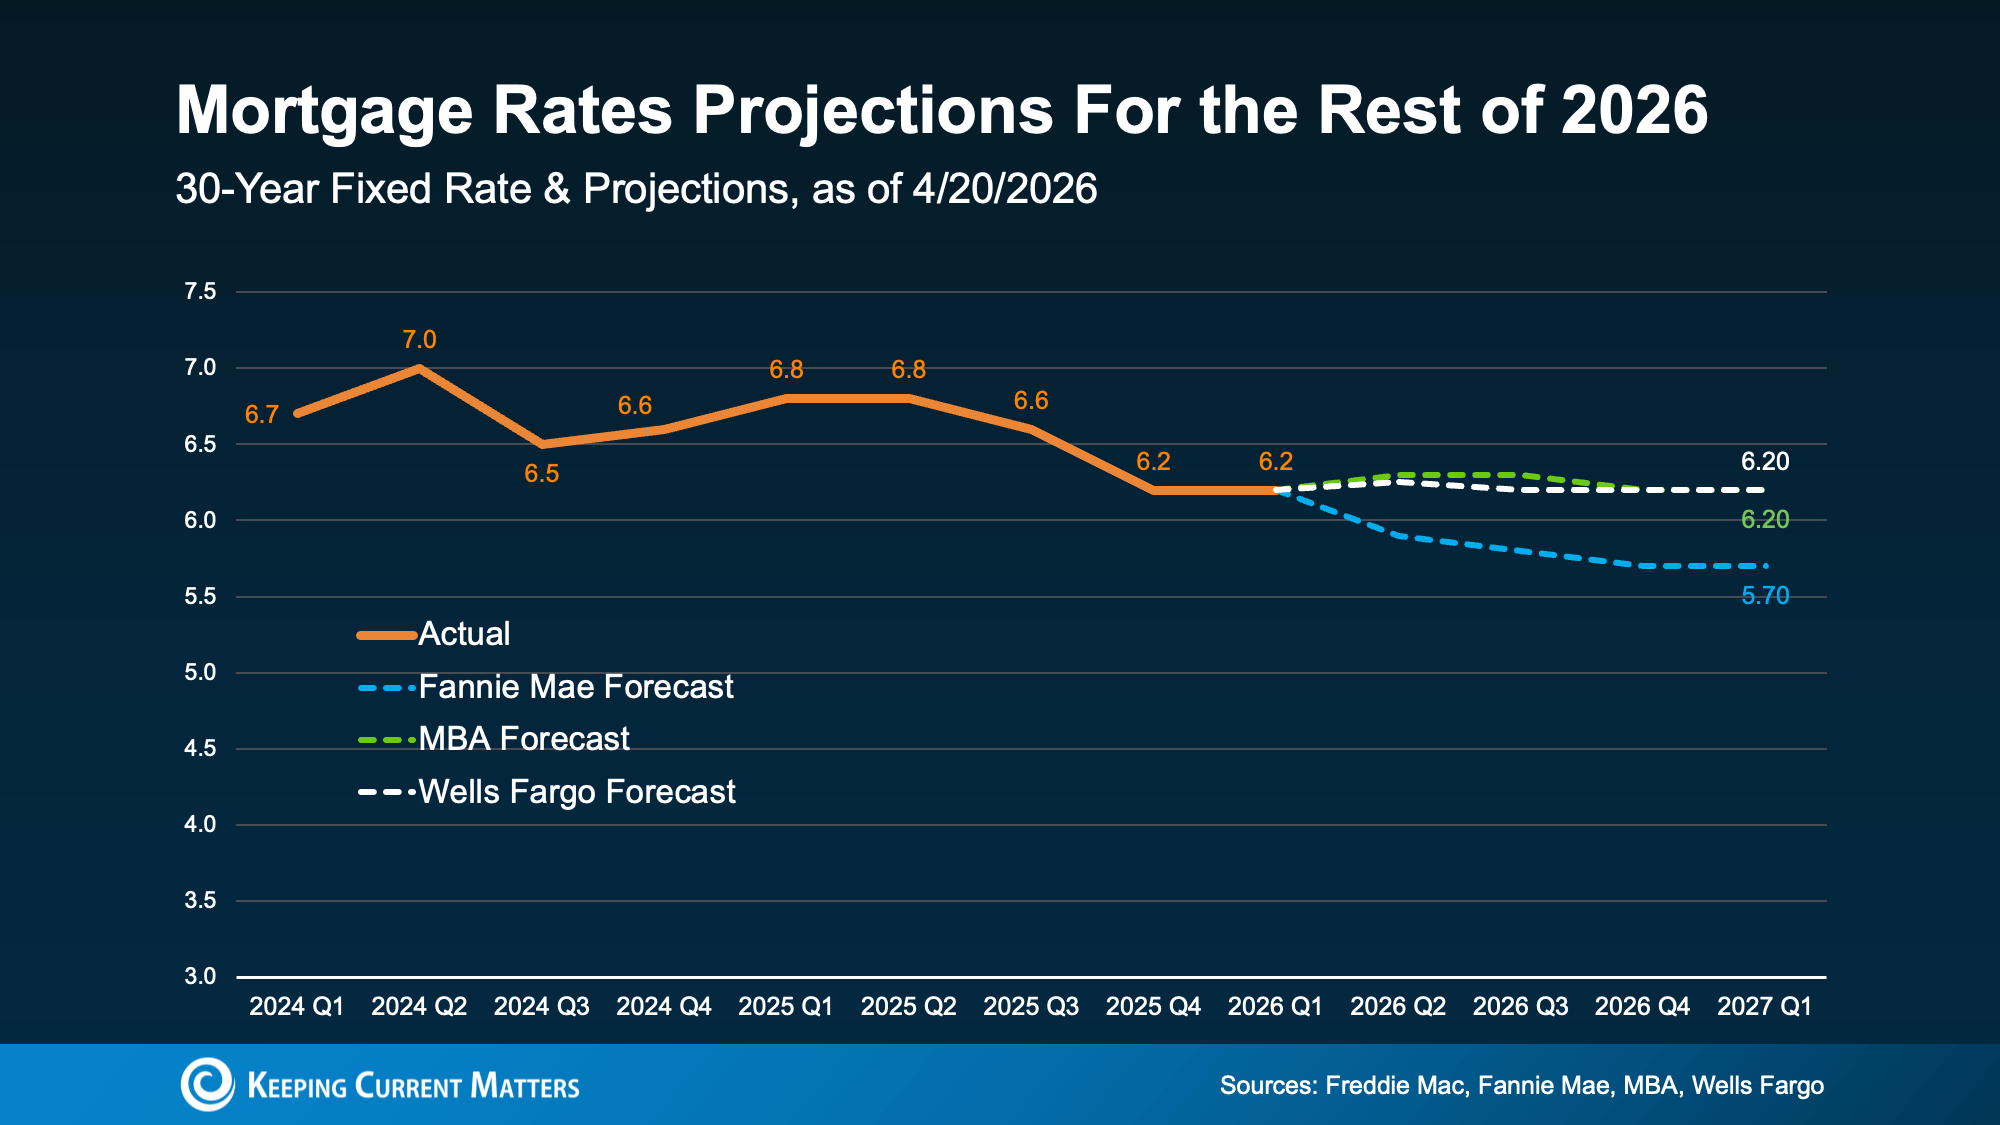
Obviously, a lot depends on inflation and the broader economy. But based on what we know right now, waiting for a big drop in mortgage rates may not play out the way many buyers hope. As U.S. News explains:
“Mortgage rates aren’t expected to change much over the next several quarters . . .”
And even with rates where they are today, buying a home is already more affordable than it was a year ago. Even if rates don’t drop in the near future, home affordability is better now than a year ago.
Misconception #2: “There Are Too Many Homes for Sale”
You may have heard that housing inventory is rising. Nationally, that’s true: the number of homes for sale is 8% higher than it was at this time last year. But that’s not bad news. In lots of markets, it’s easing the pressure on buyers.
The problem is that some headlines make good news sound like bad news. They focus on the fact that inventory is at its highest level since 2019 or highlight how many new homes builders are adding. That can make it sound like supply is growing too much, too fast.
But the bigger picture tells a different story.
According to new Realtor.com data, even though inventory is up over last year, it’s still nearly 14% lower than it was in the last normal housing market from 2017 to 2019:
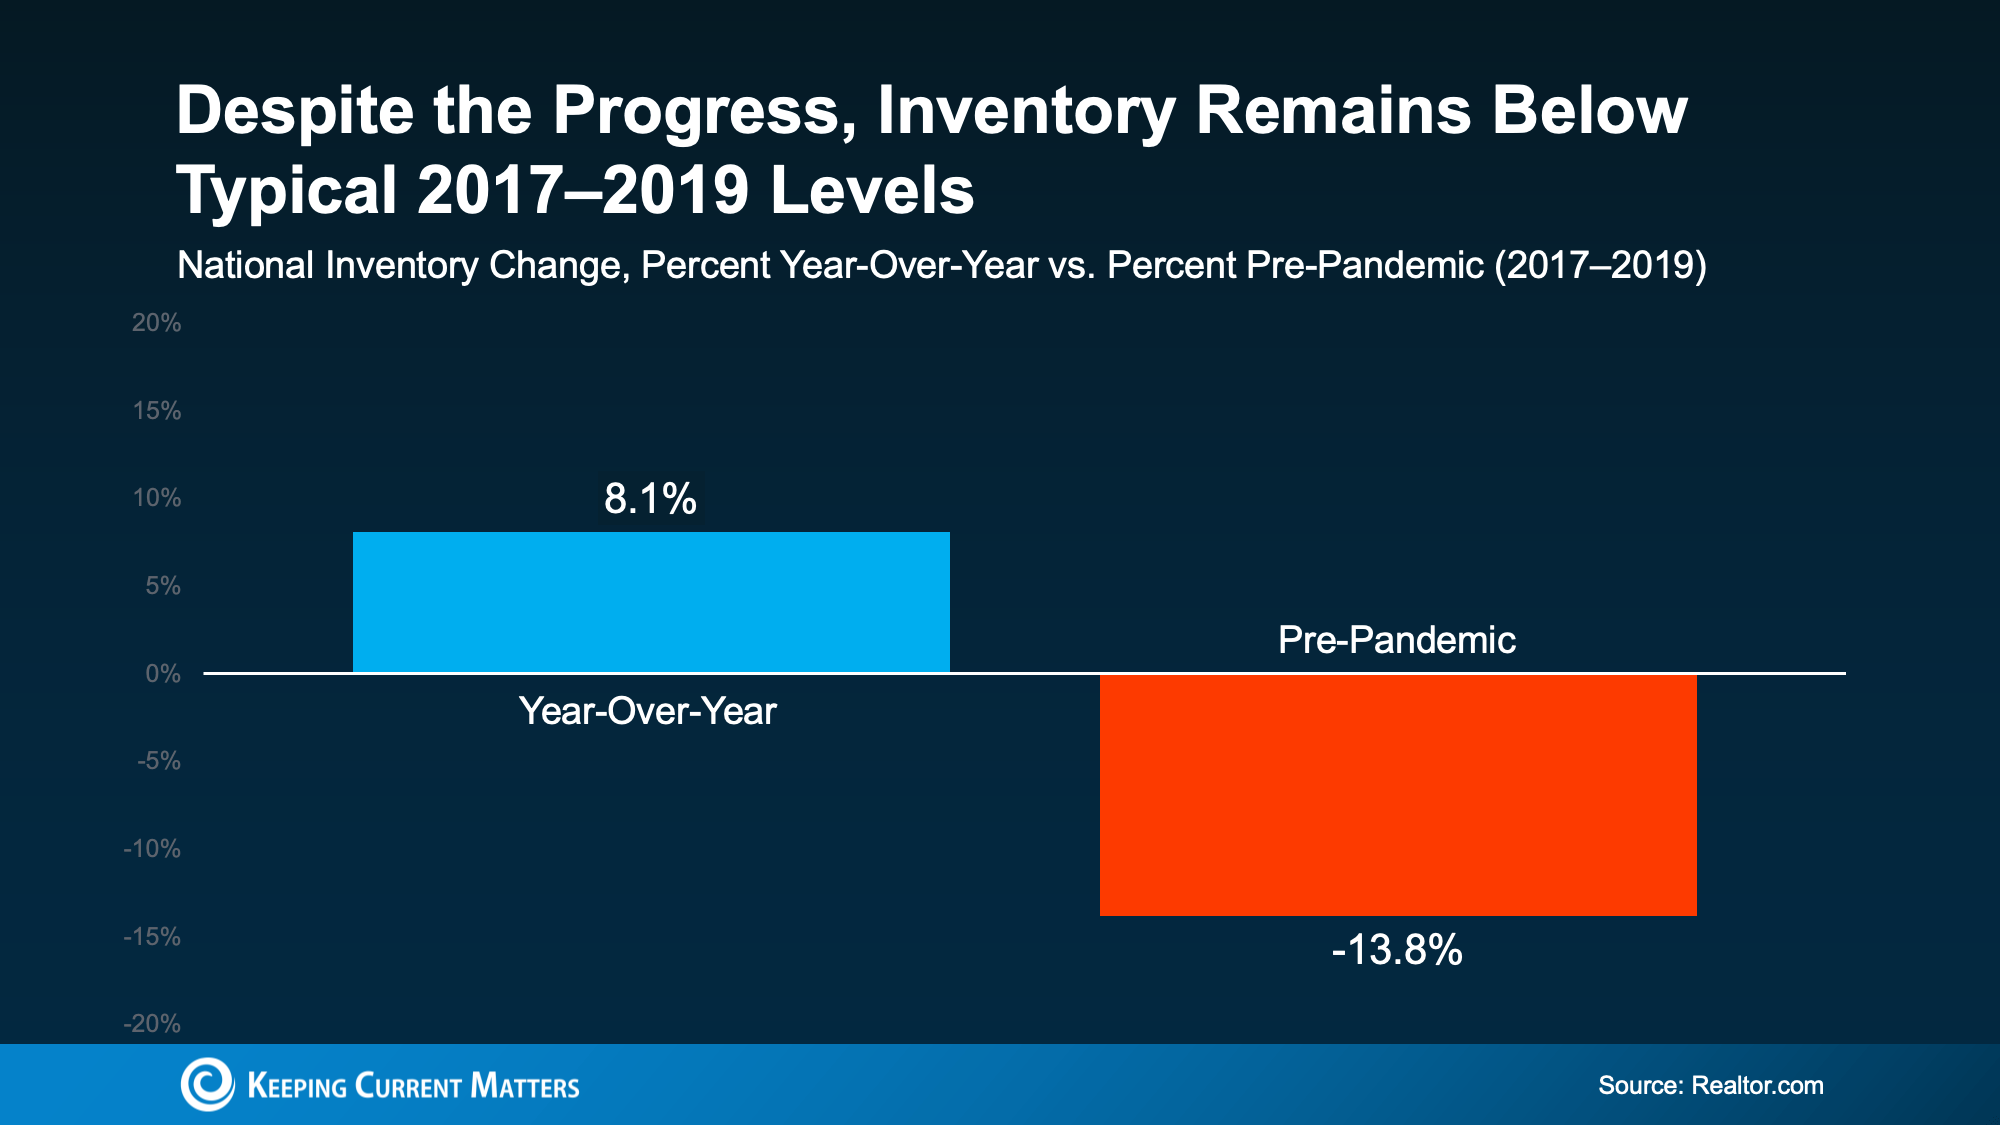
And while local conditions vary, only 9 states have more inventory now than they did before the pandemic. That’s a major reason there aren’t enough homes for sale to trigger anything like the 2008 housing crash.
Misconception #3: “Home Prices Are About To Crash”
This is another common headline you’ve probably seen. This misconception comes from the fact that a few metros are actually seeing small price declines. Influencers are pointing to this to claim home prices are crashing. But this is absolutely not true nationally.
In most markets, home prices are still rising, not falling. Here’s why:
- Many homeowners are choosing not to sell to avoid giving up the low mortgage rate they locked in a few years ago. That continues to limit how much inventory can grow.
- Inventory remains below pre-pandemic norms. There still aren’t enough homes for sale to cause a widespread price crash.
- Even in markets with more listings, some sellers are pulling their homes off the market instead of making major price cuts.
Those are three big reasons home prices are not on track for a crash.
And even in the areas seeing small price declines, those drops are nowhere near enough to erase the huge gains most homeowners have built over the past five years:
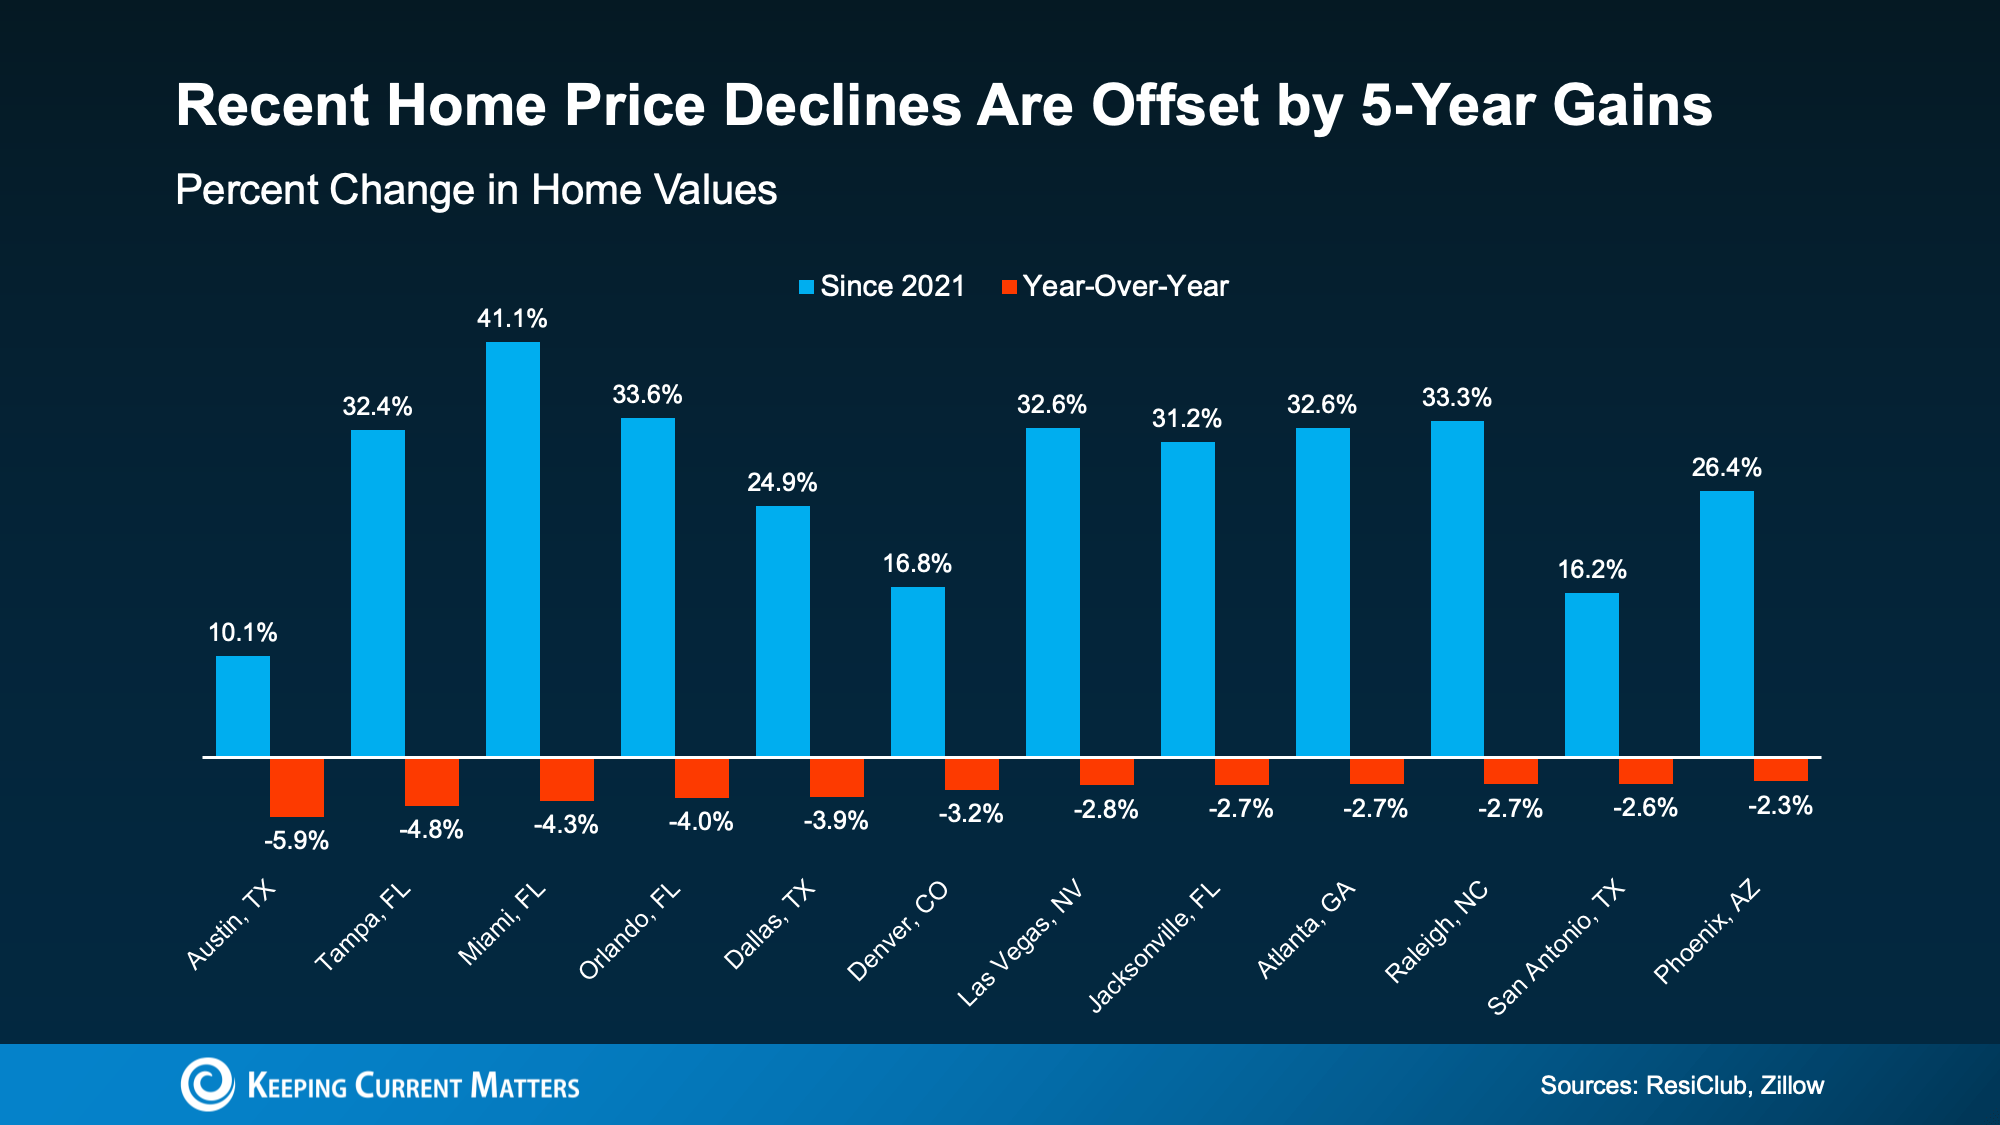
These drops don’t signal a crash. They show the market settling after a few years of record-breaking spikes in prices.
Bottom Line: Get the Facts on Your Market
The discussions we see online can often exaggerate the negative and ignore the positive, especially in housing. If you want a clearer, truer idea of what’s happening with mortgage rates, housing inventory, and home prices in your market, talk to a trusted real estate professional.
Connect with a local real estate agent so you have an expert who can give you the real story on your local housing market.
Top 10 Best Housing Markets for First-Time Home Buyers This Spring
For many hopeful buyers, purchasing a first home has lately felt less like a goal and more like a long shot.
Not because you weren’t financially responsible. Not because you weren’t ready to make a move. But because, every time you checked the numbers, homeownership still didn’t feel realistic.
That’s why so many first-time buyers have put their plans on hold.
Now, after years of watching from the sidelines, this spring may finally bring new opportunities. Especially in certain housing markets where affordability and inventory are starting to improve.
The 10 Best Markets for First-Time Buyers
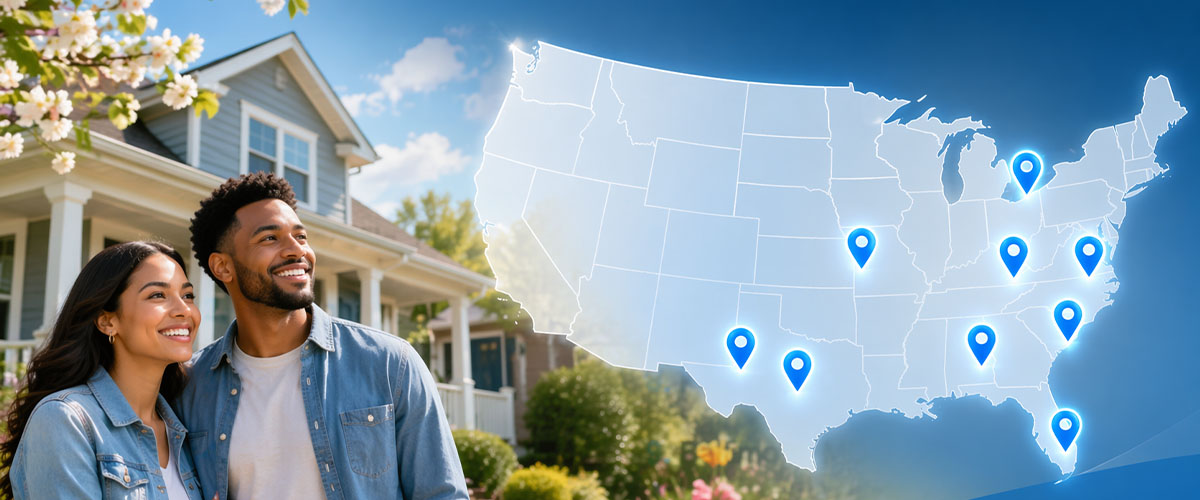
Zillow recently released its list of the top 50 metro areas for first-time home buyers this spring, and the top 10 housing markets stand out for good reason.
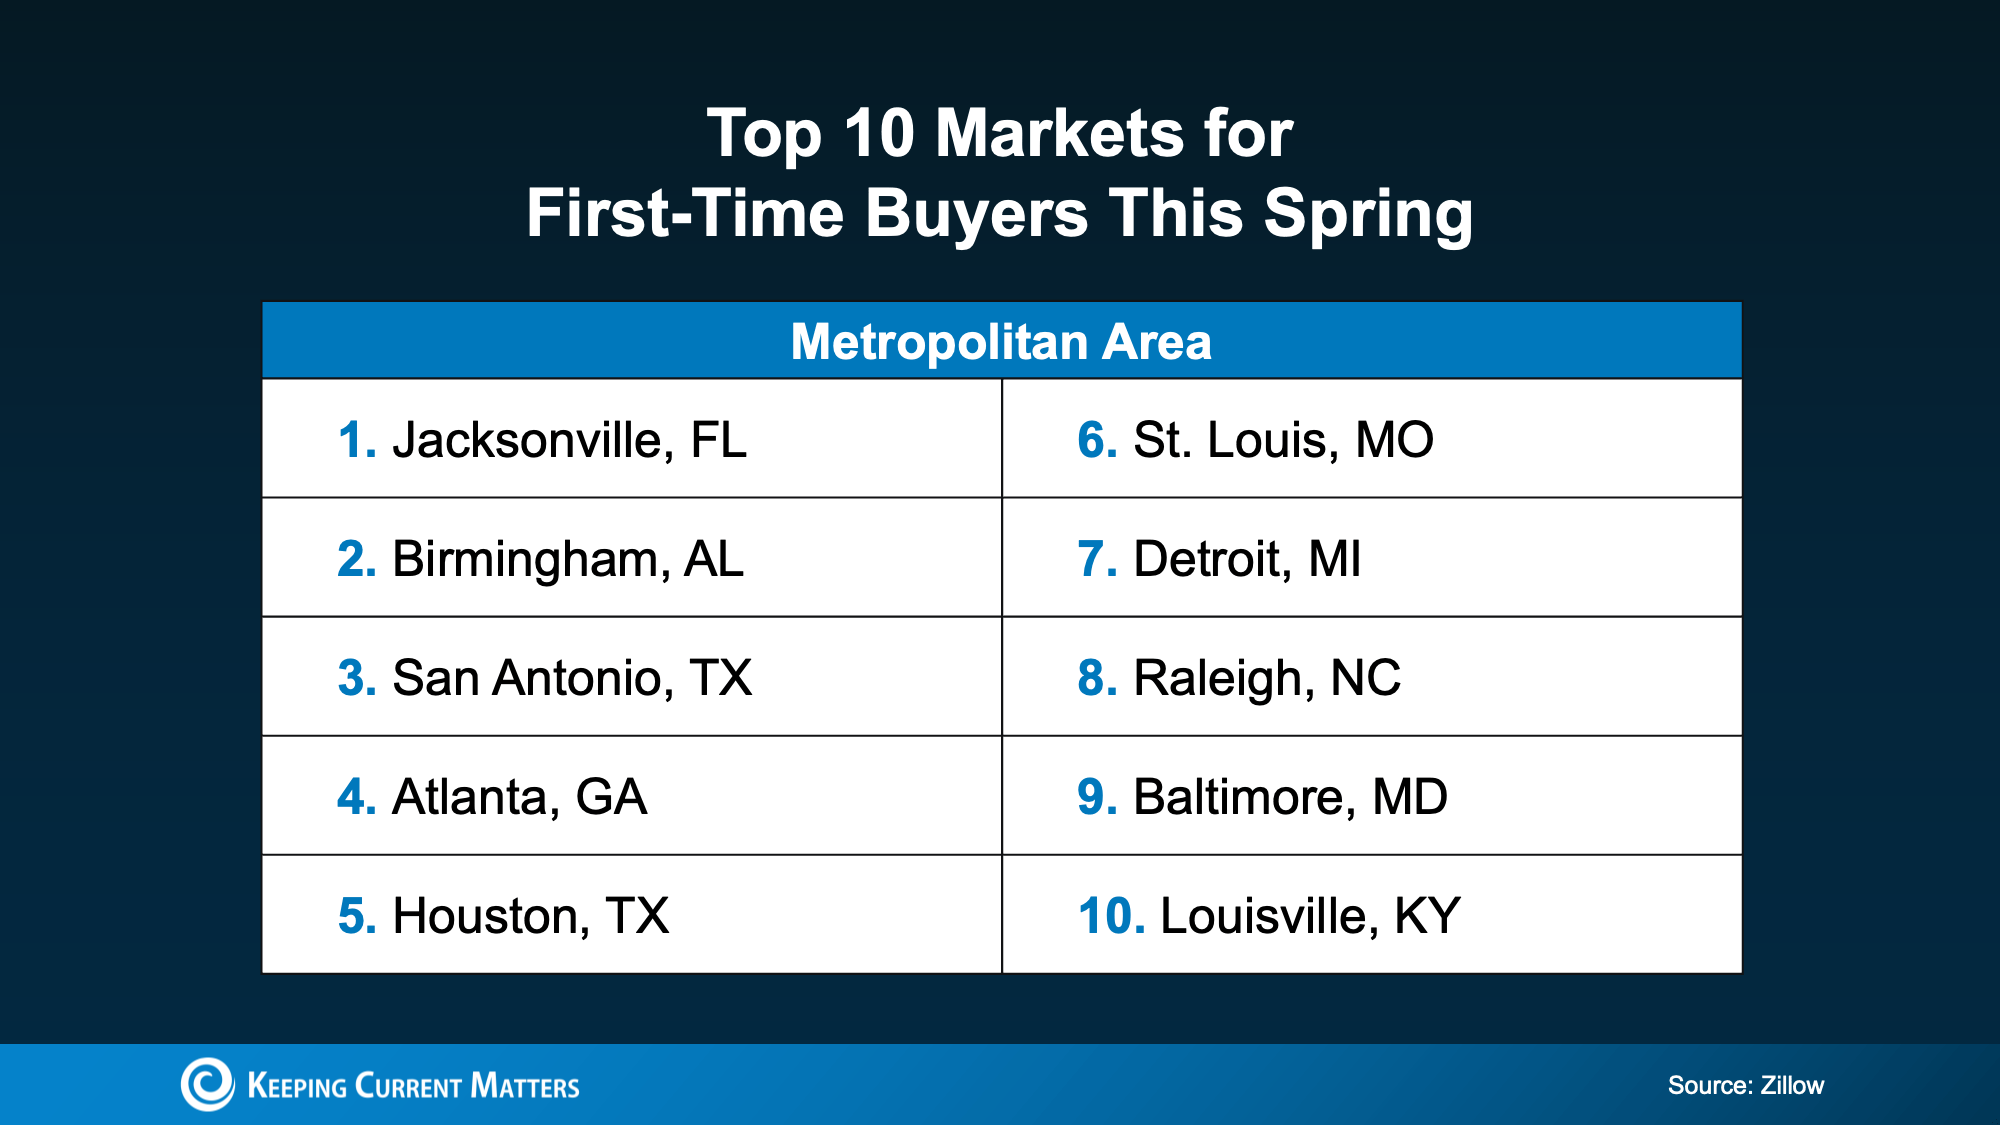
Here are Zillow’s top 10 best markets for new buyers in 2026:
- Jacksonville, FL
- Birmingham, AL
- San Antonio, TX
- Atlanta, GA
- Houston, TX
- St. Louis, MO
- Detroit, MI
- Raleigh, NC
- Baltimore, MD
- Louisville, KY
In these higher-ranked metros, Zillow says median-income households can afford 68% of all homes currently for sale.
This is a major shift, and one that could give buyers real options in some areas.
Not long ago, many buyers felt lucky to find even a few homes within reach. Today, in some markets, there are finally more realistic options for first-time buyers trying to break into the market.
What Makes These Housing Markets Stand Out?
These markets aren’t becoming more favorable for any single reason. Rather, several smaller trends are beginning to work together.
As Orphe Divounguy, Senior Economist at Zillow, explains:
“First-time buyers are finally seeing some light at the end of the tunnel. Affordability is still a challenge, but rising incomes, stabilizing prices and improving inventory are creating real opportunities in parts of the country. In the strongest markets for first-time buyers, they’ll find more choices, less competition and a clearer path to homeownership than they’ve had in years.”
That shift comes down to three key factors:
1. More Homes Are Coming to Market
According to Realtor.com, housing inventory is up 8.1% compared to last year.
More homes for sale means buyers have more choices. It can also reduce the pressure that comes with low-inventory markets, where bidding wars and quick decisions often make it harder for new buyers to compete.
2. Home Price Growth Is Slowing
While affordability is still a challenge in many areas, home prices aren’t rising as quickly as they were in recent years.
Slower price growth can help keep more homes within reach, and in some markets, prices may even be easing enough to bring new neighborhoods back into play.
3. Incomes Are Rising
Wage growth is also helping improve the picture for buyers.
When household income increases, it can offset part of the affordability challenge, even when mortgage rates remain elevated. As Mark Fleming, Chief Economist at First American, explains:
“Income growth has outpaced house price growth for 19 straight months, boosting house-buying power even as mortgage rates remain elevated.”
Taken together, these trends are creating better conditions for new buyers in select markets across the country.
What If Your Market Didn’t Make the List?
If your city did not make Zillow’s top 10, or even the top 50, there’s no reason to worry. You’re not out of options.
Opportunities exist in any market. The key is knowing where to look and having the right guidance along the way.
Even within the same metro area, one buyer’s experience can be very different from another’s. A lot depends on local knowledge and strategy. The right real estate agent can help you identify overlooked opportunities, such as:
- Neighborhoods where prices have not climbed as fast.
- Areas with more available inventory.
- New construction communities offering builder incentives.
These kinds of opportunities may not make national headlines, but they can make a meaningful difference when trying to buy your first home.
Bottom Line: More Options for First-Time Home Buyers
For a long time, first-time home buyers have felt stuck, waiting for the market to shift in their favor.
This spring, that may finally be happening in certain markets.
With more inventory, slower price growth, and rising incomes, buying a first home may feel more realistic than it has in years. And even if your market isn’t on Zillow’s list, there may still be neighborhoods or communities nearby offering a better chance to get started.
If you want to find out where those opportunities exist in your local market, connect with a trusted real estate agent who knows where to look.
Is an Adjustable-Rate Mortgage Right for You? A Homebuyer’s Guide
If you’ve been shopping for a home lately, you’ve likely felt the pressure of today’s affordability challenges. Higher home prices and mortgage rates have made it harder for many buyers to stay within budget. That’s one reason adjustable-rate mortgages, or ARMs, are getting more attention again.
For some homebuyers, an ARM can offer welcome savings upfront. But before you go that route, it’s important to understand how these loans work, why they appeal to certain buyers, and what the long-term risks might be.
What Is an Adjustable-Rate Mortgage?
An adjustable-rate mortgage is a home loan that starts with a fixed interest rate for a set number of years. After that initial period ends, the rate can adjust at scheduled intervals based on market conditions.
As Business Insider explains:
“With a fixed-rate mortgage, your interest rate remains the same for the entire time you have the loan. This keeps your monthly payment the same for years . . . adjustable-rate mortgages work differently. You’ll start off with the same rate for a few years, but after that, your rate can change periodically. This means that if average rates have gone up, your mortgage payment will increase. If they’ve gone down, your payment will decrease.”
That’s the biggest difference between a fixed-rate mortgage and an ARM. A fixed-rate loan offers predictability, while an ARM may give you a lower payment at first but less certainty later.
It’s true that costs like property taxes and homeowners insurance can still change with a fixed-rate mortgage. But the principal and interest portion of the payment generally stays steady. With an ARM, your monthly payment can rise or fall once the fixed period ends.
Why More Home Buyers Are Considering ARMs
The main reason buyers look at adjustable-rate mortgages is simple: lower initial costs.
Business Insider puts it this way:
“Because ARM rates are typically lower than fixed mortgage rates, they can help buyers find affordability when rates are high. With a lower ARM rate, you can get a smaller monthly payment or afford more house than you could with a fixed-rate loan.”
That upfront savings can matter, especially in a market where every dollar counts. Recent reporting from Mortgage News Daily and The Wall Street Journal show that ARM rates have been coming in lower than 30-year fixed mortgage rates.
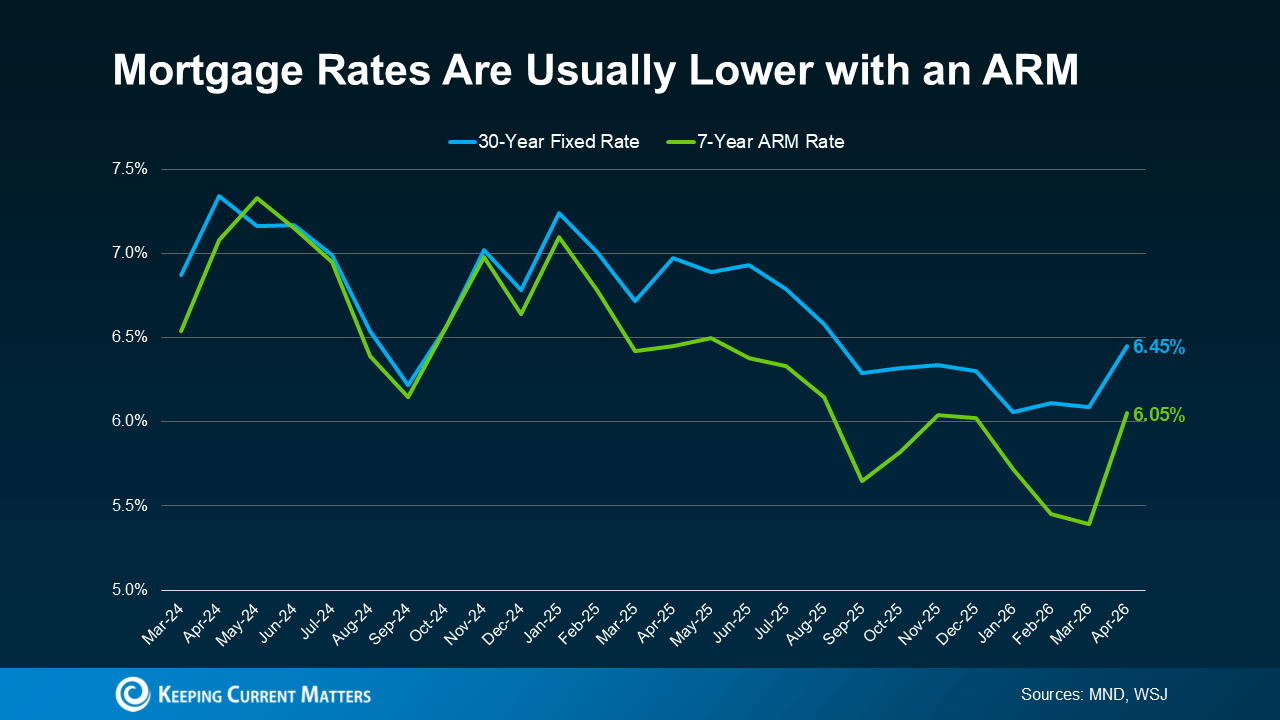
For many buyers, even modest monthly savings can make a difference. For example, Redfin found that a typical buyer could save about $150 per month by choosing an ARM instead of a 30-year fixed mortgage. Savings like that can help some buyers qualify for a home sooner or make their monthly budget more manageable.
Why Adjustable-Rate Mortgages Are Making a Comeback
More homebuyers are deciding that a lower payment today is worth considering, even if it means taking on more uncertainty later.
Recent reports from the Mortgage Bankers Association (MBA) show that the share of buyers choosing ARMs has increased in recent years. That doesn’t mean ARMs are becoming the right fit for everyone. But, it shows that some buyers are using them as a strategy to deal with affordability challenges in the current market.
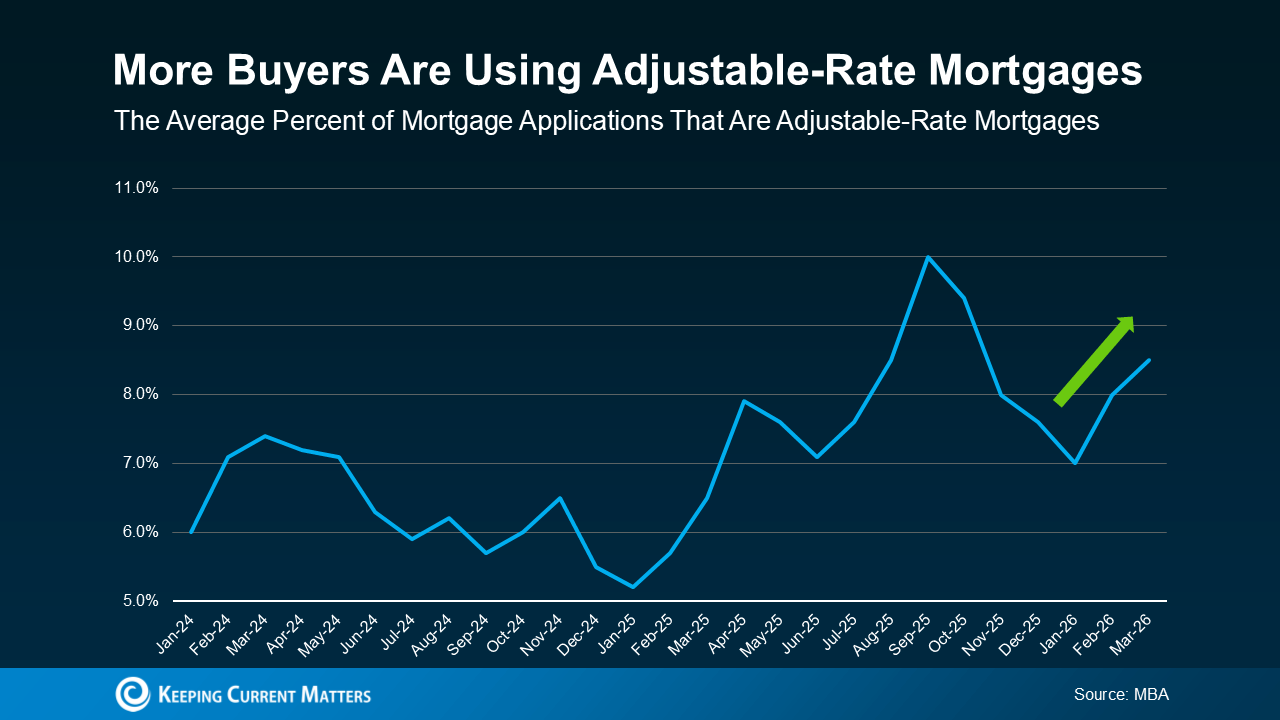
For anyone who remembers the 2008 housing crash, this trend may sound concerning at first. But today’s lending environment is very different.
In the past, some borrowers were approved for loans they couldn’t realistically afford once the interest rate adjusted. Today, lending standards are tighter, and lenders generally evaluate whether borrowers could still manage the payment if rates rise. So while ARMs are becoming more common again, that alone doesn’t point to another housing crisis.
The Pros and Risks of an ARM
An adjustable-rate mortgage can make sense in the right situation, but it depends on your financial plan and your comfort with risk.
An ARM may be worth considering if:
- You expect to move before the rate adjusts.
- You believe your income will increase over time.
- You need a lower initial payment to make homeownership possible now.
Still, there are trade-offs to consider.
Once the fixed-rate period ends, your interest rate can change, and your monthly payment could increase significantly depending on where mortgage rates are at that point. There’s also no guarantee rates will fall in the future, which means refinancing later may not be as easy or as beneficial as some buyers hope.
That’s why it’s important to think beyond the introductory rate. Make sure you understand how long the fixed period lasts, how often the rate can adjust, and how much your payment could increase over time. Most importantly, talk through your options with a trusted lender and financial advisor before making a decision.
Bottom Line: Is an ARM Right for You?
Adjustable-rate mortgages are regaining popularity because they can make buying a home more affordable in the short term. For some buyers, that lower upfront payment can be a helpful tool. But an ARM isn’t necessarily the right move for everyone.
The best decision comes down to understanding how the loan works, weighing the risks, and making sure it fits your long-term goals.
If you’re considering an adjustable-rate mortgage yourself but are still on the fence, reach out to us today. We can connect you with a qualified lender in your area who explore your options with you.
Mortgage Rate Volatility: What You Can Control as a Buyer
Mortgage rates have been moving up and down lately, and that can make buying a home feel harder to plan for. When rates are unpredictable, many buyers wonder whether they should wait, move forward, or try to time the market.
Here’s the good news: while you can’t control where mortgage rates go next, you can control several factors that may help you secure a better rate. The first step is understanding what’s driving today’s market and knowing where to focus your time and effort.
Mortgage Rate Volatility Is Normal
Recent data from Freddie Mac show that mortgage rates have been fluctuating. After trending downward for well over a year, rates ticked up again this month.
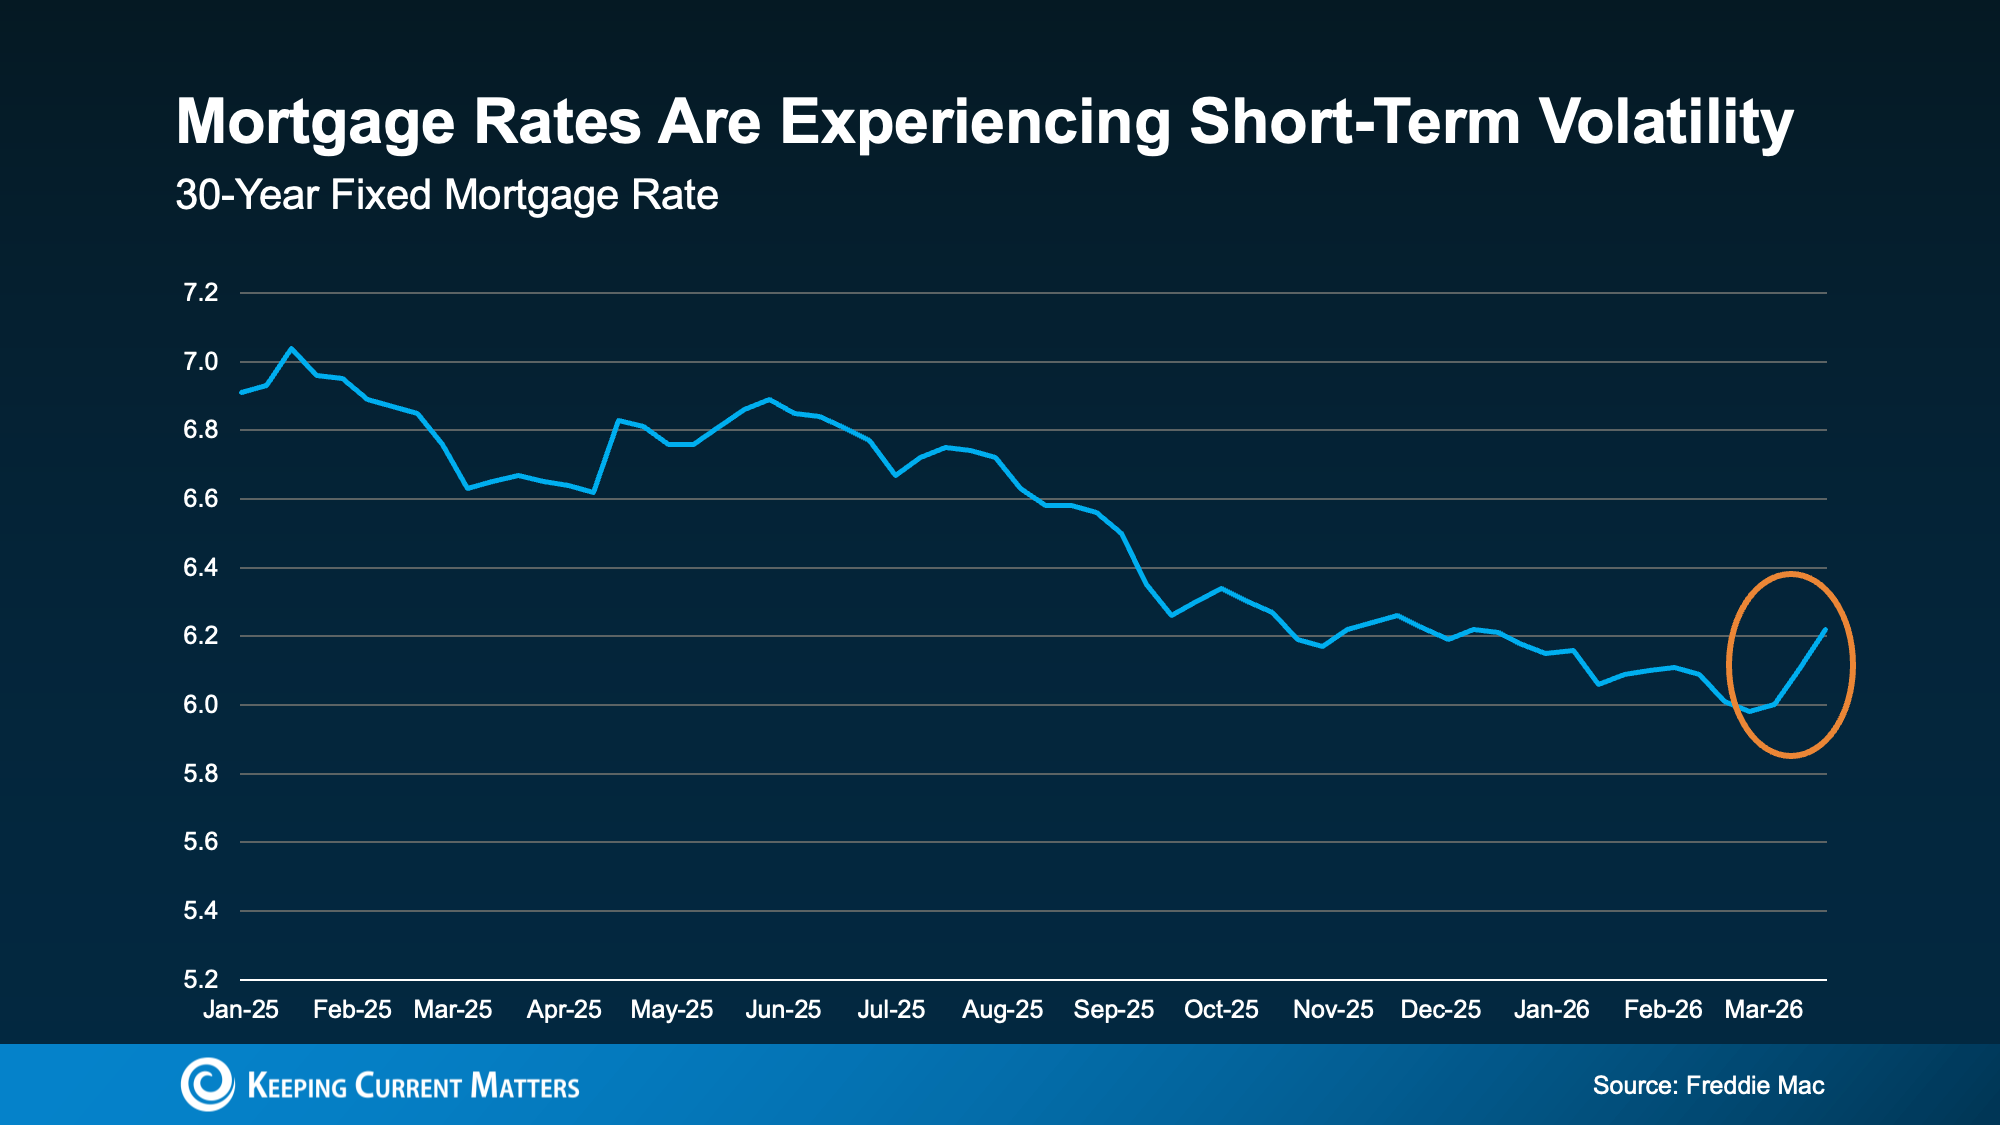
That kind of movement can feel frustrating, especially when you’re doing your best to budget for a home purchase. But occasional increases and decreases are a normal part of the mortgage market. Even over the past year, there have been periods when rates jumped before settling back down.
This is another one of those moments, and it helps to keep that in mind.
When there’s economic uncertainty or major global events unfolding, mortgage rates often respond quickly. As Investopedia explains:
“Mortgage rates don’t move in isolation. When global events inject uncertainty into financial markets . . . that can ripple through to borrowing . . . mortgage costs can respond quickly to geopolitical developments. As long as uncertainty remains elevated, rate swings may continue.”
That’s exactly why trying to predict the perfect time to buy usually doesn’t pay off. Rates can change fast, and waiting for the market to cooperate may not give you the outcome you want.
Focus on What You Can Control
You may not be able to influence the market, but you can take steps put yourself in a better position as a buyer. If your goal is to get the best mortgage rate possible, these are the areas that matter most.
Your Credit Score
Your credit score is one of the biggest factors that affects the rate you qualify for. In many cases, even a modest improvement in your score can lead to better loan terms and a lower monthly payment.
As Bankrate explains:
“Your credit score is one of the most important factors lenders consider when you apply for a mortgage. Not just to qualify for the loan itself, but for the conditions: Typically, the higher your score, the lower the interest rates and better terms you’ll qualify for.”
That’s why it’s worth taking steps to strengthen your credit before applying for a mortgage. Paying bills on time, reducing outstanding debt, and avoiding new credit inquiries can all help. If you’re not sure where your score stands or what improvements would make the biggest difference, a trusted loan officer can help you create a plan.
Your Loan Type
The type of mortgage you choose also affects your rate. There are many different types of loans, and each comes with different eligibility requirements, benefits, and pricing.
The Consumer Financial Protection Bureau (CFPB) explains:
“There are several broad categories of mortgage loans, such as conventional, FHA, USDA, and VA loans. Lenders decide which products to offer, and loan types have different eligibility requirements. Rates can be significantly different depending on what loan type you choose.”
This is why exploring your mortgage options is so important. A conventional loan may be the right fit for one buyer, while an FHA, USDA, or VA loan may offer better advantages for another. Comparing programs and speaking with more than one lender can help you understand which path makes the most sense for your financial situation.
Your Loan Term
The length of your loan term matters, too. Most lenders offer 15-year, 20-year, and 30-year mortgage options, and the term you choose can affect both your interest rate and your monthly payment.
Freddie Mac explains it this way:
“When choosing the right home loan for you, it’s important to consider the loan term, which is the length of time it will take you to repay your loan before you fully own your home. Your loan term will affect your interest rate, monthly payment, and the total amount of interest you will pay over the life of the loan.”
A shorter loan term may come with a lower interest rate, but the monthly payment is often higher. A longer term may give you more flexibility in your monthly budget, even if you pay more interest over time. The right choice depends on your goals, your budget, and how long you plan to stay in the home.
Conclusion
If you’re in the market for a home right now, the best strategy is not to focus on trying to predict where mortgage rates will go next.
Instead, focus on what you can control. Improve your credit score, explore different loan types, and choose a loan term that fits your needs. Most importantly, work with a trusted lender who can guide you through your options. If you need help connecting with trustworthy lender, reach out to us today.
Mortgage rates may be out of your hands, but the steps you take to prepare are not. And when you focus on what you can change, you give yourself a much better chance to move forward with confidence.
3 Key Steps for First-Time Home Buyers
Buying your first home is exciting, but it can feel a bit overwhelming. When you’ve never gone through the buying process before, it’s easy to wonder where to start and what to do first.
The good news is that you don’t need to figure out everything out on your own, or all at once. The best approach is to take it all step by step.
If you’re getting ready to buy your first home, here are the three most important steps to focus on first.
1. Build Your Team: Don’t Do It Alone
Buying a home is not a solo project. Having the right professionals on your side can make the entire experience smoother, less stressful, and more successful.
Here are two key people every first-time home buyer should have in place early:
A local real estate agent
A knowledgeable local agent will guide you from your first showing all the way to closing day. They can help you understand the market, explain each step of the process, and make sure you feel confident in the decisions you make.
A trusted lender
A lender will help you explore your mortgage options, estimate your monthly payment, and understand what price range makes sense for your budget. Having that info early helps you shop smarter and avoid unwanted surprises later.
When you have the right team in place, you can find your new home with more clarity and confidence.
2. Prep Your Finances: Build a Strong Foundation
It goes without saying that your finances play a major role in the homebuying process. They affect what you can afford, how competitive your offer may be, and how comfortable you’ll feel once you own the home.
Here are the main financial steps first-time home buyers should take:
Check your credit score
Your credit score can affect the loan programs available to you and the mortgage rate you receive. Checking it early gives you time to improve it if needed.
Save for your down payment and closing costs
Many buyers focus only on the down payment, but closing costs are also an important part of the equation. Saving for both can help reduce last-minute stress.
Research first-time buyer assistance programs
There are programs designed to help first-time home buyers with upfront costs. Depending on where you live and your financial situation, you may qualify for assistance that helps you buy sooner than expected.
Talk to a lender about your mortgage options
Fixed-rate, adjustable-rate, FHA, VA, and conventional loans all work differently. Understanding the pros and cons of each option can help you choose the loan that best fits your needs.
Get pre-approved
A mortgage pre-approval gives you a clearer picture of how much a lender may be willing to lend you. It also helps you set a realistic price range and shows sellers you’re serious when it’s time to make an offer.
Set a realistic monthly budget
Your mortgage payment is only part of the cost of homeownership. You also need to account for utilities, home insurance, maintenance, and everyday living expenses. Setting a realistic budget helps ensure your home feels affordable, not overwhelming.
Being confident in your finances before you start house hunting can help you feel more prepared and better positioned in a competitive market.
3. Gather Your Documents: Save Time and Reduce Stress
Once you’re ready to move forward, your lender will need to verify your income, assets, and financial history. Gathering your documents ahead of time can help speed up the loan process and avoid unnecessary back-and-forth.
Here are some of the most common documents lenders may ask for:
W-2s and tax returns from the past two years
These help verify your income history and show consistency over time.
Recent pay stubs, usually from the last one to two months
These confirm your current income and employment.
Bank statements from the past two to three months
These show your available funds, spending patterns, and where your down payment money is coming from.
Investment account statements from the past two to three months
If investments are part of your financial picture, your lender may want to review them as well.
A copy of your driver’s license
This is used to verify your identity during the loan process.
Your residential history for the past two years
Lenders may request this to confirm your housing background and stability.
Statements for outstanding debts from the past two months
This may include student loans, car loans, and credit cards. These debts help lenders calculate your debt-to-income ratio.
Proof of supplemental income
If you receive bonuses, commissions, freelance income, or child support, you may need documentation to show that income can be counted.
Keep in mind that document requirements and timelines can vary by lender. Still, having these items ready is a smart way to stay organized and avoid potential hiccups.
Conclusion
Buying your first home doesn’t mean you need to have every detail figured out from day one. It just means starting your journey with a plan.
When you gather the right people, prepare your finances, and organize your documentation early, you give yourself a much better chance to buy with confidence.
If you want help understanding any part of the process or are ready to take the first step to homeownership, connect with a trusted real estate agent.